Third charge secured loans: how they work and risks


Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
If you’re thinking about a third charge secured loan, also called a third charge mortgage, you’re in the right place.
You're not alone, and we understand your worries.
In this easy guide, we’ll look at:
- What a secured loan is.
- The cost of a bad secured loan.
- How you can get a secured loan, even if you already have one.
- Important things to think about before taking a third charge loan.
- Other choices instead of a third charge secured loan.
A third charge secured loan is an extra loan that is linked to your house. It’s taken after a first and second charge mortgage. This can feel a bit risky, but we’re here to help you understand it better.
Let’s learn about third charge secured loans together.
Can you have more than two secured loans?
More than one loan can be secured on the same property, subject to lender consent, charge priority, sufficient security and affordability.
A first, second and third charge can all use the same property as security. Equity is a measure of value remaining after secured debts, not a different asset that avoids priority rules.
How many loans can you have at once?
There is no simple fixed maximum number of charges, but legal restrictions, lender consent, security and affordability can prevent further borrowing.
Lenders assess your debt-to-income ratio to ensure that any loan they approve would be affordable to you. If you already have a secured loan, the repayments on that loan will be considered by the other lender, who may decide that another loan is unaffordable. From my experience, lenders will also assess your credit file before deciding.
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Can there be more than one charge on a property?
Yes, you have more than one charge on a property.
A first charge usually has priority over later charges. It may be a purchase mortgage or refinancing; a let property requires the lender’s consent and a product that permits the use.
As payments are made, the amount of equity you have in the property will increase. Home equity can be calculated by subtracting the debt from the current property value. So, the smaller your debt – i.e. mortgage – becomes, the more equity you will have. The only time this may not be the case is if the property value declines.
A second charge is a separate loan secured on the same property behind the first charge, subject to legal priority and consent arrangements.
Enquire about a secured loan through Loans Warehouse, a credit broker, not a lender. Approval and terms depend on checks. Compare the full cost before applying. MoneyNerd may receive a referral fee. Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Can you take out a third loan?
A third charge is further borrowing secured on a property already subject to two prior charges. Availability is limited and all existing debt must be disclosed.
As I see it, getting a third charge against the same property can be difficult. It’s more likely if there is significant home equity in the property that isn’t already secured in other loan agreements. Moreover, multiple charges can be risky. If you miss payments, you could lose your home. Not to mention, additional interest can add up if you continue to miss payments and don’t pay them back.
Interest rates
The interest rates for third – and second – charge loans are often higher than for first-charge loans. Furthermore, the interest rates for a third charge loan are usually higher than a second charge loan because the second charge takes priority. Third charge loan interest rates are often high due to the increased risk.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. Securing borrowing against your home puts it at risk if you cannot keep up repayments.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
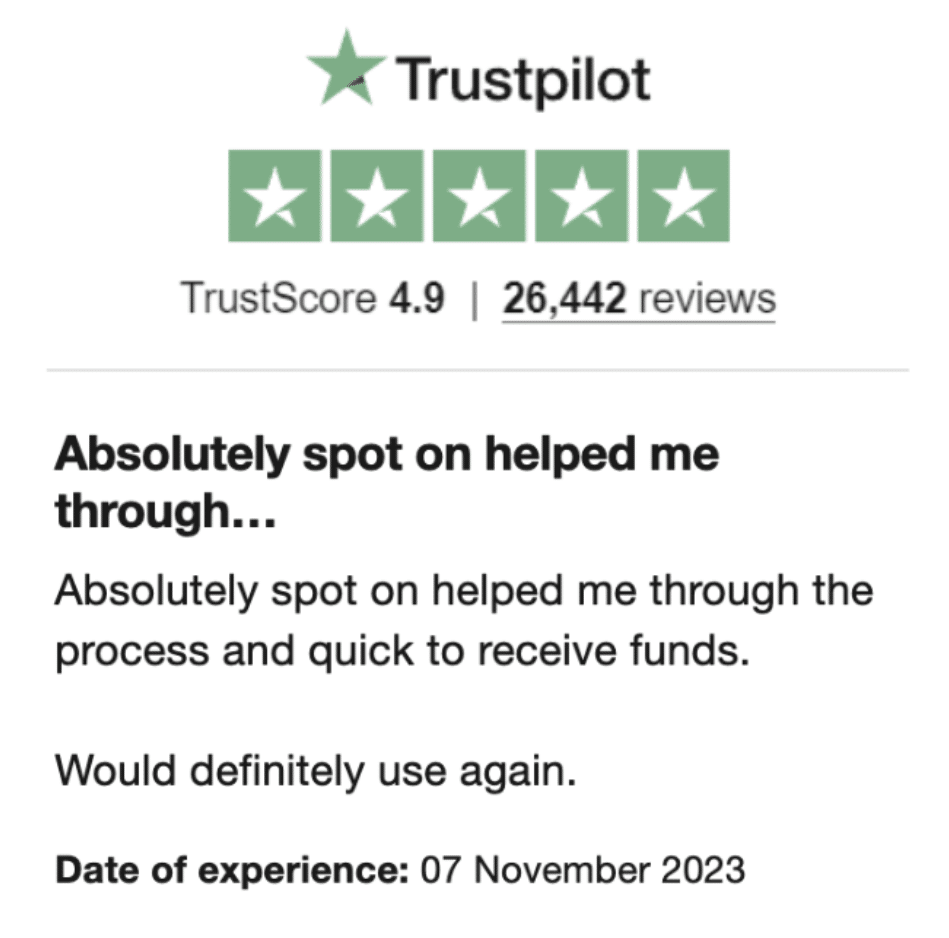
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
How many charges can you have?
Further charges depend on title restrictions, the terms of existing charges and lender acceptance. Do not assume there is an unlimited right to keep adding secured loans.
It’s not impossible, though. Someone could own a £500,000 property with no existing mortgage and multiple home equity loans for smaller amounts against their equity.
Things to consider
As mentioned, it can be difficult to get a third charge loan because lender criteria becomes stricter with each loan you try to take out against your property.
Assess all repayments, fees and the consequences of default. Short-term borrowing also needs a credible exit and contingency plan; future property growth or refinancing cannot be guaranteed.