Pros and Cons of Lifetime Mortgage


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
Are you thinking about getting a lifetime mortgage? You've come to the right place.
In this guide, we will:
- Explain what a lifetime mortgage is.
- Show how a lifetime mortgage works.
- Discuss the good and bad points of a lifetime mortgage.
- Tell you where to get a lifetime mortgage.
- Talk about what happens when a lifetime mortgage ends.
Home improvements are one possible use of released funds. Historic survey percentages need a dated source and should not be described simply as last year’s results.
If you’re considering a lifetime mortgage for similar reasons, it’s important to weigh its pros and cons before deciding.
Don’t worry, we’re here to help. Let’s find out more about lifetime mortgages together.
Regulation of Lifetime Mortgages
The Financial Conduct Authority regulates lifetime mortgage providers.
The FCA are responsible for ensuring that they are sold fairly with transparency and have specific rules and guidelines that must be followed.
Lenders must ensure that the borrower fully understands the costs of the lifetime mortgage option, including any fees and interest.
A no-negative-equity guarantee is a key standard for qualifying Equity Release Council lifetime-mortgage products. Do not assume FCA authorisation alone guarantees the same terms on every product.
For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
Lifetime Mortgage Advantages and Disadvantages
When you receive equity release advice from a financial advisor or consultant, the pros and cons of using a lifetime mortgage should be fully explained to you.
It is mandatory to receive professional equity release advice as part of the application process. This is to ensure you know what you could be signing up for.
But it’s also essential to know the pros and cons of lifetime mortgages early by doing your own research – which is why you’re reading this guide.
So let’s get into them…
Equity release enquiry: Continue to the equity release enquiry
Advertisement. In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
What are the pros of a lifetime mortgage?
The lifetime mortgage pros are:
- You can still get a loan in your latter years. Many loan providers won’t lend to people near retirement age or in retirement.
- The amount available depends on the product, age, property and lender criteria; there is no universal 60% maximum.
- Many lifetime mortgages allow interest to roll up without regular payments, but some require interest payments for a set period. Optional repayments, limits and any early-repayment charges depend on the contract.
- You might only pay off the debt after you die.
- Permitted use depends on the provider and suitability assessment; gifts, debt repayment and investments need particular care.
It is important to ensure that the provider is a member of the Equity Release Council, previously known as SHIP.
The role of the Equity Release Council is to promote high standards of conduct and ethics in the equity release sector.
Guidelines include providing the borrower with clear information, including all risks associated with equity release.
Check the particular plan against the applicable Council standards and ask the adviser to identify exceptions. Regulated advice and independent legal advice are separate safeguards.
What are the downsides of a lifetime mortgage?
The main downsides to a lifetime mortgage are:
- Some properties don’t qualify
- The debt can grow at a fast rate making it expensive to repay
- Exiting the loan early can be difficult due to early repayment charges
- The debt reduces estate equity, but a sale or loss of the entire home inheritance is not inevitable if the debt can be settled from other funds.
- Retained funds can affect means-tested support. Drawdown does not guarantee continued entitlement; get advice about capital limits, disregards and deprivation rules.
- The loan approval process includes fees, such as administration, valuation, legal, and interest charges. If you end your lifetime mortgage early, there could be early repayment charges.
Consider the costs and risks of equity release
Equity release is a long-term decision. A lifetime mortgage is secured against your home. Adding interest can substantially increase the debt and reduce your inheritance.
Consider fees, means-tested benefits, early repayment charges and future care needs. Alternatives include downsizing, other assets or a retirement interest-only mortgage where affordable.
Start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
Advertisement. MoneyNerd introduces enquiries to Age Partnership, which advises on lifetime mortgages, and may receive a referral fee.
Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply. Interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Is it worth getting a lifetime mortgage?
“My friends wince when I mention lifetime mortgages”
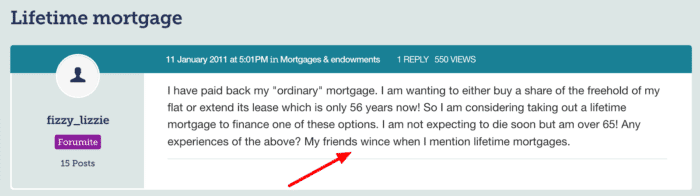
Source: https://forums.moneysavingexpert.com/discussion/2974692/lifetime-mortgage
This is how one forum user explained her experience considering a lifetime mortgage. And it’s not an uncommon scenario.
Lifetime mortgages have somewhat of a tarnished reputation due to some horror stories. But the industry and products have vastly improved over the last decade.
Ultimately, the decision to get a lifetime mortgage should be based on your needs and preferences while being fully aware of the pros, cons and long-term impact on your estate beneficiaries.
Before deciding on a lifetime mortgage, please consider the following steps.
- Do your research about the types of lifetime mortgages and how they work, weighing up the pros and cons of each option.
- Seek independent, professional financial planning advice from a qualified advisor or a mortgage broker who can help you find the best option for your circumstances.
- Consider the possible alternatives, such as downsizing or using any other savings.
- Research lenders carefully, making sure that they are registered with the FCA.
- Understand the fees and interest rates.
- Please review the terms and conditions, ensuring you fully understand them.
Are there any alternatives?
Yes, there might be alternatives to a lifetime mortgage for you, such as home equity loans or downsizing to create funds.
The alternatives available to you will depend on your circumstances, especially your age. Organisations such as the Citizens Advise Bureau may also provide helpful advise.
Your equity release adviser will discuss the lifetime mortgage alternatives that are available to you in your compulsory meeting.
Equity release comparison
When exploring equity release options such as lifetime mortgages, it’s important to consider alternatives as well.
Let’s take a closer look at another viable option: home reversion plans. Below, there’s a comparison table to help you evaluate both approaches effectively.
| Category | Home reversion plan | Lifetime mortgage |
|---|---|---|
| Ownership | You sell part or all of the home, usually for less than open-market value, and remain under the plan’s occupancy terms. | You retain ownership and borrow against the home. |
| Property value changes | The provider receives the agreed share of future sale proceeds; only any retained share belongs to your estate. | Sale value and the outstanding loan, interest and charges affect the amount left for your estate. |
| Inheritance | Selling a share reduces what you can leave; any protected share and conditions must be checked. | Rolled-up interest can reduce the remaining equity. Inheritance protection may be available under some plans. |
| Repayment | There is no loan to repay for the sold share; the provider receives its share when the property is sold under the plan. | Usually settled when the last borrower dies or moves permanently into care. Payment options and obligations vary. |
| Money received | A lump sum or income may be available, depending on the plan. | A lump sum or agreed drawdown reserve may be available; access remains subject to the plan terms. |
References