Debt Info

Can a Sold Debt Appear Twice on Your Credit Report?

Scott Nelson MoneyNerd Janine Marsh MoneyNerd
By
Scott
Scott Nelson MoneyNerd

Scott Nelson

Founder of MoneyNerd

Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

Learn more about Scott
&
Janine
Janine Marsh MoneyNerd

Janine Marsh

Former MoneyNerd Contributor

Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.

Learn more about Janine
· Oct 4th, 2026

Advertisement

Request a call from The Debt Advice Service

Total amount of debt?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
same debt defaulted twice

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.

Are you wondering if the same debt can be defaulted twice? You’ve come to the right place for answers! Each month, over 170,000 people visit our website to understand debt problems just like this one.

In this article, we’ll show you:

  •  What a defaulted debt means
  •  If a debt can be defaulted twice
  •  How an old debt might show up in your credit report
  •  Steps you can take if you’re struggling with debt

We know that dealing with debt can be hard; some of us have been there too. But don’t worry! We’re here to help you understand your debt situation better.

Advertisement

Request a call from The Debt Advice Service

Tell us how much debt you have to continue to the enquiry form. Options depend on your circumstances.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Is it possible to happen?

A debt sale can lead to entries from both the original lender and the buyer. What matters is whether they accurately show one debt and preserve its original default date.

Two linked entries are not automatically two separate defaults or two amounts you must pay.

The ICO explains that recording both entries can be fair where their connection is clear, the original entry is marked settled and the original default date is retained.

Advertisement

Debt advice: Continue to the debt enquiry form

Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
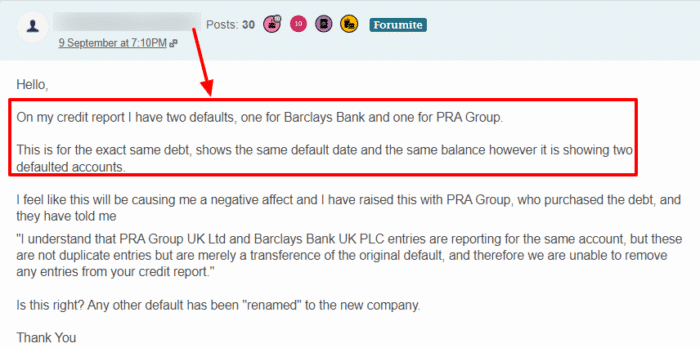
The buyer must not restart the credit-file reporting period by giving the same defaulted debt a later default date merely because it bought the account or a repayment arrangement was missed.

Can the same debt be defaulted twice
Source: MSE Forum.

For any example involving a lender and debt buyer, compare the account details, original default date, transferred balance and status before deciding whether the record is wrong.

A file should not misleadingly show two separate outstanding debts or keep the debt visible longer than six years from the original default date because it was sold.

A defaulted account normally drops off six years from that original default date. This reporting rule is separate from whether the debt can still be collected or enforced.

Can an old debt reappear on your credit report UK?

A removed default should not be re-registered with a new date simply because the debt is sold or a payment is made.

A later CCJ can be recorded separately if the creditor obtains a judgment through a legally available claim. Whether a claim is statute-barred depends on the relevant jurisdiction, debt type and history, not just the credit-file default date.

The judgment would be a separate public-record entry, not a lawful restart of the original default’s reporting period.

Advertisement

How the introduction works

The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.

Options depend on your circumstances. You decide whether to proceed.

Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Double default

After a sale, the original lender’s entry should show the transfer or settlement appropriately, while the new owner may report the remaining balance.

The buyer’s default date should match the original one. Keep copies of both entries and ask for correction if the reporting suggests extra debt or a later default.

A duplicate-looking entry can result from how a transfer is reported. Do not assume every two-entry record is deliberately unfair, but challenge inaccuracies with evidence.

Data-protection accuracy and fairness requirements apply. Raise the issue with the organisation supplying the data and the credit-reference agency; unresolved data concerns can be taken to the ICO.

The next steps

A credit-file default is not itself a demand for immediate repayment. The lender’s contractual rights and any required statutory notices determine what recovery action can follow.

Offer only affordable payments and explain financial difficulty. FCA-regulated firms must consider appropriate forbearance and cannot operate a blanket refusal to negotiate repayment plans.

The further action that a creditor can take against you after your account has been defaulted can involve:

  • Passing the debt on to a debt collection agency,
  • Taking court action against you and,
  • If the debt was a ‘hire purchase’, they can apply to the court to take back the goods under said purchase.

For financial difficulty, see FCA CONC 7.3. For inaccurate entries, use the ICO guidance above and keep evidence of your complaint.

A Consumer Credit Act default notice is a separate legal document from a default entry on your credit report. Read any notice and court papers promptly rather than relying on a credit-file dispute to pause recovery.

Advertisement

About The Debt Advice Service

Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.
Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Advertisement

Request a call from The Debt Advice Service

Tell us how much debt you have to continue to the enquiry form. Options depend on your circumstances.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Did you like this article?
Show your support ❤️
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
We are so sorry...

Is there something missing? We’re all ears and eager to improve. Send us a message and let us know how we can make our article more useful for you.

You can email us directly at [email protected] to share your feedback.

The authors
Scott Nelson MoneyNerd
Author
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
Janine Marsh MoneyNerd
Debt Expert
Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.