Further Advance on Mortgage – How to Increase Your Loan


Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
A further advance is the process of borrowing more from your current mortgage provider. Unlike the process of remortgaging, getting a further advance doesn’t mean that you have to switch mortgage deals.
But, for your application to be successful, you need to meet strict eligibility criteria. Sounds confusing? Don't worry, you're in the right place.
In this easy-to-understand guide, we’ll explore:
- What a further advance on a mortgage is.
- The difference between a remortgage and a further advance.
- How a further advance can be used.
- If you can get a further advance on your mortgage.
- The time it takes to process a further advance.
Remember, you’re not alone in this. We’re here to support you with clear and simple advice. So, let’s get started and learn more about further advance mortgages together.
In a Nutshell
A further advance on a mortgage is when you extend the borrowing on your current mortgage. However, the additional borrowing could be subject to a different interest rate than your initial and outstanding mortgage loan.
The additional borrowing can have a different rate and term from the existing mortgage. Compare the total cost with other suitable options; a lower rate does not guarantee a cheaper loan.
But it’s still worth comparing a mortgage advance with other loan products on the market before asking for a further advance on your mortgage.
How does it differ from a remortgage?
The main difference between remortgaging to borrow more with your current or a different lender and taking a further advance on your existing mortgage is that the latter doesn’t force you to switch mortgage deals.
It’s possible to extend your borrowing by remortgaging your current deal and asking to borrow more if you have sufficient home equity to borrow against. This will mean completely switching the mortgage deal you currently have, and possibly switching lenders. You might have to pay early repayment charges by clearing the initial mortgage as well.
A further advance normally leaves the existing mortgage in place with the same lender. This may be useful if the existing rate is attractive, but the new borrowing has its own terms.
Keeping the existing mortgage unchanged can avoid an early-repayment charge on that part. The advance can still have fees and its own early-repayment charges; check both sets of terms.
On the other hand, if current mortgage deals are more attractive, it could be cost-effective to not ask for a further advance, and instead, remortgage your whole loan and simultaneously ask to borrow more as part of the process.
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Can I get it on my mortgage?
Whether you can get a further advance on your mortgage will depend on several considerations, including how much home equity you currently have, your credit rating and the affordability of the prospective larger mortgage.
Loan-to-value compares secured borrowing with the property’s value, not with the equity alone. A second-charge lender normally considers the existing mortgage and proposed loan together, alongside affordability and credit criteria. There is no universal percentage of equity you can borrow.
The lender sets a maximum loan-to-value and checks the total borrowing after the advance. There is no universal requirement to retain exactly 20% equity.
For illustration, a £200,000 home with a £160,000 mortgage is at 80% loan-to-value. If a particular lender caps total borrowing at 80%, there would be no room for an advance at that valuation before fees; a different limit gives a different result.
Eligibility can change as the balance, valuation, income or lender criteria change. A rise in property value is not guaranteed and waiting alone does not ensure approval.
The lender also checks affordability and credit history. A mortgage broker can explain available options; this guide does not establish that any named broker is the best. See related guidance.
Enquire about a secured loan through Loans Warehouse, a credit broker, not a lender. Approval and terms depend on checks. Compare the full cost before applying. MoneyNerd may receive a referral fee. Your home may be repossessed if you do not keep up repayments on a loan secured against it.
What can it be used for?
Further advances are most often used to help fund home renovations and improvements, but they’re also used to help top up a deposit for other property purchases, especially investment properties.
Here’s just one example of people thinking this way:
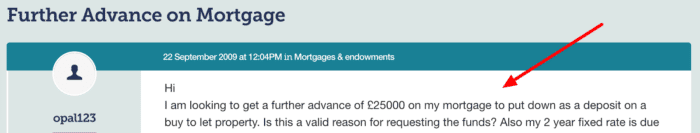
Source: https://forums.moneysavingexpert.com/discussion/1962821/further-advance-on-mortgage
Compare the total amount repayable, interest, all fees, the term and early-repayment charges. A lower monthly payment can mean a longer term and a higher total cost. Securing previously unsecured debt against your home puts the property at risk if you cannot keep up repayments.
Tell the lender the intended use and check its restrictions. Improvements may add value, but the increase is uncertain and may be less than the cost.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. A lower monthly payment may mean paying more overall, and secured borrowing puts your home at risk if repayments are not maintained.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
Getting it on a buy-to-let
Getting a further advance on an existing buy-to-let mortgage can be a little more tricky. Investment properties are considered a greater risk to banks, which is why you usually need a bigger deposit to get a BTL mortgage.
Buy-to-let further advances have lender-specific loan-to-value, rental-cover and other criteria. There is no universal requirement to retain 40% equity.
How long is the process?
Timing depends on the lender, documents, valuation and any legal checks. Ask for a case-specific estimate before committing to expenditure.