Welcome! Are you considering a second charge mortgage or wondering if it could affect your credit score? This guide is here to help.
This guide explains the main options, conditions and risks to discuss with a qualified adviser.
In this guide, we’ll explain:
- What a second charge mortgage is.
- The difference between first and second charge mortgages.
- The cost of a bad second charge mortgage.
- How to get a second charge mortgage.
- How much you can borrow on a second charge mortgage.
We know that taking out a second mortgage can be a big step – you may be worried about the costs or whether it will hurt your credit score. It’s normal to have these concerns, and it’s important to get the right advice. We’re here to support you with clear, easy-to-understand information.
What is a second charge mortgage?
A second-charge mortgage is borrowing secured on a property behind an existing first charge. Residential and buy-to-let lending have different eligibility and regulatory considerations.
The first mortgage need not have funded the original purchase. Both charges are security over the property; the available equity helps determine whether further borrowing is possible.
The second charge is usually paid out as a lump sum loan and then repaid via monthly repayments for a fixed period. This can be further understood by reading our second charge mortgage example.
There are different types of secured loans that fall under the umbrella of a second charge mortgage, such as a home equity loan or homeowner loan. We have discussed these different secured loans extensively, which you can find by heading back to our main secured loan page.
What is the difference between a first charge and second charge mortgage?
A first charge normally has priority over later charges on the same property. A second-charge mortgage creates a separate secured loan behind that first charge.
There are some other differences between first and second charge mortgages.
The first charge is considered the senior lien of credit, whereas second charges are considered the junior lien of credit.
Priority matters if the property is sold, including after repossession through the applicable legal process.
After applicable sale costs, secured creditors are generally repaid in their legal order of priority. The details can depend on the charges and any priority agreement.
In most cases, this shouldn’t be a problem. But if the homeowner/debtor is in negative equity, it could mean the second charge lender isn’t repaid in full.
Enquire about a secured loan through Loans Warehouse, a credit broker, not a lender. Approval and terms depend on checks. Compare the full cost before applying. MoneyNerd may receive a referral fee. Your home may be repossessed if you do not keep up repayments on a loan secured against it.
How does getting a second charge mortgage work?
You can take out a second charge mortgage on a residential home or investment property. It can be more difficult to get a second charge on a BTL if you also have a mortgage to pay on your home.
Loan-to-value compares secured borrowing with the property’s value, not with the equity alone. A second-charge lender normally considers the existing mortgage and proposed loan together, alongside affordability and credit criteria. There is no universal percentage of equity you can borrow.
As part of the application process, the lender may need to come and re-value your home.
Is a second charge mortgage more expensive?
A second-charge rate may be higher than a first-mortgage rate. Compare actual illustrations, including fees and total repayment, rather than assuming rates are comparable.
Even the better second charge mortgage rates can be more than a residential mortgage because second charges are the junior lien or credit and therefore have slightly more risk that a senior lien of credit in the first charge mortgage.
Both first and second mortgages may have fixed or variable rates. Inflation does not itself mean a variable mortgage rate will fall; payments can rise when the applicable rate increases.
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Who could benefit from a second charge mortgage?
Homeowners requiring significant credit could benefit from a second charge mortgage. It may not be suitable for some homeowners, especially if they only require a small loan. You may want to consider getting second charge mortgage advice before proceeding.
How much can I borrow on a second charge mortgage?
To work out your second charge mortgage borrowing power, you’ll need to work out how much home equity you have available.
You can do this by subtracting all debt secured by the property – including the first charge mortgage – away from its current market value. For example, a property worth £200,000 with a £50,000 outstanding mortgage has 75% home equity equivalent to £150,000.
Loan-to-value is based on the property value, not the equity alone. In the £200,000 property example, an assumed maximum combined LTV of 80% permits total secured borrowing of £160,000. Subtracting the £50,000 mortgage leaves £110,000 for an additional loan before financed fees, subject to affordability and lender criteria. See related guidance.
A calculator estimates payments using its stated amount, rate and term. It is not a lending offer, eligibility confirmation or suitability assessment. Compare the personalised terms and total cost before applying.
Why would you get a second charge mortgage?
You might decide to get a second charge mortgage for a variety of purposes.
Lenders can restrict permitted uses. Explain the purpose accurately and check the agreement before applying.
Can I get a second mortgage for home improvement?
A second charge may fund improvements, but their cost is not guaranteed to be recovered through a higher property value. The additional loan also reduces net equity.
Compare project quotes, contingencies, the total borrowing cost and alternatives. A product marketed for home improvements still puts the home at risk if secured payments are missed.
Can I get a second mortgage to buy another property?
Some lenders may allow a second-charge loan to help fund another property, subject to checks. The new mortgage lender must know if the deposit is borrowed. “Soft second mortgage” commonly describes overseas assistance schemes and is not a standard UK product category.
Can I get a second mortgage to pay off debt?
Yes, a second charge mortgage can be used to pay off single or multiple other debts. This is known as debt consolidation.
A second charge mortgage debt consolidation loan is any second charge loan that is taken out for the primary purpose of clearing existing debts, such as other secured loans, unsecured loans and credit cards.
Compare the total amount repayable, interest, all fees, the term and early-repayment charges. A lower monthly payment can mean a longer term and a higher total cost. Securing previously unsecured debt against your home puts the property at risk if you cannot keep up repayments.
However, using a second charge to pay off debt does add more debt to your home.
What to consider before taking out a second mortgage
Before you take out a second charge mortgage, you should consider your suitability for these loans and their pros and cons. You might want to get financial advice to clarify your position.
Pros and cons of second charge mortgages
Second charge mortgages have important pros and cons you need to fully understand.
The pros
- Available borrowing depends on property value, existing secured debts, affordability and lender criteria. Secured products may offer larger amounts than some unsecured options, but there is no universal £25,000 ceiling for personal loans.
- Because you are securing the loan with your home equity, you might be able to find more competitive interest rates than alternative credit options. You’ll still need to compare second charges to uncover the better deals.
- The money must be used for a purpose accepted by the lender.
The cons
- A second charge increases debt secured on your home. You remain the owner, but the lender’s security can be enforced if the agreement is not maintained.
- Second charge mortgages might have minimum loan amounts, making them unsuitable for people who need smaller loans.
- The loan is secured on the property. Missed payments can lead to repossession through the applicable legal process; security does not remove affordability checks or give the lender an automatic right to take the home without that process.
- Getting a second charge mortgage might include various fees
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. A lower monthly payment may mean paying more overall, and secured borrowing puts your home at risk if repayments are not maintained.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
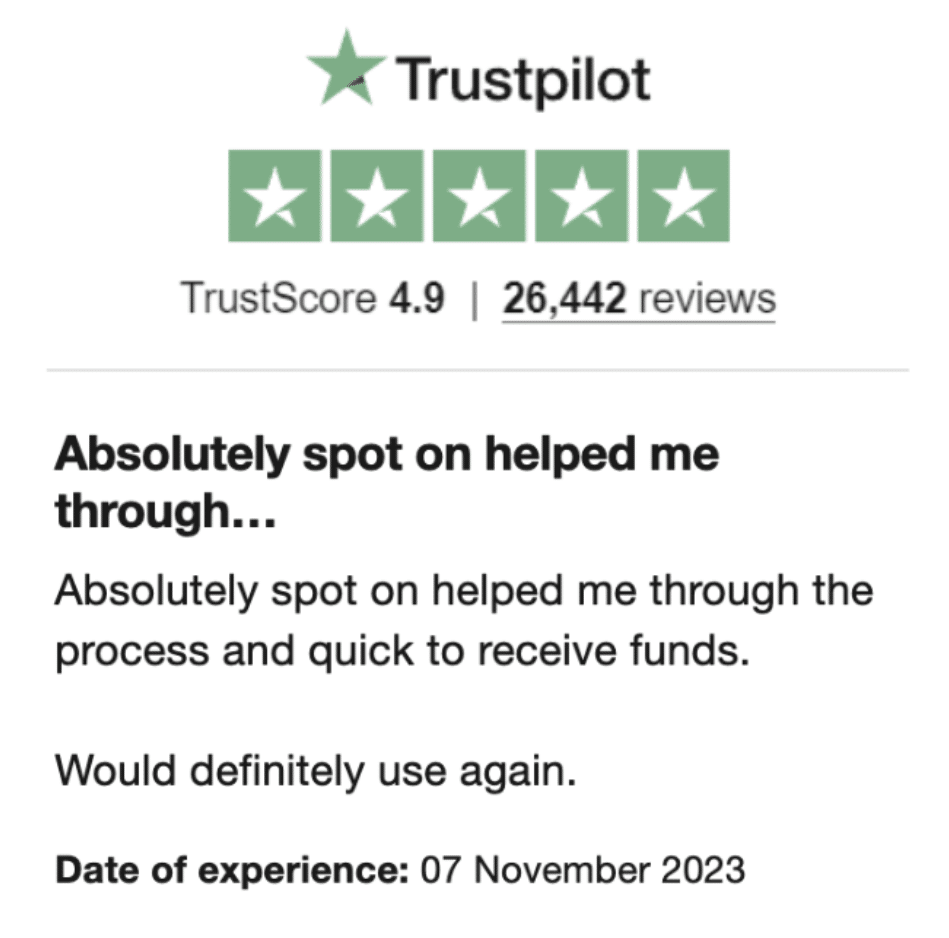
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
Can I take out a second charge mortgage with bad credit?
Getting a second charge mortgage with a bad credit rating is more challenging, but it’s still very much possible.
Security does not remove credit or affordability checks. Poor credit can restrict options and increase costs, and approval is not guaranteed.
You might want to look for bad credit second charge mortgages, which are the same loans marketed to people with unsatisfactory credit.
And if you’ve previously been made bankrupt, you may want to read our Second Mortgage after Bankruptcy guide for information.
Can a mortgage lender refuse a second charge?
Yes, a mortgage lender and any other lender can refuse an application for a second charge mortgage.
A second charge mortgage application might be refused if:
- The loan is deemed unaffordable for you alongside existing debt repayments, including first mortgage payments
- There are complications with the property ownership, such as a deceased person still being named on the deeds.
- Surveyors find major issues with the property during its appraisal.
Credit history remains part of the lender’s assessment and may lead to refusal, even where there is substantial equity.
How many second mortgages can I have?
Further borrowing on the same property may be possible, but later charges normally take a later rank unless priority is agreed. They should not all be described as simultaneous second charges.
But your finances and home equity will determine whether or not you can get approved for multiple second charge mortgages.
Additional charges can involve existing lenders’ consent, legal work and extra affordability checks. Obtaining the first additional loan is not automatically straightforward.
Does a second mortgage hurt your credit?
A hard search and the new account can affect your credit record. Multiple applications in a short period can be a warning sign to lenders.
Paying as agreed can support your credit history, but it does not guarantee a particular score or approval for future borrowing.
Secured loan alternatives to a second mortgage
Alternatives to a second mortgage can include:
- A secured personal loan using other assets as security (not as common)
- Remortgaging and borrowing more
- Taking a further advance on your existing mortgage
- Unsecured borrowing
Should I take out a second charge mortgage or remortgage?
The decision to use a second charge mortgage to release equity or remortgage and release equity can only be an individual decision based on personal circumstances.
Remortgaging may or may not offer a better interest rate on the additional borrowing, but remortgaging can also trigger early repayment charges on the initial mortgage.
One way of avoiding the early repayment charge but borrowing more from your existing mortgage is to ask for a further advance instead.