Gifting equity in property: ownership, tax and borrowing risks


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
Gifting a property share can have significant ownership, tax, benefits and care-funding consequences. It is not a reliable shortcut to qualify for equity release.
Here, we'll answer some key questions, such as:
- What does gifting equity mean?
- Why gifting ownership does not automatically create equity-release eligibility
- What impact could it have on your taxes?
- Can you change your mind after gifting equity?
- What other choices do you have?
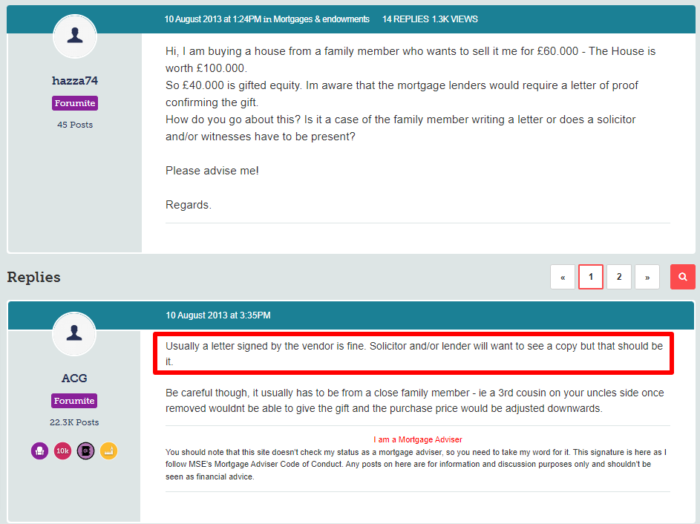
Any transfer of property rights should be assessed on its own legal and financial consequences, with independent advice for the people involved.
We’re here to make things clearer for you and to guide you every step of the way – after all, it’s your home and your future, so you deserve to understand all your options.
Let’s dive in.
How Does It Work?
We first need to look at how equity release works. Equity release leverages some of the value in a property by either a) remortgaging it under a lifetime mortgage, or b) selling part of the equity to a third party in exchange for cash payment.
A lifetime mortgage is repaid under its contract, usually after the last borrower’s death or permanent care move. Home reversion sells property rights and has separate occupancy terms.
Most standard lifetime mortgages start at age 55, but some payment-term lifetime mortgages are available from 50 and require interest payments for an agreed period. Home-reversion minimum ages and all other eligibility rules depend on the provider. Check the youngest applicant’s age and the actual product criteria.
Giving a share to an older person does not bypass the lender’s age, ownership, occupancy or underwriting requirements. If the younger person remains an owner or occupier, their position still needs assessment.
Why a gift is not an eligibility workaround
Do not transfer ownership simply to access another person’s equity-release eligibility. You may lose valuable ownership or occupancy rights without obtaining any loan.
The lender and solicitor must assess the full ownership and occupancy arrangement. A recipient’s age and proof of title alone do not establish eligibility.
A Comparison
I’ve put together this table to help you better understand the differences between a home reversion plan and a lifetime mortgage. If you want to learn more about equity release, make sure to read our detailed guide.
| Category | Home reversion plan | Lifetime mortgage |
|---|---|---|
| Ownership | You sell part or all of the home, usually for less than open-market value, and remain under the plan’s occupancy terms. | You retain ownership and borrow against the home. |
| Property value changes | The provider receives the agreed share of future sale proceeds; only any retained share belongs to your estate. | Sale value and the outstanding loan, interest and charges affect the amount left for your estate. |
| Inheritance | Selling a share reduces what you can leave; any protected share and conditions must be checked. | Rolled-up interest can reduce the remaining equity. Inheritance protection may be available under some plans. |
| Repayment | There is no loan to repay for the sold share; the provider receives its share when the property is sold under the plan. | Usually settled when the last borrower dies or moves permanently into care. Payment options and obligations vary. |
| Money received | A lump sum or income may be available, depending on the plan. | A lump sum or agreed drawdown reserve may be available; access remains subject to the plan terms. |
Our financial expert, Janine Marsh, says: ‘a lifetime mortgage is definitely the most popular of the two options, especially considering the second option isn’t technically a loan (you won’t need to pay interest on it). Both types of equity release should be considered carefully as there is risk involved.’
Consider the costs and risks of equity release
Equity release is a long-term decision. A lifetime mortgage is secured against your home. Adding interest can substantially increase the debt and reduce your inheritance.
Consider fees, means-tested benefits, early repayment charges and future care needs. Alternatives include downsizing, other assets or a retirement interest-only mortgage where affordable.
Start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
Advertisement. MoneyNerd introduces enquiries to Age Partnership, which advises on lifetime mortgages, and may receive a referral fee.
Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply. Interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Will Doing It Impact the Tax Position of the Person Gifted?
Tax consequences may arise for both the giver and recipient. Relevant questions include:
- Whether the property is/was your main home or residence.
- Whether an applicable spouse or civil-partner exemption or another specific relief applies; family membership alone is not a general exemption.
- Whether mortgage debt or other consideration is transferred and whether inheritance-tax or capital-gains rules apply.
There is no general tax-free rule for a gift simply because it is a main home given to family below one threshold. Capital Gains Tax, inheritance tax and property transaction taxes have different rules. Taking over mortgage debt can be chargeable consideration for SDLT in England or Northern Ireland; Scotland and Wales have separate taxes.
Continuing to benefit from a gifted home can bring gift-with-reservation rules into play. The 7-year rule alone may not remove it from the giver’s estate. See related guidance.
About Age Partnership
Equity release is a long-term decision. Specialist advice is needed to assess suitability and compare the costs, risks and alternatives.
Advertisement. MoneyNerd introduces enquiries to Age Partnership, which advises on lifetime mortgages, and may receive a referral fee.
Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply. Interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Can It Be Reversed?
A completed gift is not normally reversible merely because the giver changes their mind or the recipient declines to borrow. Legal remedies depend on the facts, such as capacity, undue influence, fraud or mistake; obtain independent legal advice.
- Whether the giver had the required capacity and understood the consequences.
- Whether consent was free from undue influence, fraud or other legally relevant defects.
Trust between relatives is not a substitute for independent legal advice and clear protection of ownership and occupancy rights.
Is Giving and Receiving It Regulated in the UK?
A property gift is subject to land law, tax, lender-consent and other legal requirements. It should not be described simply as an unregulated personal transaction.
Equity-release advice and products have their own regulatory requirements. Do not assume there is an FCA-approved gifting technique for bypassing eligibility. See related guidance.
Are There Any Alternatives?
Compare downsizing, savings or other assets, benefits and grants, a standard mortgage or retirement interest-only mortgage where affordable, and other suitable borrowing. A specialist adviser should assess the alternatives; equity release is not the only option in later life.
- A secured loan may be an option if eligible and affordable; compare repayment obligations, costs and the risk to your home.
- Additional borrowing through a remortgage may provide cash after existing debt and costs are paid, subject to affordability and lender criteria. Rising property value does not guarantee approval or spare cash.
Is It the Right Choice for You?
A gift of equity is not a simple or recommended way around age restrictions. Consider appropriate products and alternatives, and obtain independent legal and tax advice before any ownership transfer.
- Protect your own housing, ownership and financial needs before making a gift.
- Fully research the tax implications of making such a gift.
- Compare suitable funding alternatives with an authorised adviser; do not change ownership solely to fit a lender’s criteria.
References