


Scott & Mears debt letters: administration and checking who to pay


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Scott & Mears Credit Services Limited’s website says it entered administration on 2 September 2025. If you receive a demand in its name, verify the current authorised handler before paying or sharing information.
Administration of a collection company does not automatically cancel a client’s underlying debt. Check the creditor, account and any new collection instructions through independently verified channels.
This guide explains how to check a Scott & Mears demand and consider your options if a valid debt is unaffordable.
In this article, we’ll tell you:
- How to check if the debt is yours.
- If you can ignore Scott and Mears.
- How to stop Scott and Mears from bothering you too much.
- Ways to set up payment plans.
- How to write off your debt if possible.
Check the current company notice, the creditor’s records and any formal documents before deciding how to respond.
Let’s get started!
Why Are They Contacting Me?
Historically, Scott & Mears collected accounts for clients. Following the administration notice, establish who now has authority to handle your particular account.
Ask the creditor or verified current handler to identify the account and explain its authority.
Also, you should understand your legal rights as a debtor. These include:
- Being treated fairly and with respect and not to be harassed or threatened
- You can request proof of the debt they claim you owe
- You can request reasonable communication arrangements and explain vulnerability or inconvenience. There is no general right to stop all legitimate collection correspondence.
- Ask them to provide clear and accurate information about the debt, including the amount owed, the original creditor, and repayment options
- Be ready to negotiate and agree upon an affordable repayment plan with them
Online reviews reflect individual accounts and do not establish a current client list, legal liability or the identity of a caller.
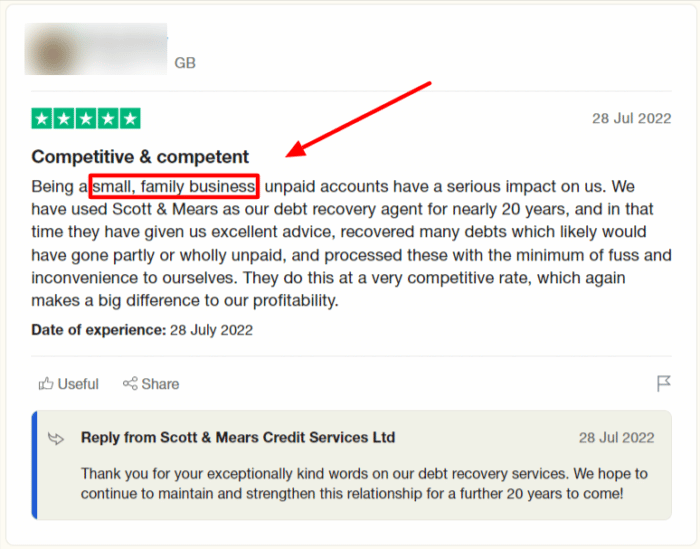
Image courtesy of TrustPilot: https://uk.trustpilot.com/review/scottandmears.co.uk
Historic descriptions of its collection services should be read alongside the administration notice. Use the current notice and administrator’s information to establish who can deal with an account.
What to Do If The Collectors Contact You
You have a range of options available to help you prepare for when this happens.
Use an independently verified current contact route to ask questions; do not rely on an unexpected caller or historic number.
Then, after you know how much you owe them and what for, you can explore some options that can help you move towards a solution:
- Bankruptcy: a formal insolvency process with eligibility, costs, restrictions and potential asset consequences. Some debts are excluded from discharge.
- Debt management plan: an informal repayment arrangement for suitable debts. Interest and charges are not automatically frozen, and it may last a long time.
- Old debts: limitation or prescription depends on debt type, jurisdiction, relevant dates, payments, qualifying acknowledgements and proceedings. Six years does not automatically write off every debt.
- IVA: a formal arrangement requiring an insolvency practitioner and creditor approval. The amount repaid or written off depends on the case; fees, asset conditions, credit impact and failure risk matter.
- Debt relief order: in England and Wales, eligible debts must not exceed £50,000 and other current income, asset and residency conditions apply. It is not based on earning less than £30,000 a year; Northern Ireland has separate rules and DROs are unavailable in Scotland. See related guidance.
Do not ignore genuine legal papers. A creditor may pursue a valid claim even if its former collection agent entered administration.
Keep records and use an appropriate letter template where helpful. Send it to the verified current handler rather than assuming the old agent remains responsible. See related guidance.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Can They Take Me to Court?
A creditor or properly authorised claimant may issue proceedings where it has a claim. Ignoring calls does not prove liability or reliably predict whether court action will happen.
Even a relatively small debt, including a private parking charge, can lead to proceedings. Do not assume an amount is too low to justify a claim.
Can I Ignore Them?
Respond to a verified demand and seek time to obtain advice where needed. Applicable obligations depend on the account and legal stage.
Read the letter and check its deadline promptly. A request for more time does not itself extend an appeal or court deadline.
For regulated consumer-credit debts, relevant dispute and financial-difficulty rules may require a pause or forbearance. Explain your circumstances, but do not assume a blanket hold applies to every case.
Ask for written confirmation of any agreed pause, communication preference or arrangement. This does not guarantee that all contact will cease.
Before using an old telephone number or sending payment, check the administration notice on Scott & Mears’ website and the linked Begbies Traynor information. Verify any replacement instructions with the creditor independently. See related guidance.
How They Attempt to Recover Debt
The company’s historic service descriptions included: See related guidance.
- Account monitoring
- Assessment of means and pre-sue reports
- Process serving
These historic services should not be treated as confirmation that Scott & Mears still handles a particular account. Check the administrator’s information and the creditor’s current instructions.
A collector may request budget information to assess an arrangement. Share only what is reasonably needed through a verified channel, and get advice if you are unsure about a request.
“Account monitoring” does not give an ordinary collector access to your live bank balance. A court information order is a separate procedure; open-banking access would require appropriate authorisation. See related guidance.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Can I Stop the Letters?
You can ask for reasonable changes to how and when you are contacted, but cannot necessarily stop all letters about a valid account.
Explain your preferred channel and any support needs. Legitimate statutory notices and court papers may still have to be sent.
Keep a record of repeated inappropriate contact and use the appropriate complaint route. Do not rely on assumptions about how this company monitors responses.
How to Make a Complaint
Our article on this subject explains the complaints process in more detail.
There are debt charities throughout the UK that can help with what details to gather, the nature of the complaint, and who to complain to.
Remember, it is vital to get the advice of a professional on the best option for you in your own circumstances.
The best free debt advice organisations to contact include:





