Residential park home finance: options and risks


Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
A residential park home usually comes with a right to occupy a pitch, rather than ownership of the land. Financing and legal checks therefore differ from buying an ordinary house.
We know that finding the right finance for a park home can be a bit tricky. There are rules about selling park homes that are different from other houses. And you might be worried about the real cost of a bad loan. But don’t worry, we’re here to help.
In this easy guide, we’re going to tell you about:
- What a park home is.
- Why a lower purchase price does not settle the overall cost
- How you can find the right park home for you.
- The different ways you can pay for a park home.
- How to compare park-home finance costs and risks
Remember, you’re not alone – lots of people need advice on buying a park home. We’re here to give you clear and simple tips.
So, let’s learn about park home finance together.
Is It Possible To Get Finance for a Park Home?
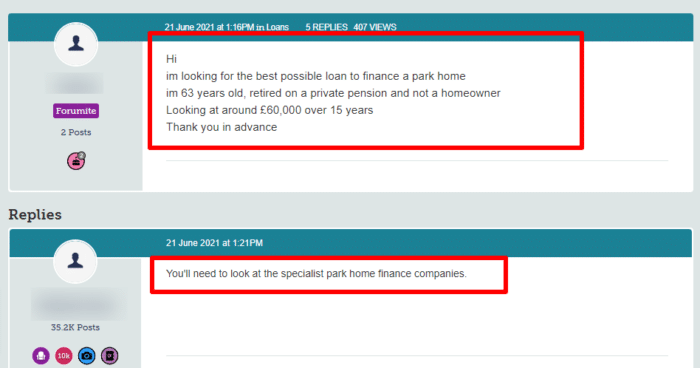
A conventional residential mortgage is generally not available for a park home on a rented pitch. Some specialist providers offer loans, and a personal loan may be an option for a smaller amount, subject to criteria and permitted use. See related guidance.
What Options Are There Available To Finance the Purchase of a Park Home?
Compare available products, the security required and the full repayment cost. A product marketed as park-home finance is not automatically an ordinary mortgage.
- The purchase of a park home can be financed with a personal loan from a bank, building society, or other lender. A personal loan is typically an unsecured loan that can be used for various purposes. Depending on the lender and your circumstances, your interest rate and repayment terms may vary.
- Specialist park-home loans can have their own security and repayment terms. Check the actual agreement and do not assume they offer the same terms or protections as a conventional house mortgage. See related guidance.
- Later-life equity release on another property requires specialist advice. That property normally has to remain your main home; moving permanently or letting it may require repayment or lender approval. Interest, fees and the effect on your estate matter.
- Bridging finance is short-term borrowing that needs a credible repayment plan. It can be expensive, and borrowing secured against another property puts that property at risk. Do not rely on a future sale or refinance being guaranteed.
Explore secured loan options
Enquire about secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
How to compare park-home finance
Choosing the best lender for your park home financing needs requires researching and comparing different lenders and products. Below are some factors to consider before settling on a specific lender.
- Park home finance products have varying interest rates based on the lender and product type. Ensure your chosen product’s interest rate is competitive and you can afford to pay it back.
- Consider the repayment terms offered by different lenders, such as the length of the loan and the type of payments.
- Know what fees and charges are associated with the finance product, including arrangement fees, early repayment fees, and exit fees.
- Check the provider’s current eligibility requirements and affordability assessment. An online calculator or preliminary check is not approval.
Which Type of Finance Is Right for You?
Your income, credit history, and the amount needed to borrow will determine the type of financing you choose to purchase a park home. If you’re deciding which type of finance is right for you, consider these factors below.
- Would you qualify for an unsecured loan?
- Is a secured loan an option? Do you have collateral to put up?
- Do you own another property, and can you remortgage it to get finance?
- Credit cards may be expensive or unsuitable for a large purchase, and the seller may not accept them. Compare permitted uses, fees, rates and repayment affordability before considering this route.
A secured-loan example can illustrate costs but does not establish availability or suitability for a park home. Your home may be repossessed if you do not keep up repayments on a loan secured against it.
| Category | Illustrative example |
|---|---|
| Background | Fictional example: John is a homeowner considering £20,000 for renovations. This is not a real customer story or a lending offer. |
| Application | A lender would assess property value, existing borrowing, income, expenditure and credit history. Approval is not guaranteed. |
| Costs | John would compare personalised APRC, fees, monthly payments, repayment term and total repayable. Rates and terms vary; no rate or monthly cost is assumed here. |
| Potential benefit | A secured loan might provide funding while retaining an existing mortgage, but other funding options could be cheaper or more suitable. |
| Risks | John’s home may be repossessed if required payments are missed. Fees, early-repayment charges and a longer term can increase total cost. |
| Possible outcome | The result depends on affordability, payments, interest rates and property values. Neither a higher credit score nor an increase in property value is guaranteed. |
Enquire about a secured loan through Loans Warehouse
Advertisement. Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare the full cost before applying. MoneyNerd may receive a referral fee. Your home may be repossessed if you do not keep up repayments on a loan secured against it. Fees may apply. Ask Loans Warehouse about any fees before you decide whether to proceed.
Park Home Insurance
As with traditional property, a park home can be a substantial investment, so many people would be inclined to protect their homes by insuring their property and the contents within. It is a good idea to compare quotes to receive the best deal possible on your insurance.
Park home insurance can vary significantly depending on a number of factors. This can include the value of a park home, how old it is, the location, the insurance provider, and how much coverage you need.
Are Park Home Sales Regulated?
Residential park-home rights and sales rules differ across England, Wales, Scotland and Northern Ireland. Check the law and guidance for the location of the home rather than treating one Act as a UK-wide scheme.
Check the written pitch agreement, site rules and the applicable statutory rights, including pitch fees, occupation and dispute procedures. Ask an independent adviser to review the documents.
Consumer rights depend on the transaction, seller and jurisdiction. Do not assume every sale has the same cancellation rights. Obtain advice before signing or paying a deposit.
Check the site’s residential licence, planning and occupancy conditions. A holiday site is not interchangeable with a residential park, and a voluntary code does not replace statutory rights.
About Loans Warehouse
Compare the repayment term, fees and total cost before applying.
Advertisement. Loans Warehouse is a credit broker, not a lender. MoneyNerd introduces enquiries and may receive a referral fee. Approval and terms depend on checks. Compare fees, interest and the total amount repayable; a longer term may increase the overall cost. Fees may apply—ask Loans Warehouse before deciding whether to proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Why Are Park Homes Cheaper Than Traditional Bricks and Mortar Housing?
A lower purchase price does not guarantee lower lifetime costs. Budget for the pitch, utilities, council tax, insurance, maintenance, financing and eventual sale.
- Prefabricated parts and materials are used to construct park homes in factories. In other words, construction is more streamlined and efficient than traditional housing construction, which involves many tradespeople and materials. Consequently, park homes are generally cheaper to build than conventional homes.
- The purchase price normally covers the home and occupation rights, not ownership of the pitch land. Ongoing pitch fees are therefore a material part of the budget.
- Maintenance and energy costs depend on the particular home, condition and specification. Do not assume that every park home is cheaper to maintain or heat than a conventional property.
- Council tax depends on the applicable valuation and banding rules, not a blanket lower rate for movable buildings. Check the actual bill and local arrangements.
Consider depreciation, resale restrictions, sale charges and ongoing pitch fees alongside the purchase price. Get independent advice about the site and the agreements before committing.
References