Equity Release Solicitors Fees – How Much Will It Cost Me?


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
If you're curious about equity release and the cost of legal help, you're in the right place. In this article, we'll explain:
- What equity release is and why people choose it.
- How to understand if you’re eligible for equity release.
- What the main two types of equity release are.
- The role of a solicitor in the equity release process and their fees.
- Important things to consider before deciding on equity release.
Equity release can seem tricky. Many people worry about the fees and if their home is at risk. But don’t worry, we understand these concerns. Our website is here to make things clear and simple for you.
Why do people choose equity release?
Equity release can be an advantageous way to secure a cash lump sum in later life and be used to pay for retirement. Some of the popular reasons people decide to use equity release are to go on frequent holidays, pay for private healthcare services, complete home improvements or to gift the money to family members, as a sort of early inheritance.
The main two types of equity release explained
As stated earlier, there are two equity release products used in the UK. A lifetime mortgage is the most used equity release scheme, but another equity release option is a home reversion plan. Only consider either equity release plan from a lender that is authorised and regulated by the Financial Conduct Authority.
- Lifetime mortgage
A lifetime mortgage is a loan secured on your home; you retain ownership. Interest that is not paid is added to the balance. The loan is usually settled when the last borrower dies or moves permanently into care, subject to the contract. Required or optional repayments vary by product.
Repayment is normally due when the final borrower dies or moves permanently into care, subject to the product terms.
- Home reversion plan
A home reversion plan is a sale of part or all of your home, usually below open-market value, in return for money and the right to remain under the plan’s occupancy terms. It is not a loan. The provider receives its agreed share when the home is sold. See related guidance.
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Do you need to receive financial advice first?
Equity release is a huge decision that can be unaffordable to get out of once you have committed. For this reason, it is imperative that you receive equity release advice before making a decision. This advice should explain the full projected costs, the effects of equity release on other things such as means-tested benefits etc., and explore alternative solutions first.
In some cases, it’s also recommended to look into getting an equity release with a lasting power of attorney to protect yourself and your assets in the event that you’re in no condition to decide over the property at some point.
Many lenders offer homeowners the chance to use their own financial advisers, who should operate with professionalism and not push you to choose their lender’s lifetime mortgages or other plans. Alternatively, you can use an independent equity release adviser not connected to a lender.
Advice firms may charge a fixed fee, a percentage or no separate client fee, and may receive provider commission. Obtain a written quote and disclosure of when charges become payable.
Do you need a solicitor for equity release?
On top of financial advice, you also need to receive legal advice to act on your behalf throughout the process of applying for equity release. This will protect you and give you additional peace of mind.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
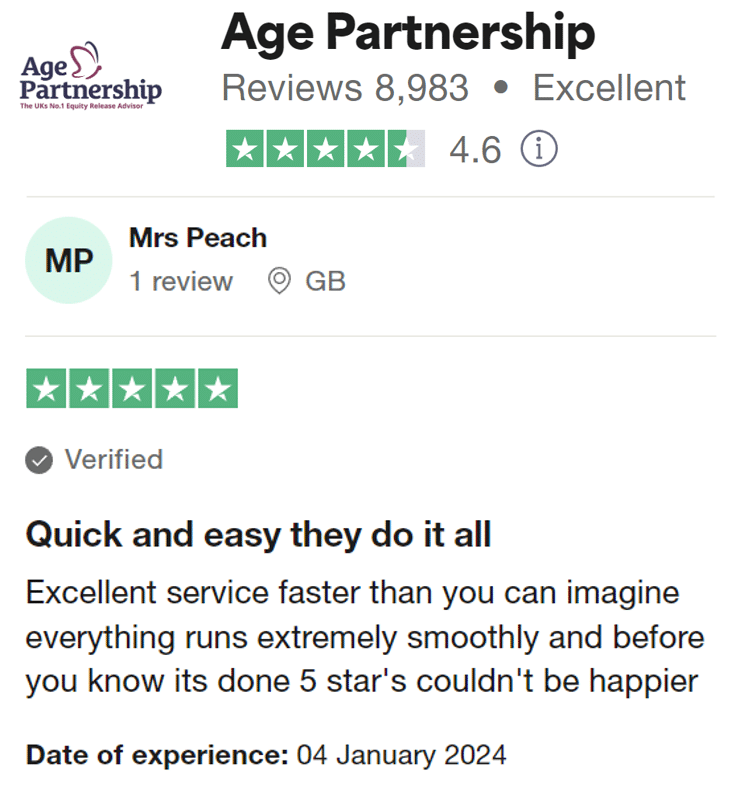
Reviews shown are for Age Partnership. Search powered by Age Partnership.
Do you have to have a solicitor for equity release?
The Equity Release Council makes it mandatory that homeowners must receive legal advice before pursuing an application for lifetime mortgages or other equity release plans.
This is mandatory to carry out legal tasks during the process, but also to help prevent homeowners from falling victim to any rogue financial advisers who wrongfully promote equity release.
You can read stories about mis-sold equity release here.
Can I use any solicitor for equity release?
Choose a suitably qualified legal professional acceptable under the provider’s requirements, with relevant equity-release experience. Council guidance does not impose a general four-lawyer minimum for every law firm; the customer’s solicitor need not be a Council member.
You should also prioritise lawyers who have experience with the equity release process or even specialise in this area. Many specialising financial advisers frequently will be able to point you in the direction of competent equity release solicitors.
» TAKE ACTION NOW: Find out how much equity you could release
How much do solicitors charge for equity release?
Solicitors set their own fees. Ask for a written quote including VAT, searches, registration, other disbursements and any extra work or abortive costs.
How much does it cost to release equity?
There is no universal £2,000 minimum. Total setup costs depend on the adviser, solicitor, lender and work required; compare written quotes and any fees added to the borrowing.
There may be additional costs you have to pay in regards to the application, often relating to admin costs, an application fee and property valuation fees.
How to choose equity release advice
Homeowners should only choose financial advisers that specialise in equity release. The adviser they use must be authorised and regulated by the Financial Conduct Authority, and preferably they should be members of the Equity Release Council.
Will a lifetime mortgage stop my state pension?
A common concern is that releasing a lump sum of your home equity will stop you from claiming a state pension. The basic state pension is not a means-tested benefit – i.e. it does not take into account your wealth to determine eligibility – and it will therefore not be taken away from you or reduced just because you receive a large loan.
However, there are a handful of means-tested benefits which could be taken away or reduced when your wealth increases, such as Universal Credit, Council Tax Reductions and Pension Credit payments, which are used to top-up the State Pension for low-income individuals.
Is equity release a good idea?
The only way to know for certain if equity release is a good idea for you is to source competent and professional equity release advice and legal counsel. You should start by doing your own research, which is why we have created lots of easy-to-read equity release content.