


Mis-Sold Equity Release Schemes – What you Should Know


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
Are you keen to understand more about equity release schemes? In this easy-to-follow guide, we'll explain:
- The basics of equity release.
- The process to get a fair quote.
- The good and not-so-good parts of releasing equity from your home.
- How equity release could touch your inheritance tax.
- If you might lose your house with equity release.
We understand that equity release can seem tricky. Many people worry about the danger of being mis-sold a scheme. We’re here to help clear up your doubts and guide you through the process. Our mission is to make sure you know all the important bits about equity release, so you can make a choice that’s right for you.
Let’s start this journey together, step by step.
Does it happen?
Signs of miss-selling
Some of the common signs of being mis-sold an equity release mortgage or scheme are:
- Interest charges not being fully explained
- Early repayment costs and other loan fees not explained properly
- Inheritance tax implications not discussed
- Alternative options not explored or pointed out
- The wrong plan recommended
Another big one is being told to remove a homeowner from the property ownership to meet the age requirements. This is dangerous for the younger homeowner if their partner passes away first.
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
An example
An example of equity release being mis-sold would be a client speaking with a financial adviser about the possibility of releasing equity to help their son buy a home. Despite having £130,000 in savings, the adviser suggests that the client releases £60,000 instead, and without truly explaining the total cost this would bear over time.
The adviser should assess savings and other reasonable alternatives and explain the costs and risks. Whether using savings is suitable depends on the client’s full circumstances.
What you can do
If unsuitable advice or another failing caused loss, you may be entitled to redress. Eligibility and the amount depend on the evidence, applicable rules and complaint outcome; compensation is not automatic. See related guidance.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
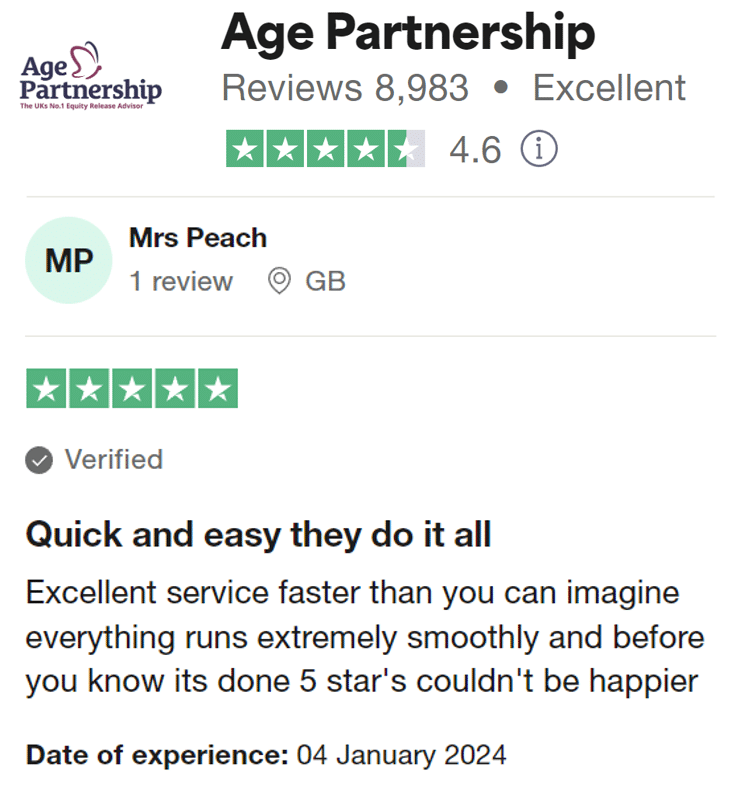
Reviews shown are for Age Partnership. Search powered by Age Partnership.
How do I complain about it?
Complain first to the firm responsible, which may be the adviser, broker or lender. It normally has 8 weeks to issue a final response. If eligible, you can refer the matter to the Financial Ombudsman Service; the usual referral deadline is 6 months from the final response, and other time limits can apply. See related guidance.
The Financial Ombudsman Service is a body set up to deal with disputes like these and they will look at both sides to make a decision on whether compensation should be awarded or not.
» TAKE ACTION NOW: Find out how much equity you could release
What if my lender went bust?
If the firm responsible has failed, check whether the FSCS covers the particular regulated activity and claim. Lender failure alone does not automatically create a compensation claim or cancel the mortgage. See related guidance.
Can you sell property wherein equity was taken out?
If you have taken out an equity release mortgage or home reversion plan, it’s still possible to sell your home and move or downsize. The Equity Release Council insists that any homeowner who wants to move to a suitable alternative property should be allowed to do so.
A new property must meet the provider’s current security criteria. A cheaper home is not automatically excluded, but a partial repayment, charges or restrictions may apply.
It gets a little more complex if you want to downsize to a less valuable home. You may need to pay off some of your equity release scheme in the process, which can trigger early repayment fees. However, including a downsizing clause in your original agreement can help you avoid early repayment charges when downsizing.





