


When Does an Old Debt Become Statute-Barred?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
An unpaid debt is not automatically written off when it reaches a particular age. Some court claims become time-barred, while other recovery powers or an existing judgment may remain. Check the debt type and jurisdiction before deciding what to do.
In this article, we’ll explain:
- The distinction between a court time limit and a debt write-off.
- How to check dates, payments and earlier court proceedings.
- The rules on collection and complaints.
- Why credit-file removal is a separate issue.
A study by Citizens Advice found evidence of poor practices by debt collectors in the UK, including the collection of very old debt.1 So, I understand your worries.
But you’re not alone. We’ll show you what you can do and how to make the best choices.
What time limit applies to an unpaid debt?
For many simple-contract debts in England and Wales, the limitation period is six years from the relevant cause of action: when the creditor became entitled to sue. The date depends on the agreement and legal requirements, including any required default notice. It is not automatically the date on the credit report.
For a mortgage shortfall in England and Wales, different periods can apply to capital and interest, commonly twelve and six years respectively. Mortgage and secured-debt cases need specialist advice.
For an ordinary statute-barred debt in England and Wales, the underlying debt generally still exists, but limitation provides a defence to a late court claim. You must respond to court papers and raise the defence; do not assume the court will identify it for you.
For collection covered by FCA CONC 7.15, a firm must not keep demanding payment once you state that you will not pay because the debt is statute-barred. A separate rule bars recovery attempts where the lender or owner had not contacted you during the limitation period. This is not a blanket ban on every communication about any old debt.
Complain to the lender or collector first. If the complaint is eligible and remains unresolved, you can refer it to the Financial Ombudsman Service within the applicable time limit. The FCA can receive reports about misconduct but does not decide individual compensation disputes.
If FCA consumer-credit rules do not apply, check the law and complaint route relevant to that creditor. Harassment and misleading statements are not automatically permitted just because a firm falls outside those rules.
This guidance focuses on England and Wales. Scotland has different prescription rules: many ordinary debts can be extinguished after five years if the conditions are met. Northern Ireland has its own limitation legislation. Obtain advice for the correct jurisdiction and debt type.
» TAKE ACTION NOW: Fill out the short debt form
A CCJ changes the position: the original limitation defence cannot simply be used to ignore the judgment. A judgment does not automatically expire after six years, although some enforcement methods then require the court’s permission and other restrictions can apply.
Some public debts have recovery powers that do not require an ordinary civil claim. For example, qualifying benefit overpayments may still be deducted from benefits or wages even where a civil claim would be time-barred.
HMRC tax debts and transferred tax-credit overpayments have their own rules. Do not treat all government debts as ordinary six-year consumer-credit claims.
Any deduction must use a lawful process and comply with the safeguards that apply to it.
If a deduction is wrong or unaffordable, ask for the decision and a review and seek debt or welfare-rights advice.
Council tax has different rules. The time for seeking a liability order is not the same as the time for enforcing one that already exists. A balance does not disappear just because the last payment was six years ago.
This is why you should always treat priority debts such as council tax debt, income tax debt, etc. very seriously.
They have very dire consequences if you ignore them.
Will Statute-Barred Debt Affect My Credit Rating?
The effect on borrowing depends on what is still accurately recorded and the lender’s assessment. Statute-barred status is not itself a credit-score category.
Missed payments and defaults can affect a credit assessment. A reduced-payment agreement can also be recorded, depending on the account and reporting rules.
Credit reporting has separate time limits. A defaulted account is normally removed six years after the recorded default date; an account closed without a default normally remains for six years after closure. Becoming statute-barred does not start a new six-year reporting period.
The absence of an old account from your credit report does not prove that the debt is statute-barred or that no court judgment exists.
Lenders use their own eligibility and affordability checks. No displayed credit score guarantees approval.
An accurate adverse history can affect the terms offered, but the result depends on the lender and your circumstances.
Avoid taking on new borrowing solely to change a credit score if it could worsen affordability. Check your reports and dispute inaccurate information first.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Once a Debt is Statute-Barred, Does it get Removed from My Credit File?
The credit-file default date is different from the statutory default notice sometimes required before legal action. Check the recorded date rather than assuming the two are identical.
Limitation depends on the cause of action, the appropriate period, later payments or valid acknowledgment, and any earlier proceedings.
A payment or a qualifying written, signed acknowledgment before the limitation period expires can restart it. A creditor’s reminder does not itself restart the period. Once a claim is already statute-barred under the Limitation Act, a later acknowledgment or payment does not revive it.
Should I just Ignore Payments for Six Years until the Debt is Written Off?
No.
Many people consider this limitation period a solution to their debt problem but the truth is that it hardly ever works for anyone. It should not be considered a debt solution.
A creditor can take action before limitation expires, including issuing a claim where entitled to do so. Failing to deal with correspondence can lead to costs, a judgment and enforcement.
A regulated-credit default notice normally gives at least fourteen days after service to remedy the stated breach. Check the notice, liability and affordability; do not make a payment solely because an article tells you to, especially where an old debt may be disputed or statute-barred.
If you cannot afford to make the payments that your creditor has stated, you should still contact them and tell them.
Many creditors will be open to negotiating a different repayment plan that you will be able to afford.
If you do get a different repayment plan, make sure you get it in writing.
This will make it easier for you to keep an accurate record of your debt repayment.
If you receive a claim, follow its response deadline even while requesting information or complaining. A complaint letter does not replace a court defence.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How Do I Talk To My Creditors?
Regular communication with your creditors is important, especially if you are having financial troubles.
You may need to talk to your creditors to create a repayment plan that works for you. But speaking to creditors can be scary when you don’t know how!
From my experience, it is best to start with your priority creditors.
These are creditors who cover essential areas of your life, like your utility company, your mortgage provider, or your landlord.
You will need to be able to demonstrate why you need them to reduce your monthly payments. Usually, creditors will ask to see a budget for your household that includes your income and your living costs.
Keep in mind that most creditors will only agree to a reduced payment scheme for a set period of time. They will then assess your financial situation to see if it has improved and if you can start to pay them more.
Don’t hesitate to contact someone who can help! There are several organisations that offer free debt advice in the UK.
But sometimes you will need to tell your creditors that they are wrong and they can’t be chasing you for old debts!
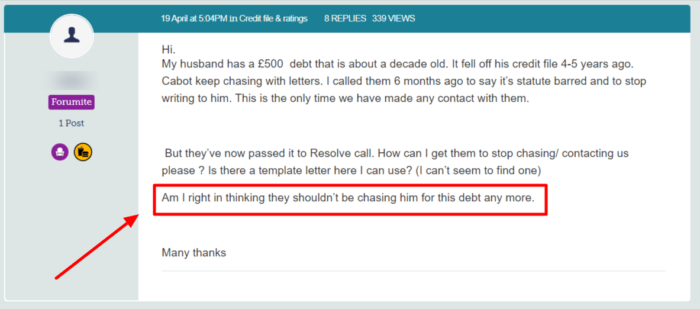
A forum account alone cannot establish whether a debt is statute-barred. Check the evidence and use the creditor’s complaint process and, where eligible, the Financial Ombudsman Service.
I Made a Payment Towards My Debt after Six Years. Have I Made it Enforceable Again?
First establish whether the applicable limitation period had actually expired before the payment.
Under the Limitation Act, a payment after a simple-contract claim has already become statute-barred does not revive that claim.
By contrast, a payment made before the period expires can restart it. Six years since the loan was taken out is not enough to settle which situation applies.
Mortgage shortfalls have different rules for capital and interest. A payment during a running limitation period may affect it, but the calculation needs advice based on the actual debt and dates.
Do not assume that a six-year gap establishes the position for every part of a mortgage shortfall.
The first starting point is the relevant cause of action. Later payments or qualifying acknowledgments may produce a new starting point before the claim becomes barred.
A verbal discussion is not the same as a written, signed acknowledgment under the Act, although the content and circumstances of any communication still matter.
Ask an adviser to check the chronology if you have already paid or written to the collector. Do not assume either that you revived a barred claim or that the debt was definitely barred in the first place.
Where Can I Get Advice For My Debt?
If you are struggling with your debt, I always recommend talking to a debt charity.
These organisations can offer free and individual financial advice to help you get back in control of your finances. You may even benefit from a debt solution which will be explained to you in more detail.
References





