How to Apply for a Debt Relief Order (DRO) Through an Adviser


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Struggling with debt and looking for a way out? You’re not alone. Each month, over 170,000 people visit our website to learn about debt solutions, including how to apply for a DRO online.
In this helpful guide, we’ll cover:
- What a DRO is and how it can help relieve your debt
- Steps to apply for a DRO through an approved debt adviser
- The cost of a DRO and the proof you need to provide
- The consequences of getting a DRO
- The reasons why a DRO might be rejected
This guide covers DRO applications in England and Wales. You must apply through an approved debt adviser. Northern Ireland has a separate DRO process, and DROs are not available in Scotland.
How Can I Apply for a Debt Relief Order?
As this online message shows, many people are struggling with their finances and need advice about how to get them back on track.
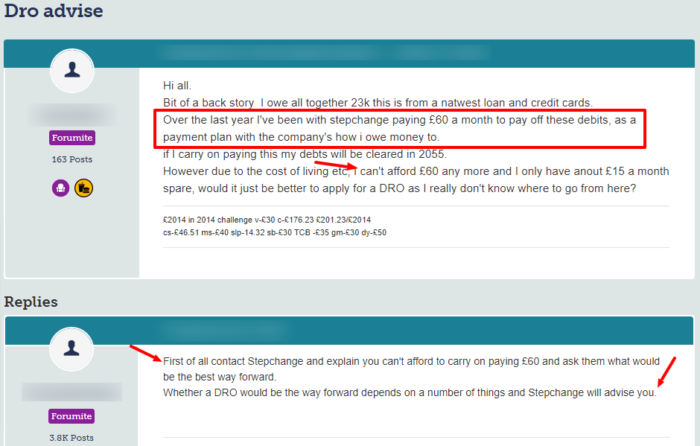
Source: Moneysavingexpert
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Can I Apply for a DRO Online Myself?
Moreover, they can assist you with the DRO online application process to ensure it goes through without any problems.
» TAKE ACTION NOW: Fill out the short debt form
How to apply online
Here’s a quick summary of how to apply for DRO online:
- Reach out to a debt advisor such as StepChange, Citizens Advice or National Debtline
- Work out your full income from your employment and or benefits
- Gather all the up-to-date balances on all the accounts you owe money to
- Work out your monthly expenses using a monthly budgeting tool
- Collect information about your employment and pensions
- Discuss the DRO and any other options regarding your debt with your debt advisor
- Complete the DRO application by sharing all your evidence and documents with your debt advisor
- There is no DRO application fee in England and Wales
- Your debt advisor will complete your paperwork and send off your application to the Insolvency Service
- Wait for the decision. Your adviser can explain current processing times and any further information required
Further information about debt relief orders can be found on the link below:
Glossary of terms
Insolvency – an individual or company that can no longer pay debts when they are due
Creditors – people or businesses you owe money to
Approved intermediary – a debt adviser authorised to submit a DRO application
Why Do I Need a Debt Advisor for a DRO?
There are many benefits of a debt advisor for DRO applications. One of which is they have the necessary experience and knowledge of what’s required.
The debt advisor will ask you questions that will help your DRO online application.
The information you provide will determine whether you’re eligible for the debt relief order. You’ll also be able to learn about other debt solutions that might be better for you and your situation.
Finally, if agreed that a DRO is the best course of action, the debt advisor will complete the necessary paperwork on your behalf.
It isn’t possible to apply for a DRO online without completing this step.
What Proof Do I Need for a Debt Relief Order?
I’ve listed the required documents for DRO online application here.
- Last 2 months payslips
- benefits entitlement letter, or
- bank statements
These documents are to prove your income. You’ll also need to prepare the documents that provide accurate and up to date information on your creditors, such as:
- Energy suppliers including gas, water, electricity
- Council tax and benefit overpayments
- Loans
- Rent arrears
Gather all the latest statements from everyone you owe money to and any supporting documents.
The amount of money you own must include the full amount of the debt and not just any early settlement offers you may have open to you.
You’ll need to provide the debt advisor with details of your income and outgoing expenses. I have a free household budget sheet that will help you prepare for this.
Be sure to be accurate when working out your finances and when sharing the details with your advisor.
Sharing false information can result in a court summons.
Other Information Required to Apply
I’ve added a DRO application information checklist below:
- Full name and place of birth
- National Insurance Number
- Employer details if applicable
- Pension information including the name of the employer and the pension or your payroll number for each employer you have a pension with
- Details regarding formal insolvency solutions you’ve previously been subject to, such as an IVA or bankruptcy.
- Make, model, registration number and condition of any motor vehicle you own
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How Much Does It Cost?
There is no application fee for a DRO in England and Wales. The £90 fee was abolished in April 2024. See the Insolvency Service guide to applying for a DRO.
An approved debt adviser will assess your circumstances and submit a suitable application free of charge.
You do not need to arrange a cash payment or seek a grant for an England and Wales DRO application fee.
Speak to an approved debt adviser to check whether a DRO is suitable and whether you meet all the conditions.
Consequences of a DRO
Once you are accepted, the DRO typically stays in place for 12 months. Once approved, you won’t have to make payments to settle the debts (and interest) which are listed during that period.
At the end of the DRO, the qualifying debts listed in it are normally written off. Excluded debts, new debts and debts arising from fraud can remain payable. Report changes in your income or assets during the DRO, as it can be revoked if you no longer qualify.
A DRO normally remains on your credit file for six years from approval. You must keep paying ongoing commitments, such as rent, energy bills and council tax.
Why Did My Debt Relief Order Get Rejected?
I’ve listed some DRO rejection reasons here:
- You may not have shared accurate information
- you might not be eligible for a debt
relief order
You must prove your eligibility for a DRO. A debt relief order is only an option for those who have £75 or less spare out of their income each month, after household expenses.
In England and Wales, qualifying debts must total no more than £50,000. The general asset limit is £2,000, with exclusions for certain essential belongings. One domestic vehicle worth less than £4,000 can normally be disregarded; adapted disability vehicles have separate rules. Your adviser must also check the residence, previous insolvency and other eligibility conditions.
A DRO is not an option for anyone who:
- Owes more than £50,000 in qualifying debts
- Has over £75 spare each month after household expenses
- Owns a home
- Has assets above the £2,000 limit after the permitted exclusions
Some debts are excluded from a DRO and remain payable, including:
- Student loans
- Court-ordered compensation for personal injury or death
- Fines for criminal offences
- Child maintenance
- DWP social fund loans
Debts arising from fraud must be disclosed and can count towards the qualifying debt limit, but they are not written off when the DRO ends. Secured debts need separate advice. Tell your adviser about every debt and any rent arrears, because a DRO does not necessarily prevent eviction.