Can I Borrow Money Against My House to Buy Another Property?


Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Are you wondering if you can borrow money against your house to buy another property? You've come to the right place.
We know you might be worried about the risks of a secured loan; you might even be in debt and unsure about your next step. We understand these concerns, and we’re here to guide you.
Here’s what we’ll explore in this article:
- The reasons for borrowing money against your house to buy another property.
- The true cost of a secured loan.
- Different options for borrowing money against your house.
- How to calculate the equity of your property.
- The effects on your pension and how to avoid negative equity.
Remember, you’re not alone in this journey. Many others are in the same situation, and we’re here to guide you.
Let’s dive in and learn about secured loans together.
What are My Options?
Depending on eligibility and how both properties will be used, options may include a remortgage, further advance, second-charge mortgage or a suitable later-life product. All borrowing and any borrowed deposit must be disclosed to the relevant lenders.
- You can remortgage your existing property
- You can opt for equity release on your existing property.
Getting a Remortgage
You may be thinking of taking out a second mortgage, but rather than doing this, you could remortgage to buy a second home.
You can opt for a remortgage if you own your current home outright or have built up some equity.
It’s important to consider the tax implications of borrowing against your home to purchase another property. There will be different property taxes and charges depending on which country the new property is in, so make sure you do your research.
In England and Northern Ireland, additional-dwelling SDLT rates are generally 5 percentage points above standard residential rates, subject to the detailed conditions, exceptions and transitional rules. Scotland and Wales use different property taxes; ask the conveyancer to calculate your liability. See related guidance.
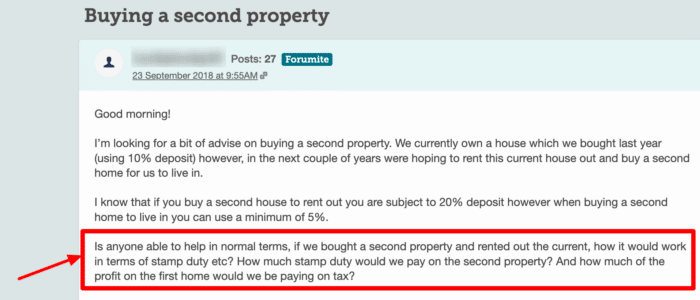
Here, you can see this forum user on MoneySavingExpert is looking for advice about buying a second property and how much stamp duty land tax they will have to pay, which is important to consider.
How do I calculate the equity of my property?
Don’t be worried about calculating the equity of your property, as it’s quite simple:
- If you own your current property outright, then the equity of it is the full value of your property.
- Subtract all outstanding debts secured on the property from its current market value to estimate equity.
Availability depends on the property, purpose, affordability and lender criteria. A broker can help assess options but cannot guarantee approval.
When opting for a remortgage to buy another home, it’s highly important that you look at the secured loan offer thoroughly and go through all the information the lender has offered to you.
Enquire about a secured loan through Loans Warehouse, a credit broker, not a lender. Approval and terms depend on checks. Compare the full cost before applying. MoneyNerd may receive a referral fee. Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Merely looking at the headline rate is not enough, and you should definitely take other costs and fees into account, such as arrangement fees, valuation costs, legal fees, as well as any other costs which may be incurred throughout the process.
If there is still an existing mortgage in place on your current property and you’re taking out a remortgage to buy another one, then there may be early repayment/redemption fees, which you need to keep in mind.
In many cases, these fees could increase your remortgage costs to become pricey, and it might be suitable for you to get to the end of your first mortgage before you can get a loan for additional money.
Retirement Interest-Only Mortgages
A retirement interest-only (RIO) mortgage normally requires affordable monthly interest payments, with the capital due at the contractual trigger, often the last borrower’s death or permanent move into care. A sale may repay it, but a shortfall is not automatically written off. It is different from a roll-up lifetime mortgage. See related guidance.
It’s important to get mortgage advice from a mortgage broker before you take out a remortgage to buy another property. It’s a very big decision and could go horribly for your finances if you don’t do your research properly.
Seeking mortgage advice from a mortgage broker when considering a remortgage to buy another property can come in handy because they could turn you onto mortgage lenders with lower rates.
They could also inform you about techniques and practices to manage your debt more efficiently and reliably.
Buying Through Equity Release
Most standard lifetime mortgages start at 55; some payment-term products start at 50 and require interest payments for a period. Home-reversion ages and other criteria vary. Seek specialist advice. See related guidance.
A lifetime mortgage is a loan secured on your home, normally repayable after the last borrower dies or moves permanently into care. Unpaid interest compounds; some plans allow optional payments and some require payments for a period. Eligibility and borrowing limits are product-specific.
Borrowing limits depend on age, property and product criteria. An existing mortgage normally needs to be cleared at completion, often from the released funds, so it reduces the cash available to you.
Credit history can affect eligibility, but having other debts does not automatically rule out every product. Disclose all commitments and ask for a suitability assessment.
Will my pension be affected?
The State Pension is not means-tested, but retained cash from equity release can affect Pension Credit and other means-tested support. Required payments also vary by product; obtain a benefits check and budget assessment.
Interest that is not paid is added to the balance and can compound. The amount charged can grow even when the interest rate itself is fixed.
A lifetime mortgage is normally due after the last borrower dies or moves permanently into care. Confirm the repayment deadline, alternatives to a sale and any applicable no-negative-equity guarantee.
To be eligible for equity release, your home will have to meet a minimum value, and it has to be your main residence. It also must be in good condition.
Increased Flexibility
The great thing about modern mortgages that are offered to older citizens, which last a lifetime, is that they are far more flexible when it comes to equity release when compared with mortgages offered in the past.
You can opt to keep making regular interest payments towards the mortgage if you want to keep your interest bill down.
You can also choose whether you’d like to have access to the funds in stages or if you would like a large lump sum all at once.
Modern mortgage products also exist, which enable you to protect an inheritance for your children or other beneficiaries.
A Guarantee for No Negative Equity
When you’re looking for equity-release providers for your current home, it’s a good idea to look for ones that are authorised and regulated by the Financial Conduct Authority and also belong to the Equity Release Council (ERC).
Lenders that are regulated by the FCA have to follow guidelines that ensure that you, the debtor, are protected throughout the process and are treated fairly.
Check that the particular equity-release plan meets the Equity Release Council’s product standards and read the guarantee’s conditions; a firm’s membership does not make every mortgage it offers an equity-release plan. See related guidance.
A qualifying no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met. It does not stop the balance exceeding the property value or make the plan risk-free.
Seek professional advice
Obtain regulated specialist equity-release advice and independent legal advice before proceeding.
This is because equity release can sometimes lead to reduced inheritance for your beneficiaries.
You can seek debt advice and information from different independent charities such as StepChange.
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
What are Some Reasons for Borrowing?
There can be several reasons and circumstances in which you could be looking to borrow money against your current property to buy another one.
Some reasons are:
- You want your current home to be an investment property on a buy-to-let basis.
- You may be wanting to raise money in order to purchase a holiday-let property. This would be different from a buy-to-let property but would still be an investment as you would gain revenue from people using it as a holiday rental property.
- You may be wanting a 2nd home in a fancy location, such as by the sea. In order to fund this home, you may be opting for a remortgage on an existing mortgage on your current property.
- You could remortgage your existing property for a Let-to-Buy purpose. For this, you would rent out your current home to purchase another property for yourself where you would live.
- You may want to remortgage your current residential property so you can purchase a friend or family member a home for them to live in.
From my experience, there are risks to using your home as collateral for a second property, for instance, if property values decrease or if there’s a market downturn.
Buy-To-Let Mortgages
If a new property will be rented out and needs a mortgage, the finance must permit that use. A residential mortgage should not be used on an undisclosed letting basis. See related guidance.
In order to be approved for a buy-to-let mortgage, you’re going to have to show the likely rental income of the investment property you intend to buy.
You must also be prepared to prove that you will be able to afford the mortgage repayments both currently as well as in the future in case interest rates increase.
Capital Repayment or Interest-Only Mortgage?
You have an option of choosing between capital repayment or an interest-only mortgage when you’re considering a buy-to-let mortgage.
Interest-only mortgages are typically more common when it comes to buy-to-let mortgages.
Buy-to-let deposit, rental-cover and affordability requirements vary by lender and property. A 25% deposit is not a universal rule.
Another thing to keep in mind is that the mortgage rates and miscellaneous fees for buy-to-let mortgages are typically higher.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. Securing borrowing against your home puts it at risk if you cannot keep up repayments.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
Can I Get Property in Another Country?
It’s definitely possible to either get a remortgage or to release equity from your current home in order to get a property overseas. You could use this property as a holiday home or something similar.
However, if you’re considering this, it’s very important that you do your research regarding taxes as well as regulations in whatever country you’re choosing to purchase a second property in.
This will help you be prepared for any additional or hidden charges and fees that may come your way.
Should I Borrow?
It may seem unwise to get a remortgage or to release equity from your current property to purchase a second one.
However, it’s a common technique that landlords use all the time.
The important thing is that you must do your research thoroughly and seek expert advice before opting for any one lender.
Also, consider the broader economic environment, such as current interest rates and the state of the housing market, when deciding to borrow money for a second property.
Be sure to scour the market thoroughly to find a lender with the best rates as well as the most flexible policies when it comes to your loan.