


Equity release companies: how to compare providers


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
This guide explains how to compare equity-release providers and the terms to check. It is not a current ranking or a live product comparison.
- How does equity release work?
- What is the best type of equity release?
- How can you spot a good equity release company?
- What are the benefits and risks of equity release?
We know that the world of equity release can feel a bit confusing. It's a big decision to make, but don't worry; we're here to help.
The right choice depends on your circumstances. Use this guide to prepare questions for a qualified adviser.
Let’s get started.
What is it used for?
Most standard lifetime mortgages start at age 55, but some payment-term lifetime mortgages are available from 50 and require interest payments for an agreed period. Home-reversion minimum ages and all other eligibility rules depend on the provider. Check the youngest applicant’s age and the actual product criteria. Funds may be available as a lump sum or through an agreed drawdown facility, subject to terms.
You are allowed to give some or all of your equity release money away to friends and family, which may go towards helping them get on the property ladder themselves. You do however need to be aware of any potential inheritance tax implications when gifting money.
This should be discussed with your financial adviser, but any financial gifts given within the seven years before you die can be subject to inheritance tax.
What is the best type?
It is not possible to say which type of equity release is the better option, as it will be determined by personal circumstances. This is why it is important to get independent financial advice before making a decision.
Although it is not possible to say what is the best type of equity release for everyone, lifetime mortgages are notably more popular than home reversion plans. This may be due to a number of factors, not least that home reversion plans are instantly expensive compared to how a lifetime mortgage debt builds up over time.
Moreover, many lifetime mortgage providers allow the homeowner to make voluntary interest repayments to stop the debt from growing too big.
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Which is the best company?
Just how there is no way of saying what the best equity release plan is for everybody, there is also no way of saying what the best equity release company is for everyone.
What the best equity release plan is for you will be based on individual circumstances and based on the time that you apply. This is why you should complete timely research when you are ready to apply. If you are unsure or apprehensive about how to research and apply to equity release companies, you may want to use credit brokerage services that do it for you. There might be a fee for these services.
You should only consider an equity release company that is a legal lender.
It should also be mentioned that in the event that the equity release company you’re currently dealing with goes bust, your debt will be taken over by another company, and your plan’s conditions will remain the same.
Where do you get it?
Providers offer different products. A lifetime mortgage is a secured loan, while home reversion is a property sale; do not assume a named company offers both.
» TAKE ACTION NOW: Fill out the short debt form
What are lifetime mortgage interest rates?
Rates change and depend on the product and your circumstances. Obtain a current personalised illustration and compare the APRC, fees, repayment options and total projected cost; this article does not quote a live market-leading rate. See related guidance.
How to spot legitimate companies
Legal lenders and equity release companies must be authorised and regulated by the Financial Conduct Authority. If they are, they usually state this on their website at the bottom of the page and this information is verifiable online.
Check the firm’s identity, permissions and contact details directly on the FCA Register. Council membership or a website claim is not a substitute for this check.
The Equity Release Council is a voluntary standards body with several membership categories, including providers, advisers and solicitors. Check the relevant firm’s permissions and professional register as well as any membership.
There are additional reasons to choose a member of the Equity Release Council. All members must follow the rules and guidelines set down by the council, which have been written in the interest of homeowners using lifetime mortgages or home reversion schemes. You can get extra peace of mind and assurances by choosing a member of the Equity Release Council. We take a look at some of the groups’ rules and guidelines later in this guide, including the negative equity guarantee.
Or you can read our dedicated post about the Equity Release Council here.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
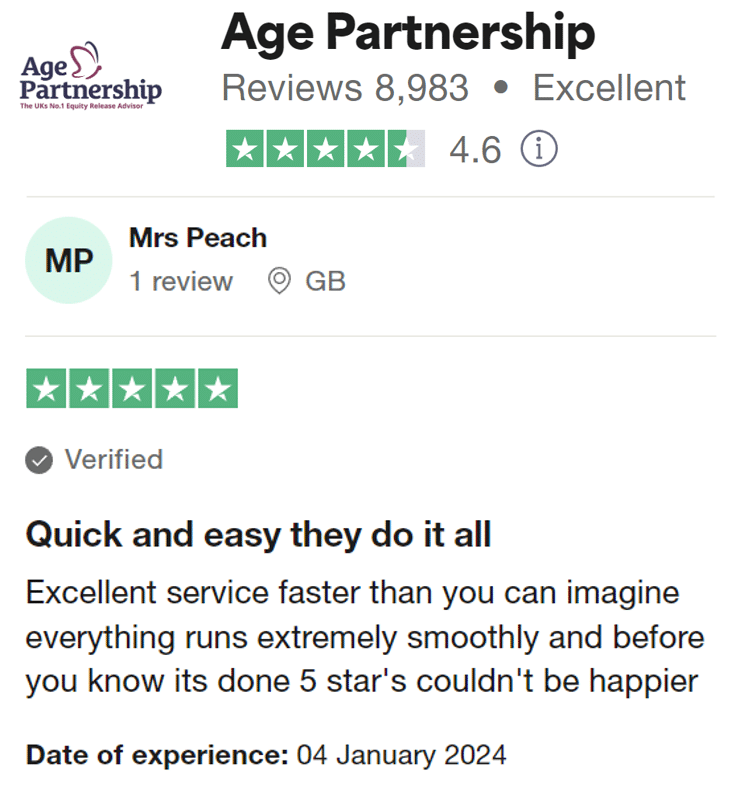
Reviews shown are for Age Partnership. Search powered by Age Partnership.
Some companies to consider
The interest rates you are offered will depend on your age, specifics about your home and the lender. It can be difficult to identify the best equity release companies without this information, especially if you want to compare interest rates to find the best deal. Nevertheless, there are other things to consider which make an equity release company worth considering.
The names below are examples mentioned in this guide, not a verified current best-buy list. Product availability and terms must be checked before relying on them.
#1: LV
Check LV’s current availability, product documents and early-repayment-charge schedule with an adviser. Older terms should not be assumed to apply to a new application.
#2: More 2 Life
Check more 2 life’s current products, early-repayment schedules, moving conditions and borrower-change requirements. Flexibility differs between products.
#3: One Family
Check OneFamily’s current service, market coverage, fees and product availability. Customer-service and value claims require current evidence.
#4: Legal & General
Check Legal & General’s current product criteria and maximum advance for your circumstances; this article does not quote a current lending limit.
#5: Aviva
Aviva’s early-repayment charges depend on the particular product and agreement. Obtain the actual schedule and any exemptions rather than treating 25% as a universal current charge.
How long does it take to get one?
On average, it takes around eight weeks to make your application and get approved for equity release. The process can be lengthy because it involves a re-evaluation of your property, specialist equity release advice and legal services.
What are the benefits of using a Council?
Earlier we told you about the Equity Release Council and how their members are more appealing because they must stick to the group’s rules that have been made in your interest. Some of the additional benefits of choosing a member of the Equity Release Council are:
- For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
- Moving depends on the new property meeting the provider’s criteria; partial repayment or charges may apply.
- Remaining in the property depends on meeting the contract terms, which may include payments, insurance, maintenance and use as your main home.
Does it affect your state pension?
When you take out a lifetime mortgage and receive a tax-free lump sum amount, your wealth instantly increases, which can make you ineligible for some means-tested state benefits. The good news is that your state pension is not means-tested and you will carry on receiving the basic state pension payments no matter how much you have in the bank.
However, pension credit payments that are given to low-income households may be affected by any new-found wealth from your lifetime mortgage. Your payments may decrease or may be stopped. And if you lose access to pension credits, you may simultaneously lose access to other benefits, including council tax reductions.
Drawdown may change the capital held at a given time but does not guarantee benefits eligibility. Obtain advice about capital limits and deprivation rules.
Things to consider
Equity release includes lifetime mortgages and home reversion plans. A lifetime mortgage is a loan secured on your home; a home reversion plan sells part or all of the property. Equity release reduces what may be left in your estate and can affect means-tested benefits and future care funding. A lifetime mortgage is usually repaid when the last borrower dies or moves permanently into care, subject to the plan terms. Specialist financial and independent legal advice are needed. Any existing mortgage must normally be repaid from the proceeds or other funds. Age Partnership publishes an advice fee of £1,995 payable on completion; confirm the current fee in your personalised illustration. Lender and legal fees may also apply.





