Borrowing against home equity: options and risks


Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Looking to free up equity in your house? We’re here to guide you. In this article, we’ll help you understand:
- What home equity is and how it works
- The real price of a bad home equity loan
- What equity release means and its uses
- How to free up home equity
- Some possible problems with equity release
We know that this topic can feel difficult and a bit scary – you might worry about making mistakes or losing money. But we're here to help.
We have the know-how to help you make good decisions about your home equity.
Why do homeowners release equity?
Homeowners choose to use equity release methods for an array of reasons. Some of the most common are:
- Home improvements – completing home improvements can increase the property value and your home equity.
- Debt consolidation replaces selected existing debts with new borrowing. A lower rate or total cost is not guaranteed, and securing previously unsecured debt puts the home at risk.
- Buy another home – the equity can be used to help you put down a deposit for a second home or even help you move home when downsizing.
- Help family – releasing equity is common among older people who want to financially help out younger family members, especially those trying to buy their first property.
How do I release the equity in my home?
Common UK options include a remortgage, further advance, second-charge mortgage or suitable later-life equity-release plan. Any revolving or drawdown facility needs its own availability and terms checked.
We have discussed these options below. If you decide to use one of these methods to release any amount of equity, you should only use a lender that is authorised and regulated by the Financial Conduct Authority. You should also consider the risks and seek professional advice first.
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
#1: What are home equity loans and HELOCs?
Loan-to-value compares secured borrowing with the property’s value, not with the equity alone. A second-charge lender normally considers the existing mortgage and proposed loan together, alongside affordability and credit criteria. There is no universal percentage of equity you can borrow.
A secured loan may pay a lump sum with fixed or variable interest and agreed repayments. A US-style home equity line of credit (HELOC) should not be assumed to be a standard UK product. Any UK revolving or drawdown secured facility has its own availability, fees and payment terms. Check whether interest or capital payments are required during the drawdown period and how the balance must be repaid.
How do you qualify for a home equity loan?
Age, residency, income, property use, loan size and equity requirements are set by the lender. There is no general rule requiring occupation for six months of every tax year. See related guidance.
Upon application, the lender will assess your personal finances and income to ensure you can repay the debt in full. They’ll also complete a close search of your credit score and you may be rejected if you have unpaid debts and defaults.
#2: Remortgaging
You can release equity from your home by remortgaging. Understanding how to remortgage to release equity is fairly simple. When you apply for a new mortgage, you will apply for the same amount of money needed to repay your existing mortgage (consider early repayment fees too!) and then ask for an additional amount based on how much equity you wish to release.
For example, if you have a £100,000 existing mortgage and £100,000 in home equity, you could look for a new mortgage asking to borrow £130,000. This money will be used to pay £100,000 to your existing mortgage provider and you’ll have also released £30,000 equity.
How easy is it to remortgage to release equity?
The process of remortgaging to release equity is fairly simple. There are scores of lenders around that are willing to provide a new mortgage and simultaneously assist you in unlocking equity, but your applications will be subject to personal finances and your credit score. Lenders will need to know about all aspects of your finances to make a decision.
Remortgaging to release equity is more about getting it right and utilising a deal that doesn’t drastically increase your loan to value ratio and the interest payable. You’ll also need to factor in early repayment fees on your current mortgage.
Should I remortgage to pay off debts?
Compare the total amount repayable, interest, all fees, the term and early-repayment charges. A lower monthly payment can mean a longer term and a higher total cost. Securing previously unsecured debt against your home puts the property at risk if you cannot keep up repayments.
However, this should be approached on a case-by-case basis considering other fees and charges. There may be more advantageous ways to consolidate debts, such as an unsecured debt consolidation loan or a balance transfer credit card.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. A lower monthly payment may mean paying more overall, and secured borrowing puts your home at risk if repayments are not maintained.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
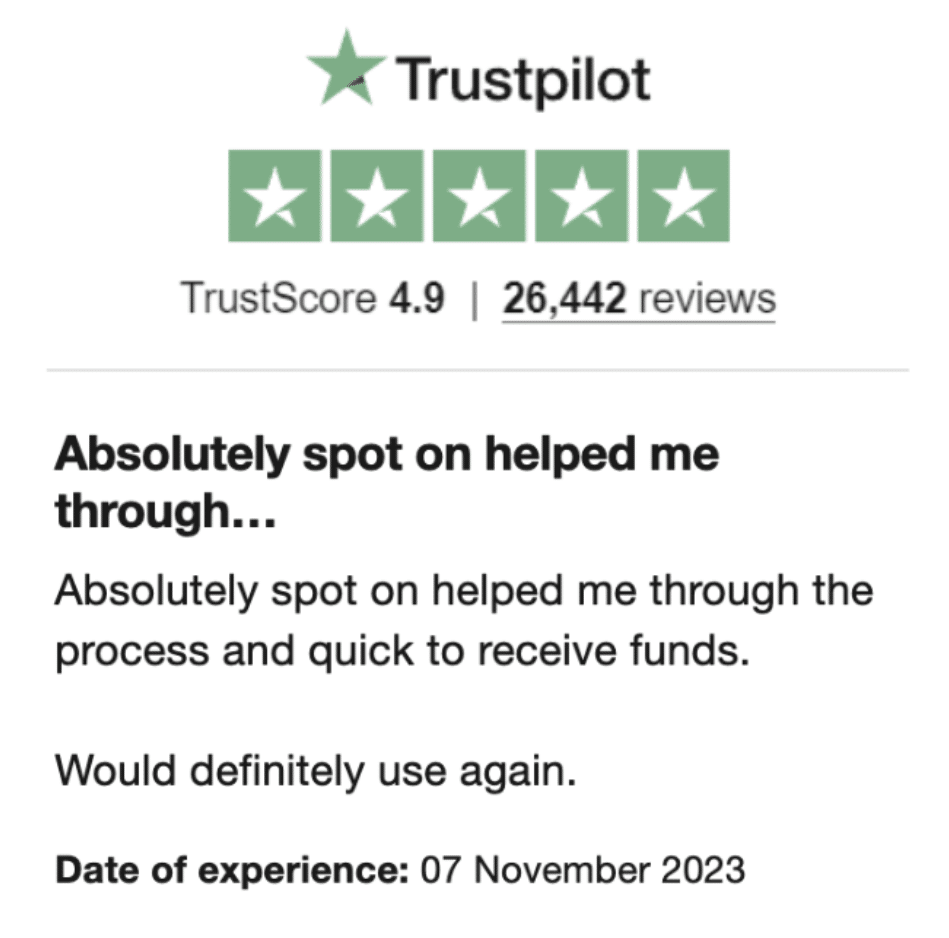
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
#3: What is a lifetime mortgage?
A lifetime mortgage is a loan secured on your home, normally repayable after the last borrower dies or moves permanently into care. Unpaid interest compounds; some plans allow optional payments and some require payments for a period. Eligibility and borrowing limits are product-specific.
A lifetime mortgage can reduce the estate left to beneficiaries, affect means-tested benefits and involve substantial interest and fees. Obtain an itemised quote and specialist advice; a sale may be avoided if other funds repay the loan with the lender’s agreement. See related guidance.
Having no intended property beneficiary does not by itself make equity release suitable. Consider future housing, care needs, benefits and alternatives.
Are there any downsides?
The biggest pitfall of releasing equity from an asset is releasing too much equity or more than what you need.
Keeping this credit unused in a modern low-rate savings account or spending it unnecessarily will only put you in a worse financial position. Even with a low-interest rate on a new mortgage, loan, HELOC or lifetime mortgage, you’re highly likely to be paying more than what you could save with the funds in the best UK savings account. Moreover, lenders will generally charge you higher interest if you start tapping into a lot of equity.
For these reasons and others, it is recommended that you only release equity that you genuinely need and nothing more. Of course, it can be difficult to accurately predict how much money you will need if you are completing large home renovations, but there is a solution for this.
A drawdown reserve is part of the agreed lifetime-mortgage arrangement. Access, future rates and limits depend on its terms; interest generally starts on money when drawn, not merely reserved.
What is negative equity?
Negative equity means secured debts exceed the property’s current value. A £190,000 home with £100,000 secured debt has £90,000 equity, not £10,000 negative equity. If secured debt were £200,000 instead, the shortfall would be £10,000.
Property-price falls, added charges or growing debt can cause negative equity. Borrowing limits vary and do not eliminate this risk; lifetime mortgages do not have a universal 85% limit.