Equity Release

Home reversion providers: how to compare plans

Scott Nelson MoneyNerd Janine Marsh MoneyNerd
By
Scott
Scott Nelson MoneyNerd

Scott Nelson

Debt Expert

Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

Learn more about Scott
&
Janine
Janine Marsh MoneyNerd

Janine Marsh

Financial Expert

Janine contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations.

Learn more about Janine
· Oct 4th, 2026
Estimate how much equity you might be able to release
25000

In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.

MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.

Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
Best Home Reversion Companies

MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.

Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.

This guide explains home reversion and the terms to compare with specialist advice. It is not a live ranking of the best providers.

This guide explains the main options, conditions and risks to discuss with a qualified adviser.

In this article, we’ll discuss:

  •  How equity release works and what it involves
  •  The benefits and drawbacks of home reversion plans
  • How to check current home-reversion availability and provider permissions
  •  Other ways you can use your home to help your finances
  •  Things to think about before you decide on a home reversion plan

So, let’s get started. It’s time to learn more about home reversion plans and how they could help you.

Estimate how much equity you might be able to release

Answer below for an estimate. This is not an offer or a recommendation that equity release is suitable for you. Compare the costs, risks and alternatives with a specialist adviser.

25000

In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.

What are the different types of equity release?

The two main types of equity release are lifetime mortgages, which are loans, and home reversion plans, which sell property rights.

A lifetime mortgage is a loan secured on your home; you retain ownership. Interest that is not paid is added to the balance. The loan is usually settled when the last borrower dies or moves permanently into care, subject to the contract. Required or optional repayments vary by product.

The second type of equity release scheme is a home reversion plan, which is the focus of this MoneyNerd guide. Read on to learn how a home reversion plan works and what home reversion companies are around in the UK today. 

Do you receive a tax-free lump sum?

A home reversion provider pays for a share of your home. Payment arrangements and access to any later amount depend on the contract; this is not a loan held in a reserve account by default. See related guidance.

Staged payments may help budgeting, but availability and benefits effects need individual assessment. They do not guarantee means-tested support.

What is the catch?

Using equity release to retire early or improve the quality of life within your retirement can sound like a fantastic idea. Without having to make monthly repayments, the chance that you will only repay after death can make equity release tempting. 

Equity release can substantially reduce future inheritance. Costs depend on the actual plan, duration, property value and repayments; there is no universal rule that everyone repays more than double.

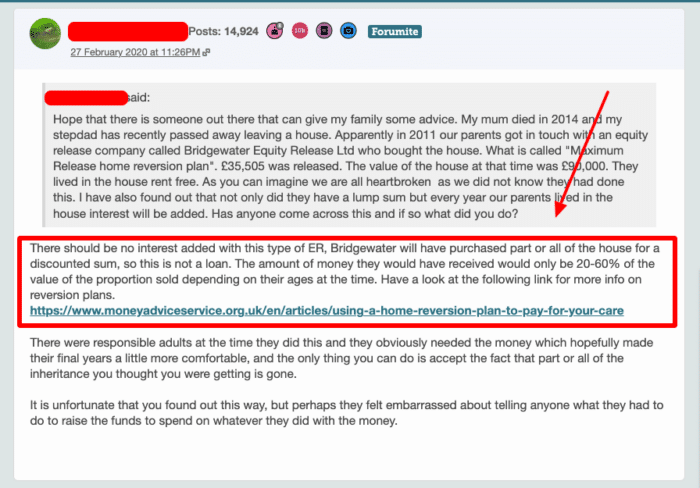
source: https://forums.moneysavingexpert.com/discussion/comment/76884832#Comment_76884832

What is a home reversion mortgage?

Home reversion is not a mortgage or credit agreement: it sells part or all of the home subject to occupancy rights. Read the sale and occupancy terms with your own solicitor.

Consider the costs and risks of equity release

Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.

Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.

Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.

Get started

In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.

How does it work?

A home reversion plan is a sale of part or all of your home, usually below open-market value, in return for money and the right to remain under the plan’s occupancy terms. It is not a loan. The provider receives its agreed share when the home is sold.

No loan interest is charged because the provider purchases a property share. Its entitlement on sale follows the agreed ownership share and terms.

The cash paid is usually below the open-market value of the share sold, reflecting the right to remain. This is a sale now, not a promise to sell a share in the future.

The provider shares in later changes in property value according to the agreement; growth and profit are not guaranteed. Buying back a share or ending the plan requires contractual and legal advice, including tax and costs.

The pros and cons

The primary advantages of using a home reversion plan are:

  1. Cash from selling a property share; tax treatment depends on the property and circumstances.
  2. Payment arrangements depend on the specific plan. See related guidance.
  3. Use of proceeds and later tax or benefits effects should be discussed with an adviser.
  4. There are no loan repayments to make
  5. You can remain under the plan’s occupancy terms; check rent, insurance, maintenance and other obligations.

Selling a share below market value reduces the property retained for your estate. The effect on inheritance tax depends on the estate and available allowances, not an automatic loss of the residence allowance.

There are a number of other drawbacks, including:

  1. Ending or buying back the arrangement can be costly and is governed by the contract; it is not an ordinary loan early-repayment charge.
  2. High set -p costs
  3. Could stop your eligibility to receive some benefit payments

Is it a good idea?

A home reversion plan might be a good idea for you, but it will depend on your personal circumstances and any alternative options available. The way to make an informed decision is to get financial advice first. 

Do not just use any financial adviser, but opt for advisers who work frequently in equity release. You may want to give preference to finance advice companies that are members of the Equity Release Council. 

A home reversion plan can help many people with their money problems, but it has a lot of legal complexities that need to be carefully negotiated to protect the homeowner’s best interests. To make sure the transaction is legal, clear, and fair, it is important to hire a solicitor who knows about equity release and what it means.

Exploring Alternative Financial Routes

Before opting for a home reversion plan, it’s crucial to explore various alternative financial paths that might align better with your financial strategy, personal circumstances, and long-term objectives. Here’s a breakdown of some alternative routes to consider:

1. Downsizing:

This involves selling your current property and moving to a smaller, less expensive one to free up cash.

  • Pros: Potential to release a substantial lump sum and lower living costs.
  • Cons: Emotional and practical implications of leaving a family home, moving costs, and possible impact on inheritance.

2. Renting Out Part of Your Property:

This involves creating an income stream by renting out a room or a section of your home.

  • Potential income, subject to permissions, demand, expenses and any qualifying Rent-a-Room relief.
  • Cons: Loss of privacy, the potential for disruptive tenants, and the possible need for landlord insurance.

3. Lifetime Mortgage:

This is a type of equity release where you take a loan against your home’s value, and the loan plus interest is repaid when the property is sold after your death or moving into long-term care.

  • You retain ownership with a lifetime mortgage; payment requirements depend on the plan.
  • Cons: The debt can grow quickly due to compound interest and may significantly reduce the inheritance.

4. Drawing on Savings or Investments:

This involves using your savings or liquidating investments to fund your retirement or specific needs.

  • Pros: No need to encumber your property or accrue debt.
  • Cons: Reduces your financial buffer and might expose you to higher risks depending on your investment portfolio.

» TAKE ACTION NOW: Find out how much equity you could release

Are the plans regulated?

Verify the provider’s identity and relevant permissions directly on the FCA Register before proceeding.

The Equity Release Council is another body that aims to improve standards of lending within the industry and to provide homeowners with additional protection when taking out home reversion plans or a lifetime mortgage. 

Lenders are not forced to become a member of the Equity Release Council but many do. When they joint they agree to follow a number of rules which benefit the senior homeowners, such as the infamous negative equity guarantee that stops lenders from chasing debts not completely repaid via the property sale. However, this particular rule only benefits people who have a lifetime mortgage loan. 

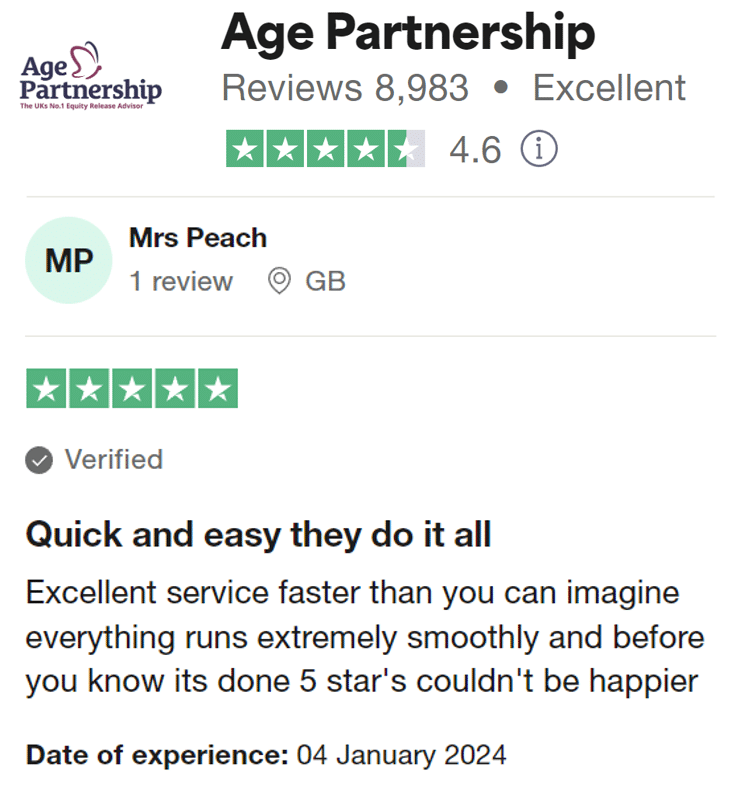
An Age Partnership customer’s experience

Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham

“I am more than pleased to have taken out Equity Release with Age Partnership.”
Get started

Reviews shown are for Age Partnership. Search powered by Age Partnership.

Who are the providers (UK)?

The following are historical names mentioned in the sector, not confirmed current home-reversion offers. Ask an authorised specialist to verify availability before relying on them:

  1. Hodge Lifetime
  2. Crown Equity Release
  3. Newlife
  4. Bridgewater Equity Release

I always advise you to complete your own research so you don’t miss out on changes in the industry and new deals. But remember to only consider those that are regulated by the Financial Conduct Authority. 

Start by looking at an equity release calculator

Check that any calculator specifically models home reversion rather than a lifetime mortgage. Estimates cannot confirm the purchase price, share sold, legal terms or suitability; obtain an individual illustration.

For more information on lifetime mortgages, reversion schemes and anything else to do with equity release, you’re already in the right place with MoneyNerd! 

Things to consider

Equity release includes lifetime mortgages and home reversion plans. A lifetime mortgage is a loan secured on your home; a home reversion plan sells part or all of the property. Equity release reduces what may be left in your estate and can affect means-tested benefits and future care funding. A lifetime mortgage is usually repaid when the last borrower dies or moves permanently into care, subject to the plan terms. Specialist financial and independent legal advice are needed. Any existing mortgage must normally be repaid from the proceeds or other funds. Age Partnership publishes an advice fee of £1,995 payable on completion; confirm the current fee in your personalised illustration. Lender and legal fees may also apply.

Estimate how much equity you might be able to release

Answer below for an estimate. This is not an offer or a recommendation that equity release is suitable for you. Compare the costs, risks and alternatives with a specialist adviser.

25000

In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.

Did you like this article?
Show your support ❤️
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
We are so sorry...

Is there something missing? We’re all ears and eager to improve. Send us a message and let us know how we can make our article more useful for you.

You can email us directly at [email protected] to share your feedback.

The authors
Scott Nelson MoneyNerd
Author
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
Janine Marsh MoneyNerd
Financial Expert
Janine contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations.