Scott and Co Debt Collectors – Should You Pay?


For free & impartial money advice you can visit MoneyHelper. We work with The Debt Advice Service who provide information about your options. This isn’t a full fact-find, some debt solutions may not be suitable in all circumstances, ongoing fees might apply & your credit rating may be affected.


For free & impartial money advice you can visit MoneyHelper. We work with The Debt Advice Service who provide information about your options. This isn’t a full fact-find, some debt solutions may not be suitable in all circumstances, ongoing fees might apply & your credit rating may be affected.
Have you received a letter from Scott and Co Debt Collectors? You’re not alone! Each month, over 170,000 people visit our website to get guidance on debt issues
This article will answer common questions like:
- Is Scott and Co a real debt collectors firm?
- Where did this debt come from?
- Should I pay this debt?
- What happens if I can’t afford to pay?
- Can I stop them from taking more action?
Research shows that 64% of people in the UK find dealing debt collectors stressful1. So, we truly understand how you feel and are here to help.
Let’s dive in and learn more about Scott and Co Debt Collectors and what you can do if they contact you.
Why have you received a letter?
You’ll start receiving Scott & Co debt collection notices through the post as they are working on behalf of a client.
While they work with many private companies, they do a lot of public sector work and often get in touch regarding unpaid council tax bills2.
Unpaid Council Tax
As mentioned, Scott & Co are tasked to recover council tax arrears.
How a debt solution could help
Some debt solutions can:
- Stop nasty calls from creditors
- Freeze interest and charges
- Reduce your monthly payments
A few debt solutions can even result in writing off some of your debt.
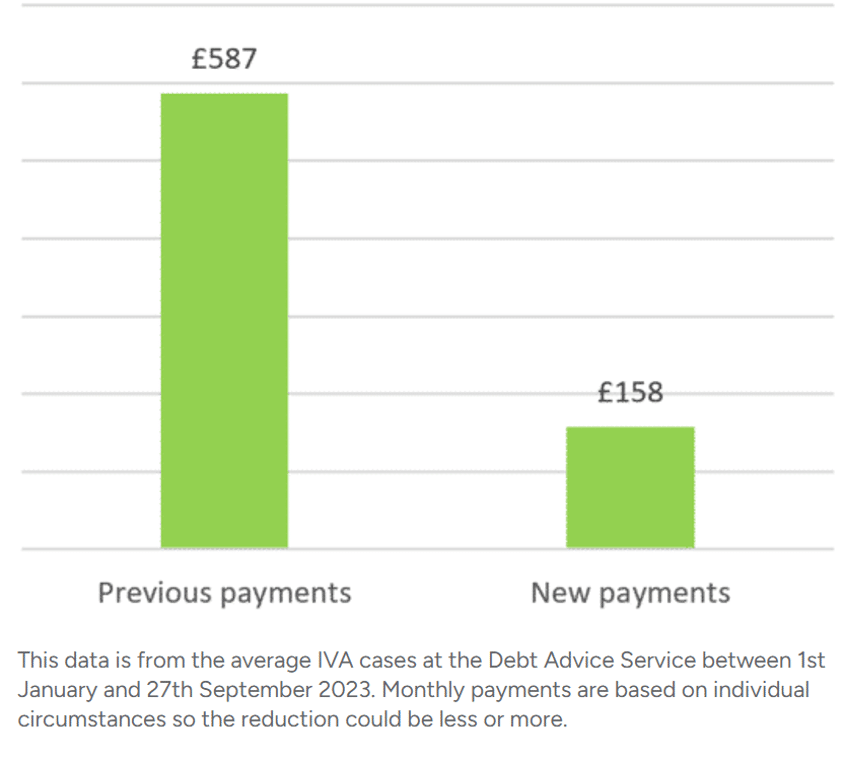
Here’s an example:
Situation
| Monthly income | £2,504 |
| Monthly expenses | £2,345 |
| Total debt | £32,049 |
Monthly debt repayments
| Before | £587 |
| After | £158 |
£429 reduction in monthly payments
If you want to learn what debt solutions are available to you, click the button below to get started.
MoneyNerd does not provide debt advice. We may introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, which can provide information about debt solutions and your available options. Fees may be payable if you enter into a formal debt solution. MoneyNerd Limited may receive a referral fee. Entering into a debt solution may affect your credit rating. Free debt guidance is available from MoneyHelper at moneyhelper.org.uk.
What happens if you don’t pay?
The average unsecured debt has increased by 25% year-on-year, rising to £13,9413. So it’s common for people to struggle with debt.
If you find yourself in this situation and can’t pay Scott & Co, it’s important to talk to them so you can arrange an instalment plan.
Keep in mind that if you refuse to pay, the consequences can be extreme.
1. Earnings arrestment
2. Bank arrestment
Will they be able to come to your home?
Our financial expert, Janine, explains that having a debt collector at your door can be scary, especially when you are already under huge financial stress.
But It’s crucial that you stay calm and know your rights. They have no power to enter your home or take any of your possessions.
» TAKE ACTION NOW: Fill out the short debt form
Typical Collection Process
We’ve put together this quick table to help you better understand the debt collector timeline and the actions involved. For more information, be sure to check out our specialized guide.
| Stage | Actions | What you should do: |
|---|---|---|
| Missing one or two small payments | Calls and letters from the debt collector asking for payment. They may enquire about reasons for missing payments. | Contact the debt collector and offer to pay what you can. If you are struggling to pay the debt, get in touch with us to explore your options. |
| Missing large or multiple payments | Their contact will become more frequent, urgent, and threatening. | Contact the debt collection agency and offer to pay what you can. You may also make a complaint if you think the letters are a form of harassment. |
| Debt collector visit | After a few months, if the debt is significant (£200+) you will receive notice of a debt collector visit. They have to notify you before arriving. Debt collectors cannot take anything from your home – they may only ask for payment. | If a debt collector shows up at your home, ask them to show proof of the debt and their ID through a window. Do not open your door or let them in. You can arrange a payment plan with the debt collector, but make sure to get a receipt of this. |
| Court | If you still do not pay your debts to the original lender/debt collector agency, they will take you to court and either attempt to: – File a CCJ against you. – File an attachment of earnings order. – File a lawsuit against you. |
You must show up to your court date. From here, you can either dispute the debt, or the judge will likely suggest a manageable repayment plan for you. |
How can you get help?
Thousands have already tackled their debt
Every day our partners, The Debt Advice Service, help people find out whether they can lower their repayments and finally tackle or write off some of their debt.
Natasha
I’d recommend this firm to anyone struggling with debt – my mind has been put to rest, all is getting sorted.
Reviews shown are for The Debt Advice Service.
How do you stop additional action?
Debt repayment plans with Scott & Co are possible, but we suggest you contact the debt collector as soon as possible after seeking debt advice from an expert, that is.
Can you complain about them?
Scott and Co Contact Details
References