Secured loans and spouse consent: ownership and rights


Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Whether a secured loan requires a spouse’s involvement depends on ownership, occupation rights, lender conditions and the legal documents. Do not assume sole registered ownership guarantees a loan can be arranged privately.
This guide explains the consent and disclosure issues to check before borrowing against a home.
In this simple guide, we’ll cover:
- What a secured loan is.
- The true cost of a bad secured loan.
- The credit score needed for a secured loan.
- What happens when you apply for a secured loan.
- Consent, disclosure and confidential advice options
Maybe you’re worried about the potential consequences of a secured loan, or perhaps you’re dealing with debt. We understand these concerns, and we’re here to give you the information you need to make the best decision for your situation.
Can I get one without letting my spouse know?
For a charge over a jointly owned home, the lender normally requires the relevant owners’ agreement and signatures. Legal advice is needed about any proposed charge and existing rights.
The lender and solicitor must verify ownership, existing charges and any required consents before completion.
Even if only one spouse is on the title, the other may have occupation or home rights and the lender may require an occupier’s consent. Sole ownership is not a guarantee of secrecy or that no consent is needed.
Applications may involve valuation, identity, correspondence and legal checks. Give accurate information about all owners and occupiers and ask the solicitor what consent is required.
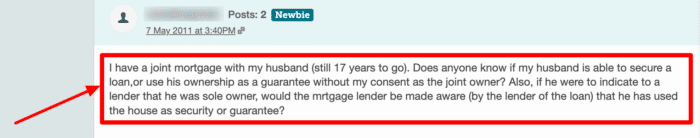
This forum user on MoneySavingExpert wants to know if her husband is able to take out a secured loan against their property without her knowing or giving her consent.
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Case Study
There are many different types of secured loans out there. To help you better understand how secured loans work and the process they typically follow, here’s a quick case study.
| Category | Illustrative example |
|---|---|
| Background | Fictional example: John is a homeowner considering £20,000 for renovations. This is not a real customer story or a lending offer. |
| Application | A lender would assess property value, existing borrowing, income, expenditure and credit history. Approval is not guaranteed. |
| Costs | John would compare personalised APRC, fees, monthly payments, repayment term and total repayable. Rates and terms vary; no rate or monthly cost is assumed here. |
| Potential benefit | A secured loan might provide funding while retaining an existing mortgage, but other funding options could be cheaper or more suitable. |
| Risks | John’s home may be repossessed if required payments are missed. Fees, early-repayment charges and a longer term can increase total cost. |
| Possible outcome | The result depends on affordability, payments, interest rates and property values. Neither a higher credit score nor an increase in property value is guaranteed. |
Will he find out if I take out a loan?
An unsecured application in one person’s name is different from granting security over a home. Do not sign for another owner or omit information the lender requests. See related guidance.
If you need private help with money worries, seek confidential debt or legal advice before taking new credit. A lender cannot guarantee that borrowing will remain unknown to other household members.
If control of money or concern about a partner’s reaction is part of the problem, a confidential support service can help you consider safe options. Choose a contact method that is safe for you.
There are lots of ways of dealing with money problems that you might not be aware of – in my experience, a loan isn’t always the best solution.
If you find yourself in a challenging financial situation, you could consider seeking financial counselling from UK-based charities such as StepChange or National Debtline, which offer free debt advice.
Enquire about a secured loan through Loans Warehouse, a credit broker, not a lender. Approval and terms depend on checks. Compare the full cost before applying. MoneyNerd may receive a referral fee. Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Can one person take it out on a joint account?
Whether one holder can authorise a payment from a joint account depends on the account mandate and bank’s rules.
Many joint accounts allow either holder to set up a Direct Debit; others require joint authority. Check the mandate rather than assuming both signatures are always required.
Card and recurring-payment authority depends on the account and card terms. Do not use payment arrangements as a way to bypass a co-owner’s required consent.
In either case, the other person will be able to see the payments to the lender leave the account each month on their bank statements.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. Securing borrowing against your home puts it at risk if you cannot keep up repayments.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
What happens when you apply?
When you apply for a secured loan, you must fill in all your personal details and prove a number of things, including:
- Prove your identity
- Prove your income
- Prove your address
- Prove ownership of the asset, which is usually your property
- Prove the amount of equity you have in the property
Timescales depend on the lender, valuation, legal checks and documents. Request an estimate for your case; approval and completion within two to six weeks are not guaranteed.
Compare the full cost of a secured loan
Compare the APRC, fees, monthly repayments and total amount repayable over the full loan term. A lower monthly payment can mean paying more overall if the loan runs for longer.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. MoneyNerd introduces enquiries and may receive a referral fee. Fees and charges may apply to the loan and broker service.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Enquire about a secured loan through Loans Warehouse.
References