


Can I Transfer Catalogue Debt to a Credit Card?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you trying to find out if you can move your catalogue debt to a credit card? This guide is here to help. Each month, over 170,000 people visit our site seeking advice on debt solutions.
In this simple guide, we’ll explore:
- The process of transferring catalogue debt to a credit card
- The benefits of this kind of debt transfer
- Other ways to manage or reduce your catalogue debt
- What might happen if you stop paying your catalogue debt
We know it can be worrying if you can’t pay your catalogue debt. It can be hard to know what to do or who to talk to. Citizens Advice says that catalogue shoppers who miss payment deadlines get charged very high fees, sometimes more than twice what they borrowed.1
But remember, you’re not alone. We’re here to help you understand your choices and make the best decision.
How can I transfer it?
Many credit card companies, especially those with 0% interest rates, don’t allow you to transfer catalogue balances directly to a credit card.
However, the interest on cash withdrawals on your credit card may still be less than you are paying on your catalogue.
Read on to find out how you can transfer your catalogue debt onto a credit card.
Balance transfer options
I’ve listed some balance transfer credit cards worth considering here:
- NatWest offers a No fee balance transfer card with a 19-month balance transfer period and a 23.9% representative APR
- Sainsbury Bank’s low balance-transfer fee credit card with long NO fee (some people may pay a 1% fee) with a 14-month balance-transfer period and 23.9% representative APR. (some people could be offered a 12 month deal)
- MBNA No fee balance transfer card with up to 15-month balance transfer period and a 22.9% representative APR
I suggest you seek advice from a debt expert when considering your credit card balance transfer options.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What are the benefits of doing it?
By transferring a catalogue debt to a credit card, you could benefit from a lower interest rate. It’s one of the debt management strategies worth considering.
For example, many catalogues charge up to 40% APR, whilst credit card interest rates are normally much lower. And sometimes 0%.
You could also benefit from fewer monthly payments by consolidating catalogue debt meaning that things are easier to keep track of.
Case Study: Very credit card debt
See this question one person with a catalogue debt asked on a popular online forum.
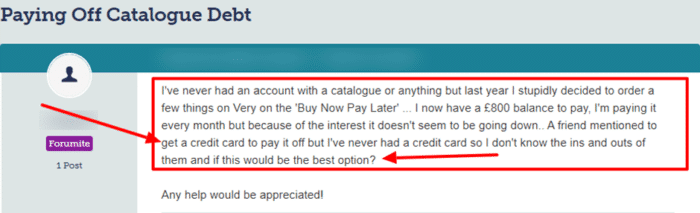
Source: Moneysavingexpert
If you already have one
If you already have a credit card, you can check what interest rate you are paying on that card. Then compare it to the interest rate being charged by your catalogue company.
If the interest rate on your credit card is lower, you can check with your bank to see if you can use your credit card to pay off your catalogue debt.
If your bank does not allow direct balance transfers from catalogues, you can still check if the interest on cash withdrawals is charged at a lower rate than your catalogue interest rate.
In these cases, you can borrow the money from your credit card and use those funds to pay off the catalogue debt.
In effect, you’re transferring your catalogue debt amount to your credit card.
Applying for a new card
You may want to apply for a credit card to either transfer your catalogue debt or allow you to pay it off.
There are some interesting balance transfer cards which allow you to borrow money at 0%. It could be an option worth considering.
You can use that money to settle the catalogue debt. The added benefit is that you may not have to pay a balance transfer fee.
Even if you can’t get accepted for a 0% card, your catalogue balance may still be better off moved onto a credit card with a lower interest rate, so you save on interest.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Are there any drawbacks to balance transfers?
There are some drawbacks to transferring catalogue debt to a credit card. I’ve listed some of them here:
- Some balance transfers charge a fee
- A low or 0% interest won’t last forever
- It could add to your existing debt
- You may need a good credit score
What happens if I stop paying?
A catalogue company can chase debt in the same way as any company. They take handling catalogue arrears seriously.
It happens if you miss a payment, or can’t make the agreed payment (but still pay less) and signed an agreement to pay certain amounts on specific dates.
If you stop paying your catalogue, or don’t pay the agreed instalment amount, the company will normally first ask you to pay these arrears.
If you can’t pay the arrears, your account will be placed in “default“. Your account is frozen to stop you from purchasing any more goods and therefore adding to the debt.
» TAKE ACTION NOW: Fill out the short debt form
The catalogue company could also add to the debt by charging you penalty fees and administration costs.
Your individual contract with the catalogue company will detail any charges or fees on defaulted accounts within the terms and conditions.
It is a good idea to check your agreement if you cannot afford to pay your monthly instalments, so you are aware of the terms and what costs could be added.
If you can’t pay the arrears, or keep up with your monthly payments, the account will default and further action could be taken against you.
To avoid missing payments and incurring further debt, please take a look at the table below, which contains some common debt solutions you can take advantage of.
| Option | How it works | Key limits and risks |
|---|---|---|
| Debt management plan | Informal repayment of eligible non-priority debts through an affordable budget. | Creditors need not agree, freeze interest or stop court action. Fees apply with some providers; free providers exist. |
| IVA | Formal agreement covering eligible debts and accepted through the creditor voting process. | Fees, credit effects, asset/equity terms and failure risks apply. Payments and term depend on the agreed proposal. |
| DRO (England and Wales) | Normally 12 months of protection before qualifying debts are discharged if the order remains in force. | Current qualifying-debt limit £50,000; strict income, asset, vehicle and residence conditions. Homeowners are not eligible. Application is through an approved adviser to the Insolvency Service, not a court. |
| Bankruptcy (England and Wales) | Formal insolvency that can discharge qualifying debts. | Assets and employment may be affected. Discharge is usually after 12 months, but income payments may continue for up to 3 years. |
| Consolidation loan | New borrowing to repay selected existing debts. | Does not write off debt. Fees or a longer term can increase the total paid; secured borrowing puts your home at risk. |
| Agreed payment break or reduced payments | A temporary arrangement negotiated with the creditor. | Interest may continue, credit reporting can be affected, and the debt remains. Terms require agreement. |
| Informal negotiation | Ask creditors for affordable payments or a settlement. | Acceptance is not guaranteed; record terms in writing. Priority bills still need separate attention. |
| Equity release | Eligible homeowners may access property value through a lifetime mortgage or home reversion. | Reduces the estate and may affect benefits or care funding. Requires specialist advice and comparison of alternatives. |
Common myths debunked
I’ve listed some myths about being in debt here:
- I’ll be blacklisted for missed payments – NOT NECESSARILY TRUE
- I could go to prison for my debts – NOT NECESSARILY TRUE – depends on the type of debt
- My water or energy supply gets cut off when I don’t pay – NOT NECESSARILY TRUE – water can’t be cut off
- All Buy Now Pay Later (BNPL) plans are the same – NOT TRUE
- If I get married, my partner’s debts become mine too – NOT NECESSARILY TRUE
- You have to pay for debt advice – NOT TRUE
- If someone who lived at my address had debts, it’ll affect me as well – NOT TRUE
- Creditors can send bailiffs to my house to recover payments – NOT TRUE
References
- Citizens Advice – Catalogue customers hit hard for missing interest free deadlines



