Unsecured Debt Consolidation Loans for Bad Credit


“If you’re looking for a way to handle your debts, this is the right place for you. In this piece, we’ll talk about unsecured debt consolidation loans for bad credit. We’ll be answering the following questions:
- What is debt consolidation?
- How much will a bad debt consolidation loan cost?
- How can you get an unsecured consolidation loan for bad credit?
- What debts can you clear up with a consolidation loan?
- Is a consolidation loan the right choice for you?
We understand your worries about unpaid debt, and we're here to help.
Remember, you’re not alone. There are many ways to handle debt, and we’ll guide you through them. Let’s start our journey into the world of debt consolidation loans for bad credit.”
How can I consolidate my debt with bad credit?
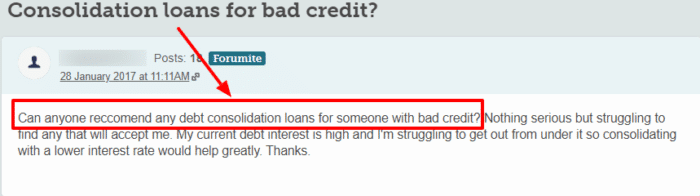
There are still ways to consolidate debts with a bad credit score. Bad credit debt consolidation loans are advertised widely online for people with a less than satisfactory credit rating.
However, these bad credit debt consolidation loans typically have a higher APR representative rate. Or you may still be able to get a debt consolidation loan tailored to people without bad credit, but the rate you are offered can be much higher.
You’ll need to calculate if debt consolidation is still worth it if you have bad credit and can only get personal loans with high interest.
If you are worried about your credit history stopping you from getting loans, you could try and improve your credit score first.
You should look for mistakes on your credit file and have them removed. Or register on the electoral register for a slight credit score boost.
Another option is to consider a DMP instead, which I explain in detail towards the end of this guide.
Enquire about borrowing options through Loans Warehouse
How to get an unsecured consolidation loan
The way to get an unsecured consolidation with bad credit is the same way as you would go about getting any loan with good credit.
You need to search your options and apply truthfully. Most applications are completed online quite easily, but you may be able to apply at a branch if you’re using a high-street bank.
The only difference is when you have bad credit, you should be looking for loans specifically available to you.
Later in this guide, we will provide some examples of unsecured loans for bad credit.
How to find a debt consolidation loan without collateral
An unsecured loan does not use an asset as security at outset, but default can still lead to court action, enforcement or a charging order. Compare affordable terms rather than treating it as risk-free.
People with a poor credit rating may want to search for online lenders as well. Most debt consolidation options for people with poor credit reports are typically offered by online loan providers and less so by high-street banks.
Types of unsecured consolidation loans for bad credit
You can find unsecured debt consolidation loans for bad credit by searching online. There are even websites that allow you to compare your options.
You can also use a credit broker if preferred, though this may come with an additional cost.
These historic provider names are not a verified current ranking or product panel. Check current availability, the firm’s FCA permissions and whether it is a lender or broker before relying on an offer.
1. Pegasus
Check the current firm, lender or broker role, and available products behind the Pegasus name. Historic amounts and APRs are not verified current offers.
Verify review dates and funding conditions independently; neither positive reviews nor an advertised timescale guarantees acceptance or suitability.
2. Everyday Loans
Verify the current trading name, lender details and application route before relying on older references to Everyday Loans.
Compare an actual current quotation; the historic APR and review claims here do not establish today’s terms or service.
3. Finio Loans
Check current Finio availability and eligibility directly; do not rely on historic loan amounts, terms or APRs.
4. Solution Loans
Check whether Solution Loans acts as a broker, its current panel and any fees. The lender named in the credit agreement is responsible for the loan.
5. Koyo Loans
A historic Koyo listing should not be treated as an available new-loan offer. Verify whether any firm mentioned is servicing existing loans or accepting new applications.
6. 118118 Money
Check current 118118 Money product details and your personalised quote; the previous amount, term and APR figures are not a live offer.
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Can my bank give me one?
Your bank will apply its own eligibility and affordability rules, which may differ by product and customer relationship.
Income, commitments and credit history matter; existing-customer status may also affect eligibility or the application process.
There is no way of saying if your credit record will stop your bank from approving the loan because the FCA allows each institution to complete its own assessments while following guidelines.
Funding speed depends on approval and checks, not simply whether you already bank with the lender.
Consider a debt consolidation guarantor loan
If your credit history is hindering you from getting an unsecured debt consolidation loan, there is another type of loan you may be able to get. Consider a guarantor personal loan.
A guarantor can become liable under the guarantee if you fail to pay. Both parties should understand affordability, the amount covered, credit consequences and any security at risk before agreeing.
The guarantor will need to be someone who trusts you to make repayments on time and repay the full loan amount. It is usually a family member or partner.
Check whether any named guarantor-loan provider is currently accepting applications and how the guarantee works; this guide does not verify a current offer.
What about an alternative?
An alternative to consolidation that is a lot like consolidating debts is a Debt Management Plan (DMP).
A DMP is when you agree with a group of your creditors to make a single monthly payment, and then that payment is divided between them based on how much you owe each of them.
In a simplified example, instead of making five payments of £50 each month, you can try to negotiate to make one payment of £250, which is split between all five.
This doesn’t necessarily consolidate debts, but it does allow you to benefit from single monthly payments. However, most people try to negotiate lower payments or repayments without any interest added.
A DMP is an informal repayment arrangement, not new borrowing. Creditors may refuse, continue interest or take action, and reduced payments can affect your credit file. Free providers are available.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. A lower monthly payment may mean paying more overall, and secured borrowing puts your home at risk if repayments are not maintained.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
What debts can I resolve with a consolidation loan?
An unsecured personal loan to consolidate debt can be used to pay off store cards, credit cards and other personal loans.
Note that a balance transfer credit card can only be used to resolve other credit card debts.
How much can I borrow?
Each lender will offer personal loans up to different amounts and repayable over different periods of time.
Each lender sets eligibility and affordability requirements. There is no universal UK credit-score threshold or guarantee of approval; income, commitments, credit history and any proposed security all matter.
Is it right for me?
Compare the total amount repayable, interest, all fees, the term and early-repayment charges. A lower monthly payment can mean a longer term and a higher total cost. Securing previously unsecured debt against your home puts the property at risk if you cannot keep up repayments.
But this doesn’t mean it’s guaranteed to be the best option for you. There could be a better method and a more efficient debt solution that fits your situation.
Only consolidate your debt if:
- You will save money even after the fees and charges of the loan have been paid
- You can afford to keep up payments until the loan is repaid
To discover what debt solution best fits your financial situation, I suggest you speak with a UK debt charity.
Charity advisors from National Debtline or StepChange will provide tailored advice and support. With their free help, you could avoid any mistakes and get out of debt with a more advantageous method.
A Debt Relief Order may write off qualifying debts after the moratorium if its conditions are met. Eligibility, excluded debts and consequences must be checked with an approved debt adviser; it is not available to homeowners.