


Repaying Tax Credit Overpayments in Instalments


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Struggling to pay off tax credit debt in one go? You’re not alone, and help is at hand.
Tax credits ended on 5 April 2025, but outstanding overpayments can still be recovered. The right contact depends on whether HMRC or DWP is handling your debt.
In this article, we’ll talk about:
- What to do when you have tax credit overpayment.
- How to pay back tax credits in instalments.
- The length of time you have to pay back tax credit overpayment.
- Any changes you can make to your repayments with HMRC.
- What to do if you’re struggling with unaffordable debt..
Check the overpayment notice, outstanding balance and recovery department. If the figures are wrong or payment is unaffordable, ask for help promptly.
Let’s dive in and find out more about how you can pay back your tax credit debt in manageable instalments.
How to pay an overpayment?
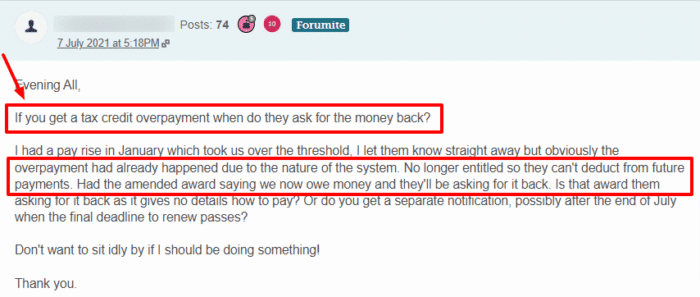
When you first receive a letter from HMRC informing you of your tax credit overpayment, it’ll have details about the overpayment as well as information about how they want you to pay them back.
There are no ongoing tax-credit awards from which to make new deductions: tax credits ended on 5 April 2025. Older explanations about deductions from future tax-credit payments are no longer current.
Some debts are recovered by DWP, including through Universal Credit, while others remain payable directly to HMRC. Follow the latest verified notice for your case.
Before making a payment, establish:
- Whether the debt remains with HMRC or has transferred to DWP or, in Northern Ireland, the Department for Communities.
- Which award period and single or joint claim the overpayment relates to.
- The current balance and correct payment reference; do not assume a new relationship or claim cancels an earlier debt.
If you’re having trouble finding the details of your overpayment by HMRC, then you can call the tax credits helpline to find out information about it.
For difficulty repaying an HMRC tax-credit overpayment, the current payment-enquiries number is 0300 200 3800, Monday to Friday, 8am to 5pm, excluding bank holidays. If HMRC or its collection agent has already contacted you, use the verified contact instructions provided for the case.
When you make any such call to HMRC or any other organisation, make a note of the date and time when the call was placed.
Also, ask and take note of the person who spoke to you over the phone. You may need this information later on if a problem arises with your HMRC overpayment.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Can I pay in instalments?
HMRC may agree to repayment by instalments. Contact the tax-credit payment-enquiries team with your reference and an affordable budget. If the debt has transferred to DWP, discuss repayments with DWP instead.
You should suggest a realistic amount that you are able to repay each month. After the conversation, you should make a note of the date and time of the call, in addition to the name of the person you spoke to at HMRC.
| HMRC payment enquiries | 0300 200 3800: help if you cannot repay the full amount. |
| Calls from abroad | Use the current GOV.UK payment-enquiries page or the verified instructions on your notice for the appropriate contact route. |
| Accessibility or language support | Check HMRC’s current extra-support arrangements before calling. |
| DWP Debt Management | For a debt transferred to DWP: 0800 916 0647; Relay UK 18001 then 0800 916 0647. |
Relay UK connects people who cannot hear or speak on the phone through an app or textphone. Follow the service instructions and dial the appropriate prefix and number; sending an ordinary text to 18001 is not the procedure.
Bear in mind that entering into a repayment plan with HMRC generally does not directly affect your credit rating. But if you do not keep up with repayments and HMRC takes further action (e.g. CCJ), this could hurt your credit score.
Can I make a payment online?
If HMRC is still responsible for your debt, use its current official payment instructions and the 16-character payment reference from the notice to pay. Confirm the recipient before paying, particularly if the debt has transferred to DWP.
HMRC says Faster Payments and CHAPS normally arrive the same or next working day; Bacs normally takes three working days. Check your bank’s limits and processing times and allow the payment to arrive by the deadline.
| Sort Code | Account Number | Account Name |
| 08 32 10 | 12001039 | HMRC Cumbernauld — verify these details and your payment reference on GOV.UK before sending money; DWP debts use different details. |
How long do you have to pay it back?
HMRC’s notice to pay normally asks for payment within 30 days. If you need instalments or dispute the amount, contact the appropriate team promptly rather than assuming that any small payment automatically creates an arrangement. See related guidance.
If you plan to pay in instalments, it is crucial that you agree upon an instalment plan with HMRC during this time.
Failure to resolve the balance can lead to further recovery action. Most tax-credit overpayments do not attract interest; separate rules can apply to fraud or neglect and penalties. Ask for the legal basis of any extra amount rather than assuming automatic late-payment interest.
Universal Credit (UC)
HMRC may transfer tax-credit debt to DWP for recovery, including deductions from Universal Credit. Check the transfer notice and UC statement so you know which department now controls repayment. See related guidance.
Deductions do not require you to agree a separate voluntary payment plan, but you should receive information about the transferred debt and can ask for the calculation and recovery details.
HMRC explains the transferred tax-credit debt, while DWP or your UC statement provides the deduction information. Keep both departments’ notices and query discrepancies.
If DWP deductions cause hardship, contact DWP Debt Management or raise the issue through the relevant Universal Credit channel and request an affordability review. See related guidance.
The usual maximum deduction for debt repayment is 15% of the Universal Credit standard allowance, not 40% of the whole award. Exceptions, including last-resort deductions, can apply. The standard allowance excludes additional elements such as housing support. Ask DWP to explain the deductions and review them if they cause hardship.
» TAKE ACTION NOW: Fill out the short debt form
Changing the Terms of Your Repayments
If HMRC is collecting directly, ask its payment-enquiries team to review the arrangement. If DWP is collecting, ask DWP. Neither department is required to accept every proposed change. See related guidance.
You can ask them to change:
- The amount of money you pay in each instalment
- The duration for which you’ll need to keep making payments
- The way in which you pay the debt back
If you’re not comfortable with the terms of HMRC, it’s definitely worthwhile to contact them and attempt to change them.
Do not assume larger payments save interest: most tax-credit overpayments do not carry interest. Keep essential living costs and other priority commitments affordable, and confirm how additional payments will reduce the balance.
If repayments leave too little for essentials, contact the department recovering the debt and explain your budget, health needs and other relevant circumstances.
Ask whether payments can be reduced or spread over longer. There are no continuing tax-credit payments to reduce; current recovery may instead be through DWP deductions or direct payments.
If you’re paying through direct recovery, you can call and ask HMRC to lower or raise your repayments for your tax credit debt.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
It’s a good idea to assess your finances and calculate how much you can afford to spare each month to contribute towards your overpayment.
Prepare a complete income-and-expenditure budget, allowing for essential costs, priority bills and reasonable contingencies. Do not assume every pound left after a narrow list of bills is affordable for repayment.
Include all debts and repayments in the budget, but distinguish essential living costs and priority liabilities from unsecured credit repayments. A free debt adviser can help assess an affordable offer.
Also, note that you can also contact HMRC if you’d like to repay the overpayment with a single payment.
Do not ignore notices. HMRC can use several recovery methods, but a missed letter does not itself authorise an unrestricted bailiff entry. Obtain advice on the specific notice and any enforcement deadline.
HMRC has direct-recovery powers for eligible established debts, subject to conditions, protected balances, notice and challenge safeguards. It is not an automatic right to empty an account once a debt crosses a threshold. Seek urgent advice if you receive a direct-recovery notice.





