


Debt Assigned to a CAIS Member: What It Means


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
“Debt assigned to a CAIS member” is a credit-report description relating to an account transferred to another member of Experian’s information-sharing scheme. It is not a court judgment or a separate debt.
Check the new account details and any assignment notice against your own records.
In this article, we’ll help you understand:
- What it means when your debt is assigned to a CAIS member.
- How to start dealing with this issue.
- If you can write off some of your debt.
- Why creditors sell debts.
- What the next steps are for you.
This guide explains the marker, the checks to make and how to ask for help.
Where to start
If you’ve received a letter about an outstanding debt claiming that your debt has been assigned to a CAIS member, you might be wondering what that means.
Debt Sold
In this credit-report context, the marker indicates that the lender sold the debt to another member of the information-sharing scheme.
The original creditor will record the status of your account as being ‘debt assigned’, which basically reflects that the debt has been assigned or sold, to another company.
Check who now owns the account and who is authorised to collect it before changing your payments.
Selling a debt transfers ownership; appointing an outside collector to act for the existing creditor does not necessarily do so.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
The original creditor may still be relevant to a complaint about its earlier conduct, lending or credit-file information. Ask which firm should handle each issue.
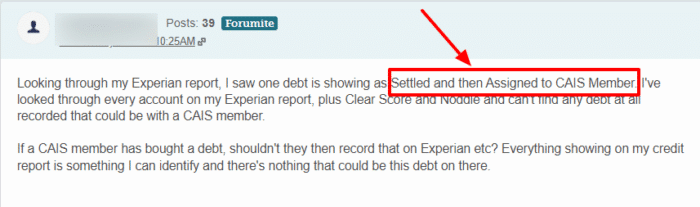
The seller may close its entry following a sale. This does not itself mean you have paid or that the balance was written off. Any purchaser entry should relate to the same debt and preserve the original default date where applicable.
But what does CAIS stand for?
Who Are They?
CAIS stands for Credit Account Information Sharing. It is Experian’s programme through which members share credit-account information.
This is the name given to the shared database of credit history that is maintained by Experian.
Experian is a UK credit reference agency. Lenders and other eligible organisations use credit-reference information alongside their own decision criteria.
Credit-data sharing requires a lawful basis and appropriate transparency, but consent is not the only possible basis. Check the organisation’s privacy notice and ask it or the credit reference agency to correct inaccurate data.
How to Deal with It
Start by checking the account details, creditor and balance. An assignment marker alone does not establish that every recorded amount is correct.
If contact is excessive, misleading or otherwise unfair, keep the evidence and complain to the relevant firm.
Complain to the firm first and keep copies and call logs. For an eligible regulated financial complaint, you can normally approach the Financial Ombudsman Service after a final response or after eight weeks without one, usually within six months of the final response. The Ombudsman can require a remedy or compensation; it does not impose regulatory fines. Tax, council and other non-credit debts may have different complaint routes.
Free debt advice is available from organisations such as Citizens Advice and StepChange. MoneyHelper is a public guidance service with a debt advice locator, not a debt charity. Free advice does not mean every debt solution is cost-free or that the debt will be cancelled.
Why do creditors assign/sell debts?
Creditors can transfer accounts for commercial reasons; a sale is not limited to forgotten or overdue debts.
Do not infer the reason for an individual sale from a general description. Ask for the account and assignment details.
The Consumer Credit Act is not the only law relevant to assignment, and default is not a universal prerequisite. Applicable rules depend on the account and jurisdiction.
Verify any notice and the new creditor’s payment instructions with independently obtained contact details.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Next steps
Now we have the basics down. We now know what debt assigned to CAIS member actually means. Let’s look at the next steps in dealing with the debt you owe.
Get advice if the account is disputed, old or unaffordable. There is no guarantee that every account can be resolved quickly.
Be active
Once you have found out you now have debt assigned to CAIS member, you’ll want to see what you can do to sort it out.
Explain any difficulty paying and propose a sustainable amount after essential costs. Ask for reasonable contact arrangements.
Gather information
Once you know your debt has been assigned to a CAIS member, you’ll want to go through all the correspondence you might have received from the original creditor and the new debt collection agency.
Double-check any of the amounts they say you owe, and make sure that they match.
Don’t ignore them
Ignoring a debt collection agency if you’ve had your debt assigned to CAIS member will not make them go away.
Respond to genuine legal notices within their deadlines. Contacting the firm does not guarantee that every call or letter will stop.
Prove the debt
If you’re uncertain as to whether you owe the amount they say you do, you can ask them to prove the debt using a ‘Prove the Debt’ letter.
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
Statute-barred status
A sale does not restart a limitation period merely because the owner changed.
For many unsecured debts in England and Wales, the usual limitation period is six years from the relevant cause of action, not simply the last phone call. A payment, qualifying written acknowledgement or court proceedings can affect the position. Scotland usually has a five-year prescription period for many ordinary debts, with different rules and exceptions. Court judgments, secured debts and some tax debts require separate advice. Get free debt advice before paying or acknowledging an old debt; do not ignore court papers.
An England and Wales limitation defence does not usually extinguish the debt, whereas Scottish prescription can do so. Ask an adviser to assess the particular account before paying or acknowledging it.
Pay them
If you are certain that the debt is yours, and it isn’t statute-barred, and you have the necessary funds to pay it, you should do exactly that.
Obtain written confirmation of the balance and the effect of payment or a settlement. Accurate historic credit entries may remain, and necessary account notices can still be sent.
If the debt is valid but unaffordable, ask about a sustainable arrangement. For regulated consumer-credit debts, firms must consider appropriate forbearance. Where a repayment arrangement is used as forbearance and you meet its terms, interest and charges must be reduced, waived or cancelled as needed so the balance does not grow during the arrangement.





