


How much debt can you have and still get a mortgage?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
There is no universal UK debt-to-income cutoff. Learn how existing commitments affect affordability and what to check before applying.
What Do Lenders Look At?
There are several factors affecting mortgage applications for people in debt which I’ll explain here.
Mortgage lenders’ criteria for loan approvals include:
- Looking at your credit history
- What your income is
- The level of your monthly expenditures
- The value of a property
- The amount you want to borrow
Can I borrow with debt?
The amount of money you can borrow depends on what you can afford. This is why mortgage lenders perform affordability assessments.
An affordability assessment would factor in the following:
- What your credit score is
- How many times you applied for a mortgage which involves a hard search
A hard credit search can be recorded when you apply. The credit report does not normally show a lender’s refusal as a separate entry, although repeated applications may affect later decisions.
Affordability assessments help mortgage providers get a better idea of what you can afford in monthly payments.
Plus, the importance of credit history in mortgage applications must be stressed.
Hence, they will only approve you for a mortgage if they think you’ll be able to comfortably afford it.
This means that if you have outstanding debts and most of your income is going towards paying them, then you may not be able to borrow a lot of money.
A good example is shown in the message posted by a person on a popular forum.
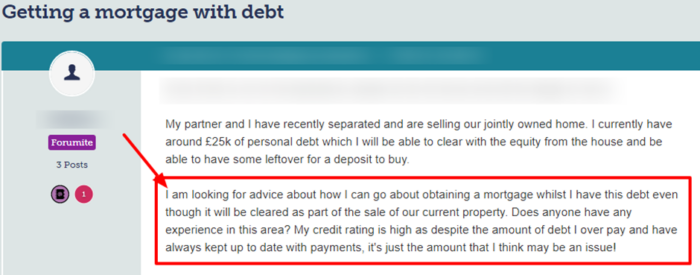
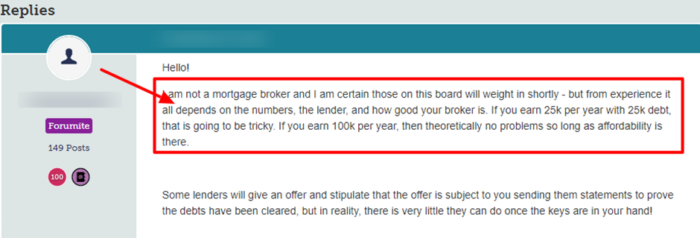
Source: Moneysavingexpert
What is My Debt-to-Income Ratio?
Understanding debt-to-income ratio helps you know whether a mortgage provider would consider your application.
Your debt-to-income (DTI) ratio is a financial measure which estimates what your debts are compared to how much you earn every month.
It’s what mortgage providers use when reviewing mortgage applications.
Lenders try and look for applicants with lower debt-to-income ratios because they believe they will be able to manage their monthly payments more effectively.
Please note that while your credit utilisation rate does affect your credit score, it does not affect your DTI ratio.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice. We may introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, which can provide information about debt solutions and your available options. Fees may be payable if you enter into a formal debt solution. MoneyNerd Limited may receive a referral fee. Entering into a debt solution may affect your credit rating. Free debt guidance is available from MoneyHelper at moneyhelper.org.uk.
Is a high ratio good or bad?
Large existing repayments can reduce what is affordable for a mortgage. The lender looks at the full circumstances rather than just a ratio. A guarantor or family-assisted mortgage is not a universal solution and can create risks for the person providing support. Get regulated advice before considering one.
This is a guidance tool only and not an assessment. For an accurate mortgage assessment, consult an online mortgage broker. Do not rely solely on this calculator’s results.
Is a low number good?
Lower existing commitments may leave more income for housing, but do not guarantee acceptance for a mortgage or any other credit. Lenders also consider the stability of income, essential spending, deposit and credit history.
How Do I Calculate It?
Calculating your DTI ratio is fairly simple. I’ve listed the steps to calculate your DTI ratio below.
First, you must add up any debt payments that you make every month. It includes student loans, credit card loans, child support, and car loans.
Second, you must add up your gross monthly income. It includes not only your salary but any other form of income you have such as investments or rented properties.
Keep in mind that you should NOT subtract any taxes or other deductions from your monthly income when calculating your DTI ratio.
Then, all you have to do is divide your total debt payments with your total monthly income.
Here’s an example for you:
Suppose that you pay £400 each month towards your car loan and £400 towards your credit card debt. Then, your total debt payments would be:
£400 + £400 = £800.
Now, suppose that your gross monthly income is £4000. Then, your DTI ratio would be 20% (800/4000 = 0.2).
Keep in mind that the DTI ratio is typically expressed as a percentage.
What do Lenders Consider to be a Good Number?
UK lenders use their own affordability assessments. There is no universal 36% debt-to-income rule, 28% mortgage-payment limit or absolute 43% rejection threshold. Income, spending, dependants, deposit, existing commitments, credit history and product criteria all matter.
A ratio can help describe a budget, but it is not a mortgage offer. Provide accurate documents and ask a regulated mortgage adviser to assess the options before making repeated applications.
» TAKE ACTION NOW: Fill out the short debt form
The role of a broker
A mortgage broker advises on and arranges products from the lenders within its scope. The broker is not necessarily the lender, and using one does not automatically mean a higher interest rate. Ask about lender coverage, fees, commission and authorisation before choosing advice.
What can I Do to Lower It?
I just discussed how to calculate your DTI ratio above. Now, I’ll cover the various techniques to reduce your DTI ratio.
Using that information, you can see that there are mainly two ways to lower your DTI ratio:
- By Lowering debts for better DTI ratio.
- Explore ways to increase gross monthly income.
Reducing your debts can go a long way in lowering your DTI but that’s easier said than done.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Is it a good idea to transfer credit card balances?
A balance transfer moves debt; it does not itself reduce the principal owed. It may reduce interest if you qualify for suitable terms, but fees, the promotional period and the later rate matter. Taking new credit can also affect a mortgage application. Check the total cost and get advice before making changes solely to improve a ratio.
Curb your spending to reduce debt
You can also opt to reduce your living costs by assessing your spending habits and eliminating any unnecessary costs.
You should consider your needs versus your wants and try to hold off on your wants until you can get your finances in order.
After a few months of practising financial discipline, you may find that you have extra money. You can then use this money to take care of your debts and thus, lower your DTI ratio.
To increase the amount of money you earn every month, you could opt for any of the following:
- Get a second job or try freelancing.
- Work overtime at your main job.
- Ask your employer for a pay rise.
- Learn a skill or complete a course which will enable you to secure a job at a higher salary.
Can I get help with debt?
Yes, you can get debt help in the UK by contacting a leading charity or a debt management company.
Several major UK charities that provide debt advice. Alternatively, debt management companies provide debt management assistance in the UK.
It’s worth noting that charities provide free debt advice, whereas you’d have to pay if you approach a debt management company.
For more information and advice on how to lower your DTI ratio, you can contact an independent charity such as StepChange or Payplan.
References





