


How to Dispute an Incorrect Debt in the UK


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
If a debt, balance or creditor’s right to collect appears wrong, ask for an explanation and evidence promptly. The correct dispute process depends on the debt and UK jurisdiction; this guide is not a fixed eligibility test.
In this guide, we’ll help you understand:
- What it means to dispute a debt.
- When and how you can dispute a debt.
- The role of different agencies in debt disputes.
- Possible outcomes of a debt dispute.
- Steps to take if you’re struggling with unaffordable debt.
Keep statements, agreements and notices. A complaint or evidence request does not replace a response to court papers or extend a court deadline.
Let’s start your journey to resolving your debt issue today.
When Can You Dispute a Debt?
You can raise a genuine concern about a debt without first satisfying a fixed list of seven criteria. Identify exactly what you dispute and why.
Possible issues include mistaken identity, an incorrect balance, payments not credited, the creditor’s authority, unfair conduct or a legal defence. See related guidance.
Check what you previously agreed or acknowledged, because it may affect the evidence or a limitation defence.
Previous payments or an earlier repayment plan do not automatically prevent you from disputing an error or other valid issue. For old debts, obtain advice before making a new payment or written acknowledgment.
If the creditor claims more than you believe is due, compare the itemised balance with the agreement, statements and payment records.
You may find proof that the actual amount owed is less than what your creditor is charging you. If so, you can take the issue up with them.
Lastly, if you’re looking to dispute a debt because a debt collector called you and asked for the money, don’t immediately assume that you don’t owe the debt.
Ask whether the firm owns the debt or collects on behalf of the creditor, and request evidence of the balance and its authority. Debt collection does not always involve a sale. See related guidance.
A free debt adviser can help assess your options. StepChange is a charity; PayPlan is a commercial debt-advice provider offering free debt advice. A referral form is not a substitute for meeting a legal deadline. See related guidance, debt enquiry form.
Issues that may justify a dispute
The examples below are reasons to investigate, not automatic cancellation rules. The remedy depends on the law, agreement, evidence and jurisdiction.
Understanding your rights in debt disputes is essential.
Explain the particular error or legal issue and ask for relevant documents. Seek advice if court proceedings, a secured asset or an old debt are involved.
Examples to check include:
- If you were underage when you signed the agreement
Age and legal capacity at the time of the agreement can matter, but the rules differ within the UK and by type of contract. See related guidance.
Do not assume every agreement made under 18 is automatically void or becomes valid merely because an adult co-signed. For example, Scotland has different capacity rules, and guarantees and some contracts can have separate effects.
Give an adviser the agreement, your age when it was made and any guarantor details so the correct rules can be checked.
- If you didn’t sign an agreement at all
If you did not agree to the borrowing, or believe someone impersonated you, tell the creditor and ask for evidence. Lack of a handwritten signature alone does not establish that no debt exists.
Many agreements can be made electronically, and some liabilities arise by law rather than a signed credit contract. Consumer Credit Act document requirements apply only where relevant.
Missing documents can affect enforceability for some regulated agreements, but do not automatically cancel every debt. Ask for advice on the specific document request and consequences.
- If you were pressured/coerced into signing the agreement
The corporate world can be very tricky to navigate.
You could have to deal with sales representatives and business managers who lead you to believe they’re doing you a service.
If you think that your arrangement was unfair because representatives coerced you or pressured you to agree to the deal, you could potentially use this as a reason to dispute the debts.
- If you didn’t understand the credit agreement
Misleading explanations, unfair pressure or lack of capacity may provide grounds for a complaint or legal challenge. Simply saying that you did not understand an otherwise valid agreement does not automatically remove liability.
The law states that creditors/lenders have a responsibility to provide clear data and information on what they’re signing you up for, and the nature and specifics of the agreement.
Provide evidence of what you were told and why it was misleading. Remedies can depend on consumer-credit, contract and consumer-protection rules.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
- If your name isn’t on the agreement
A debt addressed to the wrong person should be challenged. However, a spelling error, name change or missing label does not automatically remove liability, and joint borrowers or guarantors may have obligations under separate documents.
Ask the creditor to show why it believes you are liable. If court papers arrive, obtain advice and respond through the court process as well as raising the dispute.
- If what you’re being asked for doesn’t match the agreed conditions
Check the agreed balance, lawful interest, fees and any recoverable court costs. Not every amount beyond the initial borrowing is unlawful, but unexplained or incorrect additions should be challenged.
Ask for a calculation and identify the terms or charges you dispute without assuming every disagreement proves fraud.
Many regulated consumer-credit agreements have a 14-day withdrawal right, subject to exclusions and the statutory start date. Withdrawing normally requires repayment of the credit and accrued interest within 30 days; it does not make money already borrowed free. See related guidance.
Other contracts have different cancellation rules. Check the agreement and act within the relevant deadline.
- If the credit agreement has incomplete or incorrect information
Regulated credit agreements have legal information and form requirements. The effect of an omission or error depends on the agreement, the applicable law and the defect; it does not automatically cancel every debt.
If you find clearly incorrect information, or if there’s some missing information on the credit agreement, you may be eligible to dispute the loan.
Case study: debt collector chasing wrong person
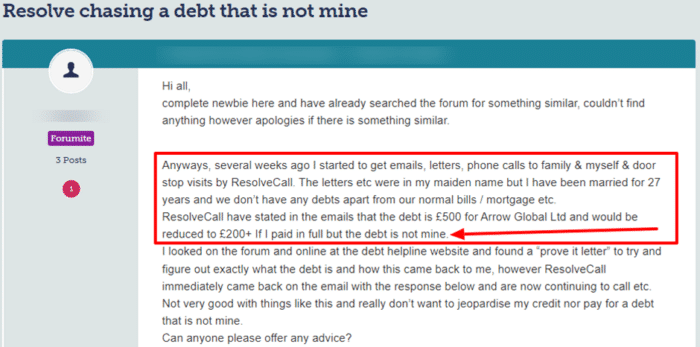
Source: Moneysavingexpert
My Creditor Sold Off the Debt… Is this Disputable?
Selling debts usually isn’t an issue where a dispute can be made.
In short, disputing sold off debts is possible and the good news is that your rights remain the same regardless of whether your creditor sold your loan off to a debt collector or not.
If you don’t recognise the loan and you think you don’t owe them money, you can choose to dispute it.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How To Dispute a Collection That Has Been Sold
Creditors can often assign a debt without the debtor’s consent, subject to the agreement and legal requirements. Ask for the assignment and payment details if you are unsure who is entitled to collect.
A valid assignment is not itself a defence to payment, but errors in identity, balance, authority or enforcement can still be disputed.
However, challenging sold off collections is possible if the debt is not yours, or its amount is incorrect.
For example, if you do not recognise the debt, or you believe that the balance is too high, you can write a debt dispute letter to the agency.
Does filing a dispute hurt your credit?
Raising a dispute is not itself the same as missing a payment or receiving a default. However, credit reporting on the underlying account may continue while a dispute is investigated. See related guidance.
Corrections to credit-file information can affect a score in different ways. A complaint does not guarantee removal of accurate information.
If information is inaccurate, raise the issue with both the creditor and credit-reference agency. Obtain advice before stopping payments on an account you otherwise accept.
» TAKE ACTION NOW: Fill out the short debt form
Writing a Letter
A debt dispute letter is a letter that you can send to a debt collection agency to have them prove you owe money they claim you owe.
Writing an effective debt dispute letter is important because it shows you’re serious.
For debts covered by FCA consumer-credit rules, a firm must suspend recovery while investigating a dispute raised on valid grounds or grounds that may be valid. This is not a universal freeze on all debts, and it does not remove court response deadlines.
What To Write To Dispute a Debt
You should ask the collection agency to provide evidence of your liability for the alleged debt.
If the firm cannot substantiate its claim, ask it to explain the outcome and correct any inaccurate records. Failure to answer a letter does not by itself legally write off the balance.
I’ve listed the key elements of a debt dispute letter here:
- You must state the reference number they assigned to your case
- You should also attach a copy of any letter the collection agency has sent to you
- For an eligible financial-services complaint, first complain to the firm. You can normally refer it to the Financial Ombudsman Service after a final response or eight weeks without one, usually within six months of the final response. The FCA does not decide individual debt disputes, and not every creditor or type of complaint falls within the Ombudsman’s jurisdiction.
Possible outcomes
If there are any changes made following a debt dispute, you may find it helps your credit score.
An upheld dispute can lead to a corrected balance or credit record, but score improvements are not guaranteed. Losing a dispute does not itself create a separate credit penalty; the underlying account information matters. See related guidance.





