


CARS Debt Collection: Checking a Debt and Your Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you surprised by a letter from CARS Debt (Creditlink Account Recovery Solutions)? You might be wondering where this debt has come from or if you need to pay it.
This guide explains how to check a CARS demand, respond to a dispute and seek help with unaffordable payments.
Keep correspondence and account records so that advice or a complaint can be based on the facts.
In this article, we’ll explain:
- Who CARS Debt Collection is
- What to do if you get a scary letter from them
- If you can ignore a letter from CARS Debt
- How to request reasonable contact and complain about conduct.
- If CARS Debt will come to your home
We’ll also show you ways you might be able to write off some of the money you owe. Plus, we’ll tell you where to go for free debt advice.
Let’s dive in.
Intimidating CARS Debt Collection Letters
You will learn about your Cars Debt Collection debt through one of their letters.
A demand should identify the alleged debt and any genuine possible next step. Check it before paying; an evidence request is not a trick that guarantees delay or cancellation.
» TAKE ACTION NOW: Fill out the short debt form
Ask Creditlink to Prove the Debt!
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
Asking for proof of your debt has never been easier, thanks to the letter template available at MoneyNerd.
Use a template to explain a genuine dispute and request relevant documents. It does not guarantee that the debt will be written off. See related guidance.
Sometimes companies make errors and try to chase debts that have already been paid. This can be very frustrating!
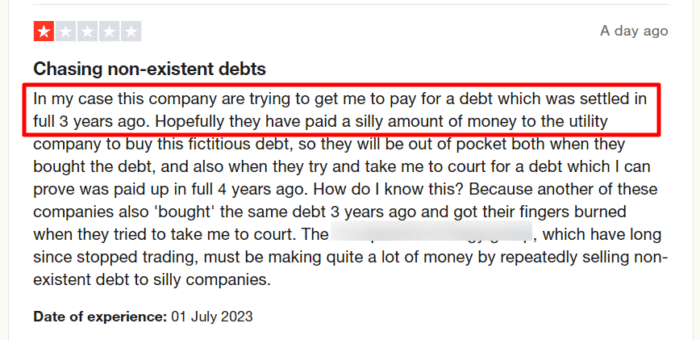
This also shows why it is so important to keep up to date with your records!
If you have had a letter from a debt collection agency that you know you have already paid, you still need to reply and let the company know. You can provide copies of letters confirming that your debt has been settled to help make the process quicker.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Can You Ignore a Debt Collection Letter?
You should not ignore a letter.
Lots of debtors ignore Cars Debt Collection because they think it is a scam or because they don’t have the money to pay. This is not a smart move because Cars Debt Collection can take the debt to court if they are willing.
However, we don’t recommend that you ignore debt collectors.
What Happens If You Ignore It?
If you know that you have debts, you need to do something about them.
You should not just ignore them and hope that they will go away – they won’t!
If you do not engage with CARS and refuse to pay them the debt that they can prove you owe, you may end up being taken to court.
A creditor may issue a claim and only the court can enter a CCJ, including by default. Pay or respond according to the court order; the one-month credit-register rule is not a universal extra month to start instalments.
A CCJ normally stays on the register and credit file for six years from judgment. Paying the full judgment within one calendar month can allow the entry to be removed; paying later normally marks it satisfied rather than removing it. The debt does not automatically expire when the entry disappears.
Removal of the register or credit-file entry after its normal retention period does not cancel the judgment debt.
If you pay all of your debt off within a month, you can write to the courts and ask for your CCJ to be removed from the Register of Judgements, Orders and Fines.
If you still ignore CARS and make no effort to pay them anything, they may go back to court.
Taking control of goods needs a further lawful warrant or writ. Enforcement agents must follow the relevant notice, entry, ownership and exemption rules; they do not have unrestricted access to a home.
Explain any financial difficulty and ask for affordable support. A payment holiday or interest freeze may be agreed, but is not guaranteed and should be confirmed in writing.
You could also consider a debt solution.
If you ever feel like you need some help, you can talk to a debt charity. We have linked some at the bottom of this page. Their advisers will be able to look at your finances and tell you how to move forward.
A national or historic debt statistic does not establish your liability or determine the appropriate response to your account.
Learn About Possible Debt Solutions
If the balance is valid, consider affordable repayment and any suitable debt solution with a free adviser. Limitation is only one factor affecting recovery.
If you can’t afford to pay off the debt in one go, you may be able to negotiate with them and agree on a new repayment structure. Just make sure that you don’t agree to a payment schedule that you can’t afford.
We also recommend getting any new agreement in writing from CARS before you make your first payment. This will make sure that your records are up to date and make it more difficult for CARS to argue about your payments in the future!
But sometimes that’s still not enough, and you may need to look into a debt solution.
There are several debt relief options available in the UK, so it’s a good idea to get some advice before you commit to a solution. We have linked some charities at the end of the page that offer free financial advice and debt counselling services.
How Can You Stop Creditlink Calls and Texts?
Get in touch. As well as scary debt letters, Cars Debt Collection could continue to keep in touch and apply pressure by calling you. But this might not be one call per week, it could be daily or more than once each day.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Cars Debt Collection is not allowed to harass you for payment.
Ask for a reasonable contact method and explain any vulnerability. The firm should consider your circumstances, but a preference or debt solution does not automatically prevent every necessary legal notice or communication. See related guidance.
Individual Voluntary Arrangement (IVA) or Scottish alternatives
An IVA is formal insolvency managed by an insolvency practitioner. An approved proposal binds the debts and creditors covered by it, with fees, payments and any asset terms set out.
Suitability depends on debts, available income or assets, costs and creditor approval. There is no universal minimum balance or requirement for more than one creditor.
Many IVAs involve five or six years of payments, but terms vary and qualifying debt is normally released only on successful completion. They affect credit records and may involve assets. Scotland has different options, including protected trust deeds, DAS and sequestration; a trust deed is not compulsory. See related guidance.
Debt Relief Order (DRO)
In England and Wales, DRO eligibility includes a £50,000 qualifying-debt limit and detailed income, asset, vehicle and residence conditions. An approved debt adviser checks eligibility and submits the application.
During a DRO, included qualifying debts are protected from most recovery action under the moratorium rules. This is not a ban on every necessary communication, and excluded debts and ongoing bills still need attention.
A DRO normally lasts 12 months. If it remains in force, included qualifying debts are normally discharged at the end. Report relevant changes and keep paying ongoing bills and excluded debts.
Bankruptcy or Sequestration
Bankruptcy – or sequestration in Scotland – may be your final resort if you have no realistic possibility of paying back your debts.
Bankruptcy does have a negative image, but it can let you write off some of your debts and get a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
An approved Scottish money adviser can assess eligibility for the Minimal Asset Process (MAP), a form of sequestration, and compare other suitable options. Eligibility and consequences must be checked; it is not automatically the best choice for everyone with a low income. See related guidance.
Know Your Rights
CARS acting as an ordinary collector cannot force entry or seize goods. Bailiff enforcement requires separate authority, so identify the stage of the process before applying bailiff guidance.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Can You Complain About CARS?
If you think that CARS have acted inappropriately, you can make a complaint.
You can also complain if you think that they have not kept to the Financial Conduct Authority’s (FCA) guidelines.
First, complain to CARS directly so that they have the opportunity to sort out the issue themselves. But if you feel that they have not taken your complaint seriously or dealt with it properly, you can escalate matters.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
CARS (Creditlink Account Recovery Solutions) Contact Information
| Website: | https://www.carsuk.org/ |
| Post: | C.A.R.S. PO Box 6520, Basingstoke, Hampshire RG21 4UY |
| Phone: | 01256 512500. Check the official website for current payment and support options. |
| Opening hours: | Monday and Thursday 8:30am–6pm; Tuesday and Wednesday 8:30am–5pm; Friday 8:30am–4pm; Saturday 8:30am–12:30pm; Sunday closed. |
| Email: | [email protected] |
References





