Average Car Debt in the UK


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
If you’re wondering about the average car debt in the UK, this article is here to help.
Car finance payments can be quite stressful, but don’t worry! You’re not alone. Each month, over 170,000 people visit our website looking for guidance on debt solutions.
In this easy-to-understand guide, we’ll cover:
- The current average car debt in the UK
- Information on loans for new and used cars
- The impact of missing car payments on your credit score and legal standing
- Where to find professional advice for car debt
- Frequently asked questions about car debt
It’s common to feel unsure about seeking help when dealing with car debt. In fact, Citizens Advice revealed that 60% of adults facing financial difficulties hesitate to seek assistance.1
But rest assured, we’re here to help you.
UK Statistics
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
Debt Solutions Comparison
Dealing with car debt and missed payments can be scary. But don’t worry, there are different debt solutions available that can help you.
These are:
| Option | How it works | Key limits and risks |
|---|---|---|
| Debt management plan | Informal repayment of eligible non-priority debts through an affordable budget. | Creditors need not agree, freeze interest or stop court action. Fees apply with some providers; free providers exist. |
| IVA | Formal agreement covering eligible debts and accepted through the creditor voting process. | Fees, credit effects, asset/equity terms and failure risks apply. Payments and term depend on the agreed proposal. |
| DRO (England and Wales) | Normally 12 months of protection before qualifying debts are discharged if the order remains in force. | Current qualifying-debt limit £50,000; strict income, asset, vehicle and residence conditions. Homeowners are not eligible. Application is through an approved adviser to the Insolvency Service, not a court. |
| Bankruptcy (England and Wales) | Formal insolvency that can discharge qualifying debts. | Assets and employment may be affected. Discharge is usually after 12 months, but income payments may continue for up to 3 years. |
| Consolidation loan | New borrowing to repay selected existing debts. | Does not write off debt. Fees or a longer term can increase the total paid; secured borrowing puts your home at risk. |
| Agreed payment break or reduced payments | A temporary arrangement negotiated with the creditor. | Interest may continue, credit reporting can be affected, and the debt remains. Terms require agreement. |
| Informal negotiation | Ask creditors for affordable payments or a settlement. | Acceptance is not guaranteed; record terms in writing. Priority bills still need separate attention. |
| Equity release | Eligible homeowners may access property value through a lifetime mortgage or home reversion. | Reduces the estate and may affect benefits or care funding. Requires specialist advice and comparison of alternatives. |
Loans for New Cars
Currently, almost £17.5 billion is borrowed every year to pay for new cars in the UK.
Some people don’t even view car debt as debt in the traditional sense.
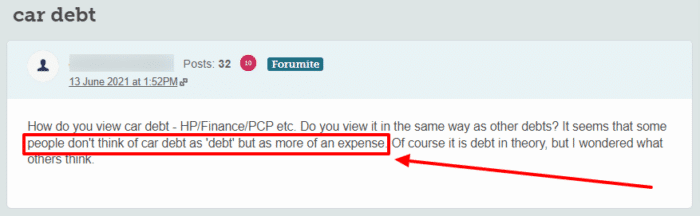
Car debt is still debt so it is important to keep up with your repayments. If you don’t, you can end up with serious elgal issues to deal with.
This can also have a negative impact on your credit score.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Loans for Used Cars
From 2009 until 2022, the average amount of money borrowed to buy a new car increased from £11,964 to £25,039.
Are there legal repercussions for missing payments?
If you realise that you can’t afford to pay your car finance anymore, you should tell the car finance company.
In some situations, you might be able to negotiate an alternative payment plan.
You may even be able to voluntarily surrender your car, depending on the type of contract that you have. If you are unsure, you can read your contract or contact your car finance company to find out.
If you do nothing, you run the risk of your car being repossessed.
You will get a reminder after you miss the first payment.
You may get a second reminder if you miss another payment or you can be sent a notice of arrears. This arrears notice will tell you how much you owe and when you need to pay it.
If you do nothing and stay in arrears, your car finance company can send a default notice which will give you 14 days to pay off all the debt in full. If you don’t pay off the balance, your car agreement can be ended and your car repossessed.
The car finance company has the legal right to repossess your car if you don’t pay them back.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
References