How to compare home improvement loans


Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Are you hoping to improve your home with a loan but feeling unsure about the costs and choices? This is the perfect guide for you. It answers all your pressing questions about home improvement loans in the UK.
So, don't worry, you're not alone.
In this guide, we’ll be covering:
- The ideal type of loan for home improvements
- Tips to compare quotes and get the best deal
- The difference between loans that are secured and those that are not
- Important points to think about before you take a loan
- How to use a home improvement loan calculator
We understand that loans can be hard to understand. That’s why this guide is simple and easy. So, let’s get started and find out how a home improvement loan could work for you.
What type of loan is best?
Home improvements don’t come cheap. From new furniture to paying for contractors, the cost of enhancing your property comes at a cost that many cannot afford upfront. That’s why there are many options to access credit to pay for home improvements, not least a home improvement loan. These loans are specifically offered so homeowners can pay to improve their home.
There are other loans and ways of funding home improvements too, which we outline at the end of this guide. Make sure you stick around for those!
Rates explained
For a regulated consumer-credit promotion using a representative APR, that rate or lower must be expected to apply to at least 51% of credit agreements entered into as a result of the promotion. It is not a promise to 51% of everyone who applies, and the rule should not be applied indiscriminately to mortgage APRC illustrations.
A calculator estimates payments using its stated amount, rate and term. It is not a lending offer, eligibility confirmation or suitability assessment. Compare the personalised terms and total cost before applying.
Advertised rates can differ by amount and term. Check the actual rate for the sum you need rather than borrowing more merely to reach a pricing band.
Your personal offer may differ from an advertised representative rate. The 51% rule does not mean exactly 49% of all applicants receive a different rate.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. A lower monthly payment may mean paying more overall, and secured borrowing puts your home at risk if repayments are not maintained.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
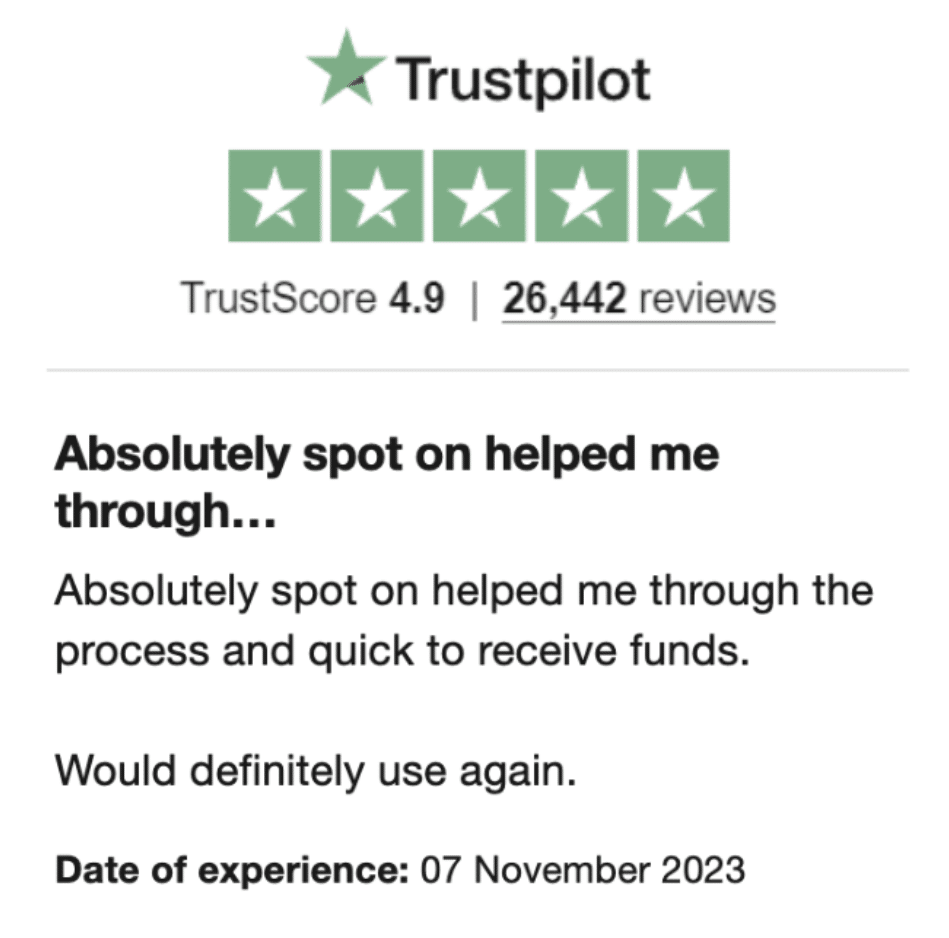
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
What are the lowest rates?
Rates and eligibility change and depend on the product and your circumstances. Obtain a current personalised quotation or mortgage illustration and compare the total cost, fees, rate type and repayment terms; figures in this article are not live offers.
The best place to get one
Compare current offers from eligible lenders and, if useful, brokers with clear panel and fee disclosures. There is no substantiated current cheapest-provider ranking here.
Examples
These historic provider names are not a verified current ranking or product panel. Check current availability, the firm’s FCA permissions and whether it is a lender or broker before relying on an offer.
- Nationwide
Verify this provider’s current name, product availability, eligibility and personalised terms. The historic rate, amount and repayment-period figures are not retained as current offers.
- Post Office
Verify this provider’s current name, product availability, eligibility and personalised terms. The historic rate, amount and repayment-period figures are not retained as current offers.
- MBNA
Verify this provider’s current name, product availability, eligibility and personalised terms. The historic rate, amount and repayment-period figures are not retained as current offers.
- Tesco
Verify this provider’s current name, product availability, eligibility and personalised terms. The historic rate, amount and repayment-period figures are not retained as current offers.
- M&S Bank
Verify this provider’s current name, product availability, eligibility and personalised terms. The historic rate, amount and repayment-period figures are not retained as current offers.
- Virgin Money
Verify this provider’s current name, product availability, eligibility and personalised terms. The historic rate, amount and repayment-period figures are not retained as current offers.
- Sainsbury Bank
Verify this provider’s current name, product availability, eligibility and personalised terms. The historic rate, amount and repayment-period figures are not retained as current offers.
- Hitachi Personal Finance
Verify this provider’s current name, product availability, eligibility and personalised terms. The historic rate, amount and repayment-period figures are not retained as current offers.
- NatWest
Verify this provider’s current name, product availability, eligibility and personalised terms. The historic rate, amount and repayment-period figures are not retained as current offers.
Interest-free loans
Interest-free options may sometimes include qualifying council schemes, retailer finance or promotional credit cards. Availability, fees, deferred-interest terms and eligibility vary; check the total cost and conditions.
A 0% purchase card can be useful only if the limit, permitted payments and repayment plan fit. Minimum payments still apply and interest may start after the offer or a breach; it does not guarantee a credit-score improvement.
However, there will be limitations to doing so and you are not likely to fund large-scale renovations with one of these cards and then repay within the 0% period. You would still need to make minimum monthly payments on the capital borrowed.
What things should I consider?
When considering a home improvement loan, the first thing to consider is if you want to look for secured or unsecured loans.
Using a secured option may enable you to access more credit (if required) and it may help you get a lower interest rate. However, with a secured loan you are putting assets at risk and you could even lose your home. It will be a personal decision whether you feel comfortable doing so, as unforeseen circumstances – such as injury or illness – could affect your income.
Compare interest with all fees, repayment term, total amount payable and the consequences of default.
We’ve explained how these rates are advertised between lenders below. Read on!
Enquire about a secured loan through Loans Warehouse, a credit broker, not a lender. Approval and terms depend on checks. Compare the full cost before applying. MoneyNerd may receive a referral fee. Your home may be repossessed if you do not keep up repayments on a loan secured against it.