


County Court bailiff fees: court charges and enforcement costs


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
County Court bailiffs are court employees. Their court fee rules differ from the staged fees charged by private certificated enforcement agents and High Court enforcement agents.
This guide concerns England and Wales. It explains the main distinction and how to check the charges on your case:
- Learn what a County Court Judgement (CCJ) is and how it works.
- Find out about the role of a bailiff in enforcing a CCJ.
- How court fees differ from private enforcement fees.
- Explore ways to potentially write off some of your debt.
- Understand your rights and options if you’re struggling with unaffordable debt.
Our team knows the worry that comes with dealing with bailiff companies. We’ve been there, and we understand your situation. We’re ready to provide the information and support you need to navigate this.
Let’s start this journey together and find the best way forward for you.
How much do they charge?
1. Application for a warrant of control
2. Further court enforcement
3. Removing and selling goods
Miscellaneous costs
» TAKE ACTION NOW: Fill out the short debt form
Do I have to pay it?
If you dispute a charge, challenge it promptly and ask an adviser about the appropriate complaint or court application. Do not assume a complaint suspends the warrant or that every amount demanded must be accepted as correct.
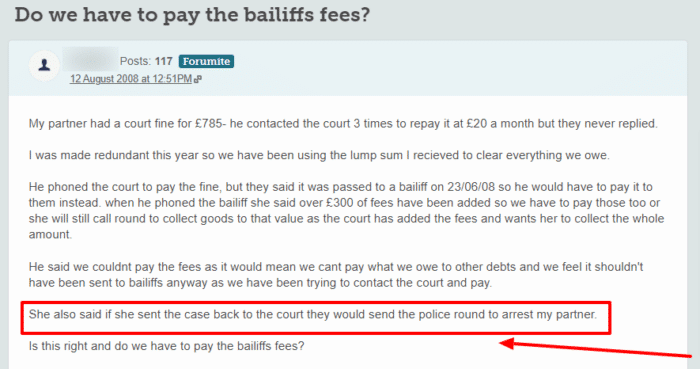
A warrant of control for an ordinary civil debt does not authorise arrest merely because you cannot pay. Separate court orders and other enforcement powers have different rules.
Can I claim back the charges?
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Are their fees regulated?
Different fee rules apply to court-employed bailiffs, private non-High Court enforcement and High Court enforcement. The private stage-fee schedule changed on 1 May 2026; court application fees must be checked separately.
The current warrant-of-control issue fee is listed in HMCTS EX50. Check the type of officer and each charge against the applicable schedule rather than assuming all bailiffs have the same fees. See related guidance.
It is rare, but sometimes bailiffs can charge the wrong amount. This is why it is essential that you check your bill and collect receipts for anything that you pay.
Are there ways to avoid them?
Free debt advice can help you assess repayment options and formal protections. An informal plan or enquiry about a debt solution does not itself stop an existing warrant.
There are several different debt solutions available in the UK, so I recommend speaking to a debt charity as soon as possible. Their advisors will be able to look at your finances in detail and help you work out which debt solution will work best for you.
I have linked a few charities that offer these advisory services for free below.
Debt Management Plan (DMP)
A DMP is an informal arrangement for eligible non-priority debts. Creditors do not have to accept it, freeze interest or stop enforcement; a County Court warrant needs specific attention.
Because it is informal, it is not legally binding so you are not tied into a DMP for a minimum number of payments.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency arrangement with creditors. It can include agreed payments or other contributions and binds creditors covered by the arrangement once approved. Fees, effects on assets and credit, and the risk of failure need to be considered with an authorised insolvency practitioner.
An IVA can write off the unpaid balance of included debts on successful completion, subject to its terms. Excluded debts remain payable, and failure can leave you liable for remaining debt and further action.
There is no universal statutory requirement to owe several thousand pounds or have more than one creditor. Suitability depends on the debts, available income or assets, alternatives and the provider’s criteria.
Trust Deed
Scotland has different debt remedies, including protected trust deeds, the Debt Arrangement Scheme and bankruptcy. A trust deed is one option, not a compulsory replacement for an IVA; ask a Scottish debt adviser which options fit your situation. See related guidance.
A protected trust deed is a formal Scottish insolvency arrangement with conditions, costs and risks to assets and credit. Protection and discharge depend on its status and successful completion; it does not automatically cover every debt or prevent every type of contact.
Debt Relief Order (DRO)
In England and Wales, a Debt Relief Order may be available if qualifying debts are no more than £50,000, spare monthly income is no more than £75, assets are no more than £2,000 and any qualifying vehicle is worth no more than £4,000. Other conditions apply, including not owning your home. An approved adviser must assess eligibility. See related guidance.
A DRO normally gives 12 months of protection for the debts included in it. Ongoing bills and excluded debts still need to be paid. Follow your adviser’s guidance, especially where rent arrears or eviction are involved.
Included debts are normally discharged at the end of the DRO period if the order remains in force. Changes in circumstances must be reported and can affect the order; excluded debts are not written off.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is the Scottish version of bankruptcy.
Scotland has its own bankruptcy and Minimal Asset Process eligibility rules. Ask a Scottish debt adviser about the available options rather than assuming England and Wales bailiff rules apply. See related guidance.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
What do I do if the bill is wrong?
For a County Court bailiff, contact the court promptly about an incorrect bill. If a private firm is actually involved, contact that firm and the creditor and check the separate fee regime. See related guidance.
You can use my free letter template to help you write the letter. I recommend writing rather than phoning because there will be physical evidence for you to rely on if you need to take the dispute further.
Ask the body responsible for the charge to correct it and refund any overpayment where appropriate. Keep receipts and copies of the response.
Possible reasons for complaint include:
- The wrong fee regime or percentage calculation has been used.
- A court or enforcement fee has been charged at the wrong amount.
- You have been charged for something that the bailiffs didn’t do
- The bailiffs haven’t given you receipts for their disbursement costs, and you think they’re wrong
- A charge is claimed for action that was not legally authorised.
If the issue is not resolved, obtain advice on the appropriate court application or complaints escalation route and its costs.
If you are considering any type of court action, you need to seek legal advice immediately. The debt charities that I have linked below will be able to guide you on your best next steps.
Does the bailiff’s salary affect the fees?





