Prioritise essential bills, compare debt options and understand why old debts are not automatically written off.
What happens if you can’t pay a debt?
The consequences depend on the type of debt and jurisdiction. Mortgage or other secured arrears can put the secured asset at risk through the applicable process. Unsecured creditors may use collection or court action. Enforcement requires the relevant legal authority, even where the procedure does not involve an ordinary County Court claim.
Contact the creditor and get free advice promptly. Do not ignore a notice or assume all debts follow the same route. Prioritise housing, essential living costs and other priority bills.
How can I get out of debt?
You can get out of debt by using get-out-of-debt strategies and debt mitigation techniques that you can implement yourself without having to negotiate with creditors or companies.
Alternatively, if you have already gotten into arrears on your debt, you might be able to use one of many debt solutions. Some debt solutions are informal agreements with creditors, whereas others are legally-binding debt solutions that must be set up and overseen by an insolvency practitioner.
When trying to get out of arrears, some debts need to be paid off before others. These are known as priority debts and include things like mortgage payments, council tax and court fines.
There is also a way you might be able to get out of debt without paying by using the law. We’ll return to this towards the end of this guide.
» TAKE ACTION NOW: Fill out the short debt form
Repayment strategies and consolidation
Consolidation repays old borrowing using a new loan or credit facility. It may simplify payments, but a lower monthly payment can cost more overall if the term is longer. Compare fees, rates, term and total repayment. Securing previously unsecured debt against a home creates repossession risk. Get free advice before committing.
Use a debt solution
A DRO has strict eligibility conditions and covers qualifying debts, not every liability. In England and Wales the debt limit is £50,000, with limits of £75 monthly spare income, £2,000 assets and normally £4,000 for a vehicle. Homeowners are not eligible and applications are free through an approved adviser. Northern Ireland has separate rules.
The usual 12-month period restricts recovery of included debts; successful completion releases qualifying balances. It does not stop every contact or excuse current bills. Misconduct can lead to extended restrictions or revocation; a restrictions order is not simply an extension of the waiting period for automatic write-off.
A DMP is an informal repayment arrangement and does not guarantee an interest freeze or prevent court action. An IVA is a formal insolvency agreement supervised by an insolvency practitioner, with fees and consequences for credit and assets. Its terms control payments and duration. Under the 2025 protocol, standard IVAs generally use 60 months, or 72 months where the relevant home-equity condition applies, instead of the former standard remortgage clause. Existing and non-protocol arrangements can differ. Only covered qualifying balances are released on successful completion.
How a debt solution could help
Some debt solutions can:
- Stop nasty calls from creditors
- Freeze interest and charges
- Reduce your monthly payments
A few debt solutions can even result in writing off some of your debt.
Here’s an example:
Situation
| Monthly income | £2,504 |
| Monthly expenses | £2,345 |
| Total debt | £32,049 |
Monthly debt repayments
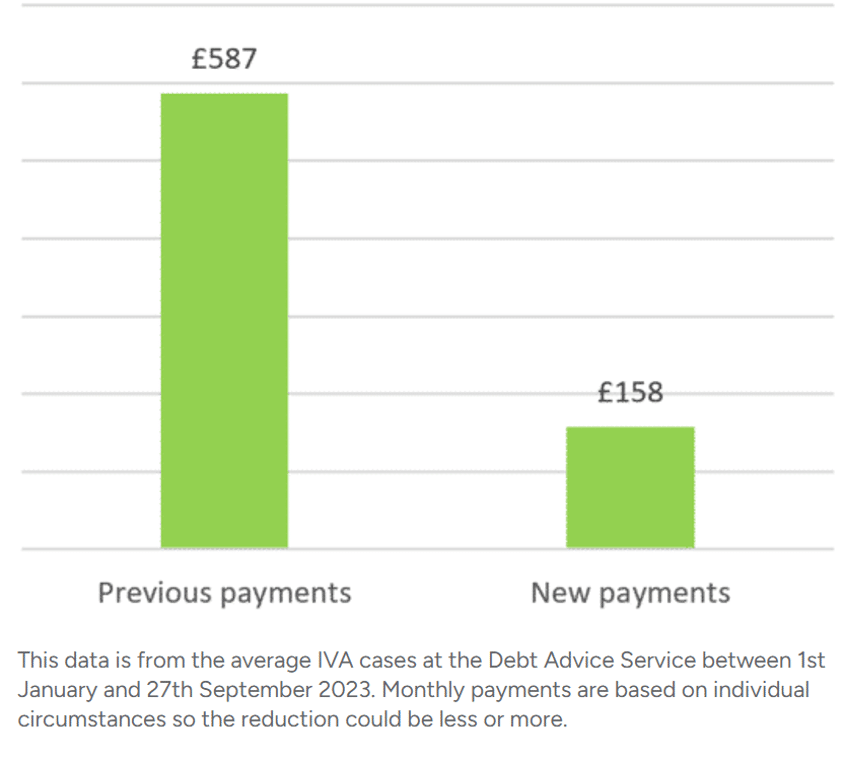
| Before | £587 |
| After | £158 |
£429 reduction in monthly payments
If you want to learn what debt solutions are available to you, click the button below to get started.
How do I clear debt quickly?
Debt consolidation, the snowball method and the debt avalanche method can all be used to clear your debts more efficiently. Simply making overpayments on the debt will also clear debt quicker, but be aware of overpayment or early repayment charges.
What’s the best way to get out of debt?
The best way to get out of debt is entirely dependent on your situation, including your disposable monthly income and the nature of your debts.
You can get help figuring out what debt mitigation strategy or debt solution is most advantageous for you by speaking with a debt charity. Debt charities offer free personalised debt advice and can even help organise some of the solutions listed above.
How to clear your debts (step by step)
There are four main steps to clearing your debts after recognising that you need to take action. We have outlined these four key steps below.
#1: Work out your budget
Work out your monthly finances first. Your monthly budget should contain all essential expenses, such as rent, mortgage payments, groceries, household bills, transport costs and debt repayments.
If you’re unsure how much something costs, such as groceries, check back over your bank statements for a better estimate. Take the overall cost away from your total monthly income to uncover how much disposable income you have each month.
#2: Speak to a debt charity
Now is the best time to get free debt advice from a debt charity. A debt charity will help you pick the right debt strategy or solution, but to do this they need to have a clear picture of your finances. This is why it’s important to work out your monthly budget before speaking with the charity’s debt advisor.
#3: Choose a debt strategy or debt solution
The debt charity will assess your situation and recommend one or multiple debt strategies or solutions. They should provide all information on how each of them works, including their pros and cons.
Debt charities can usually help you negotiate and set up debt solutions with creditors, or you may need to consider commercial services from a debt management company.
#4: Stick to your plan or solution
Once you have chosen a debt strategy or solution, it’s important to stick to it and see it through to get out of debt. There can be serious consequences if you don’t stick to formal debt solutions as these are legally binding. You could even be made bankrupt in some cases.
How can I get out of debt with no money?
Free advice can identify suitable options when there is no spare income, including whether you qualify for a DRO or another formal solution. No solution is automatic, and eligibility, costs and consequences differ across the UK. A DRO does not cover every unsecured debt or ban all creditor contact.
Thousands have already tackled their debt
Every day our partners, The Debt Advice Service, help people find out whether they can lower their repayments and finally tackle or write off some of their debt.

Natasha
I’d recommend this firm to anyone struggling with debt – my mind has been put to rest, all is getting sorted.
Reviews shown are for The Debt Advice Service.
Is it better to pay off debt or save money?
It’s usually better to pay off your debts faster through overpayments rather than put the money into a savings account. This is because the interest added to debts is usually higher than the interest rates on savings accounts.
Additionally, clearing your debts can improve your credit score and reduce the risk of getting into arrears later, which could lead to a court order and enforcement action.
Does being in debt affect my credit score?
Debt can have a positive or negative effect on your credit rating depending on how you’re handling your debt. If you’ve taken out credit and are repaying as agreed, you’re showing responsible borrowing and this could improve your score.
On the contrary, if you’re failing to repay debts as agreed or have a high credit utilisation ratio on your credit card, you could be worsening your credit file.
How can I clear my debt without paying?
Limitation is not a general debt-write-off strategy. In England and Wales, many contractual claims have a six-year limitation period, but the start date, payments, relevant acknowledgments and court proceedings matter. The debt is not automatically erased. Scotland has different prescription rules that can extinguish qualifying obligations; Northern Ireland has its own legislation.
Existing judgments and some types of debt follow different rules. Do not ignore court papers or wait in the hope that a debt will disappear. Ask a qualified adviser to check the facts before paying or acknowledging a potentially time-barred debt.
What does it really mean to be debt-free?
Being free from debt means you don’t owe any money to a creditor or organisation, this includes any overdrafts you have with your bank.
Even people who don’t use payday loans and credit cards usually have debt through their mortgage or student loans.