Debt Management Plan DMP

Debt Management Plan Living Expenses: Building a Realistic Budget

Scott Nelson MoneyNerd Janine Marsh MoneyNerd
By
Scott
Scott Nelson MoneyNerd

Scott Nelson

Debt Expert

Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

Learn more about Scott
&
Janine
Janine Marsh MoneyNerd

Janine Marsh

Financial Expert

Janine contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations.

Learn more about Janine
· Oct 4th, 2026
Get debt advice from The Debt Advice Service

Total amount of debt?

MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.

If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Debt Management Plan

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.

Are you thinking about a Debt Management Plan (DMP)? Wondering how much you’re allowed to spend on basics like food and bills?

Keep a clear record of your debts, income and essential costs. Free independent debt advice can help you compare the options available where you live.

This guide will help you understand:

  • What you can spend money on during a DMP.
  • How to create a budget for your essential living costs.
  • Whether you could write off some debt.
  • The guidelines set by DMP providers for monthly spending.
  • What happens if you spend more than the suggested amount.

You might feel worried about having enough money left after making DMP payments, and may be uncertain about seeking help.

You can ask for free debt advice before deciding on a DMP. Include all essential costs and any disability or caring needs in your budget.

Could you legally write off some debt?

MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.

Answer a few questions to start your enquiry. Options available depend on your circumstances.

How much debt do you have?

MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.

If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

Do DMP providers set monthly expenditure guidelines?

DMP providers commonly use a recognised budgeting framework, such as the Standard Financial Statement, alongside your actual circumstances.

Spending guidelines help assess whether figures are reasonable; they are not a universal legal allowance or an automatic ceiling on every household’s costs. See related guidance.

The amount of money varies depending on the number of family members that you have in your household. 

Also, the guidelines may vary depending on the debt management company.

Check the provider’s relevant FCA permissions or applicable legal status, fees and complaints process. Free DMP providers are available. See related guidance.

Budget figures should reflect your household rather than relying on undated fixed amounts. Consider:

  • The actual costs of a person living alone, including irregular bills
  • The shared and individual costs of a couple or other adults in the household
  • Children’s needs, including food, school costs, clothing and care

Include reasonable work meals, school meals, transport and any specific health or disability costs rather than assuming they fit a standard figure.

Ask your adviser to explain the budgeting guidance used and discuss any higher costs supported by your circumstances.

» TAKE ACTION NOW: Fill out the short debt form

What am I Allowed to Spend Money on During a DMP?

You need to note that a debt management plan involves paying reduced payments towards your debts using your surplus income.

DMP surplus income calculation is defined as the income that remains after paying your monthly essential expenses.

Your essential expenses would include everything you need such as groceries, bills, and fuel. Plus any payments towards priority debts that are not included in your DMP. 

The payment offer is based on what remains after a realistic budget for essentials, priority debts and reasonable allowances. Do not commit money needed for predictable or irregular household costs.

Creditors can ask about the budget, but regulated firms must consider individual circumstances and sustainable forbearance. For regulated consumer credit, firms must treat customers in or approaching arrears with forbearance. Where an agreed forbearance repayment arrangement is being met, further interest and charges must be reduced, waived or cancelled as necessary to prevent the debt balance rising during that arrangement. This is not an automatic cancellation of all existing interest or charges. See related guidance.

A DMP does not impose a legal ban on every discretionary purchase. The important issue is whether the budget and offered payments are realistic and sustainable.

Discuss reasonable personal spending and a contingency allowance with the adviser as part of the household budget. Repeatedly borrowing to meet essential costs is a sign the plan needs review.

If you set your living expenses lower than they actually are, you’re going to have trouble maintaining your household.

If you set them higher than they are, then you’re going to have trouble getting your creditors to accept the payment offer for your DMP. 

Case study

See this message one concerned person posted on a popular online forum about their situation.
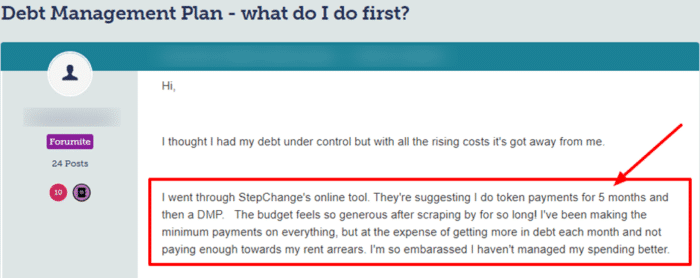
Source: Moneysavingexpert

Understand your debt options

MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.

The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.

Get started

MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

Don’t worry, it happens.

Some households reasonably spend more than a general guideline because of health, caring, location or other needs.

If actual costs are higher, explain why and provide evidence where reasonably requested. A guideline is not proof that necessary spending is excessive.

For example, a child may have special dietary requirements. Or you may have a high electricity bill due to an appliance needed to run your household properly. 

Use accurate figures supported by your circumstances. Do not inflate expenses, but do not omit genuine needs to make an offer appear affordable.

If costs rise or income falls, contact the provider promptly to review the budget and payments before the problem worsens. See related guidance.

Explaining higher necessary costs may support an affordable proposal, but it does not guarantee that every creditor will accept it. The adviser can help negotiate and consider alternatives.

Make sure you never set it lower than you need because if your budget is lower than what they are, you’re going to end up spending more than what’s listed in the DMP. 

It will affect your monthly payments and it could jeopardise the success of your DMP.

Your creditors could grow unsatisfied and reject it altogether. 

Take the first step towards tackling your debt

Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.

MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha

Very helpful and informative thank you

Get started

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.

For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.

Consequences of abandoning a DMP

You must contact your DMP provider and ask to cancel the plan. The provider informs your creditors the agreement has been cancelled.

In short, you would have to deal with your creditors yourself.

DMP cancellation consequences could leave you worse off.

However, before going down this route, you may need to ask yourself the following:

  • How do you intend repaying your debts once the DMP is cancelled?
  • Will you receive a refund for the fees you paid?
  • Will there be a cancellation fee?
  • Did the DMP provider mislead you? Therefore, you want to cancel the agreement

Should I review my Debt Management Plan regularly?

There are several advantages to regularly reviewing a DMP. Plus, you can review your plan online.

I’ve listed the benefits of regular DMP reviews here:

  • You can review your budget to make sure it’s still feasible
  • You get to check the progress of your DMP and how much longer it lasts

I suggest that you review your plan regularly or every 12 months. Sooner if your circumstances change.

Another option is to contact one of the leading UK charities that provide free debt advice. Their help, advice and support could prove invaluable when you need it the most.

Examples of free debt-advice services and money-guidance organisations include:

Could you legally write off some debt?

MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.

Answer a few questions to start your enquiry. Options available depend on your circumstances.

How much debt do you have?

MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.

If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

References

  1. StepChange – Credit safety net report
Did you like this article?
Show your support ❤️
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
We are so sorry...

Is there something missing? We’re all ears and eager to improve. Send us a message and let us know how we can make our article more useful for you.

You can email us directly at [email protected] to share your feedback.

The authors
Scott Nelson MoneyNerd
Author
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
Janine Marsh MoneyNerd
Debt Expert
Janine contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations.