How Bankruptcy Can Affect Your Spouse or Partner


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you worried about your debt and thinking about bankruptcy? You’ve come to the right place. Every month, over 170,000 people visit our website seeking advice on sorting out their debts.
In this article, we’ll cover:
- What bankruptcy is
- How bankruptcy works
- The effect of your bankruptcy on your wife
- How bankruptcy might change your shared and sole assets
- Ways to reduce your debt.
It’s common to feel unsure about seeking help when dealing with debt. In fact, Citizens Advice revealed that 60% of adults facing financial difficulties hesitate to seek assistance.1
But you’re not alone. We understand your worries and are here to explain bankruptcy in simple terms.
What happens next after bankruptcy?
This is a common question asked by people considering applying to be made bankrupt. And it’s a common question among the partners of debtors considering bankruptcy.
Just like Tigger asked here:
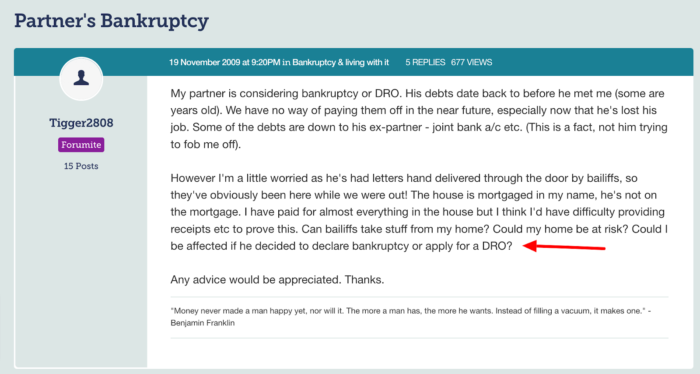
Source: https://forums.moneysavingexpert.com/discussion/2091595/partners-bankruptcy
Bankruptcy can affect a spouse or partner through joint debts, shared assets, household finances or a financial association on your credit files. This guide covers England and Wales.
Your spouse or partner does not become personally responsible for your sole debts just because you are married. Your own assets and your interest in jointly or solely owned property may be affected.
How does bankruptcy affect joint assets?
If you declare bankruptcy, your wife or husband can be asked to buy your share of the asset for its market value.
This is usually the case for property If this isn’t possible, a court order might be granted to force the sale of the asset.
Your partner keeps the share that legally belongs to them after secured borrowing and relevant sale costs. That share is not automatically half; beneficial ownership may need to be established.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
How will it affect sole assets?
Your assets as the bankrupt person will be subject to bankruptcy proceedings. They’re likely to be sold.
However, any sole assets owned by your wife or husband will be theirs to keep and won’t be forcibly sold.
But there is an important exception to this rule which often affects couples…
A home in your partner’s name may be affected if you have a beneficial interest in it. Marriage or living there does not automatically establish that interest; ownership, contributions and intentions need to be assessed.
Contributing to the purchase, mortgage or improvements can be relevant, but does not automatically establish a particular share. Get legal advice if ownership is disputed.
There might be things you can do to prevent the sale in this situation. Speak with Citizens Advice for information.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
How will it affect joint debts?
If you declare bankruptcy and have joint debts with anyone else, the other person is still responsible for the whole debt.
This is because both individuals on a joint debt take full responsibility for the whole debt, technically known as “joint and several liability”.
For example, you might have taken out a joint loan with your wife in the past. If this loan hasn’t been repaid when you declare bankruptcy, your wife will still be obligated to pay back the whole amount – not just 50% of the loan.
If your partner disputes being liable, for example because a credit agreement was made without their consent, they should get advice and raise the dispute with the lender. Other defences may apply depending on the agreement and circumstances.
But on the other hand, you could face more serious consequences if you committed fraud during the credit application to make it a joint debt.
You might benefit from reading the pros and cons of bankruptcy.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Debt support at MoneyNerd
Debt information and support can be found in abundance on the debt info master guide. Check this out now to start your journey free from debt.
References