Disadvantages of Equity Release – What You Should Know


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
Are you eager to learn more about equity release? You've come to the right place for answers. This article aims to guide you through the key points you should know about equity release.
We understand that the process of equity release can seem daunting and confusing. It’s a big decision, and you may have many questions, which is why we’re here to help.
In this article, we will:
- Explain what equity release is and how it works.
- Discuss the potential risks and drawbacks, such as the chance of losing your home.
- Provide guidance on how to get a realistic quote.
- Explore whether equity release is a good idea for you.
- Talk about what happens after death if you have equity release.
The Centre for Ageing Better’s study reveals that a million homes in the UK need changes to be better fit for living comfortably, and a third of these homes have someone over 55.1 This is why knowing how equity release works and its disadvantages is crucial.
We have a deep understanding of your concerns and questions. So, sit back, relax, and let us guide you through the details of equity release.
Are there any cons of equity release?
The FCA reports that many lifetime mortgages work well for consumers, especially those who couldn’t afford traditional mortgages or borrowing.
However, some lifetime mortgages do not work out well for consumers, often because they weren’t informed enough before they applied.2
It’s also important to mention that both lifetime mortgages and reversion schemes have some disadvantages, such as the long-term cost of equity release, eye-watering early repayment charges, impact on state benefits, implications on inheritance, and more.
We discuss the main cons of equity release below.
» TAKE ACTION NOW: Fill out the short debt form
What are the disadvantages?
The main cons of equity release are:
- Overall cost
Illustration only: £65,000 at 6.4% interest compounded annually without repayments would grow to about £137,000 after 12 years, excluding fees. This assumed rate is not a live offer. Actual costs can reduce the inheritance left.
It’s also mandatory to get professional advice and legal services, which add to the total cost of the process.
- Early repayment charges
Early-repayment charges can be substantial, but schedules, charge-free allowances and exemptions vary. Obtain a current redemption illustration before repaying or switching.
- Losing means-tested state benefits
Accessing part of your home equity as a lump sum will instantly increase the amount of savings you hold.
This may affect your entitlement to some means-tested state benefits.
The State Pension is not means-tested, although amounts differ between people. Equity-release proceeds can affect means-tested benefits such as Pension Credit.
Universal Credit normally has an upper capital limit of £16,000, but disregards and other rules may apply. Pension Credit and Council Tax Reduction have different assessments; obtain benefits advice.
Equity Release Do’s and Dont’s
As we delve into the details of equity release, we know how important it is to have clear guidance. That’s why we’ve put together this table that outlines the do’s and don’ts of equity release.
If you want to learn more about equity release, including its advantages and disadvantages, be sure to read our specialized guide.
| Equity Release – DO… | Equity Release – DON’T… |
| DO Discuss your purpose, affordability, alternatives and future needs with a qualified equity-release adviser. Borrowing to repay debts or give money away can reduce your financial security. | DON’T proceed under pressure or without understanding estate, benefit, care-funding, interest and fee consequences. |
| DO Seek professional advice from professionals who specialize in equity release. | DON’T Rush into a decision. Take your time, you are in control on this. |
| DO Understand the difference between lifetime mortgages and home reversion plans – and which is best for you. | DON’T Use equity release without fully understanding the terms. |
| DO Check for flexibility – look for plans that let you be flexible, like making partial repayments. | DON’T Forget to look at alternative options for raising funds. |
Remember to take your time to fully understand the terms of equity release. This way, you’ll make the right choice for your needs.
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Equity release isn’t the only option out there!
While equity release can be a wonderful option for many homeowners trying to free up some cash, it’s not the only option out there. You could look into other options like:
- Downsizing
- Taking out a regular loan
- Tapping into pensions and savings
- Asking friends and family for some help
But, what are the advantages of equity release?
From my experience, the advantages of equity release from a member of the Equity Release Council are:
- A lifetime-mortgage advance is borrowed capital; regular payments may be optional or required depending on the plan.
- Voluntarily keep the debt lower with repayments if desired
- Different uses may be allowed, subject to provider rules and advice on tax, benefits and risk.
- For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
- Moving may be allowed if the new property meets the provider’s criteria; a partial repayment or charges can apply.
- A qualifying no-negative-equity guarantee limits repayment to net sale proceeds when its conditions are met; it does not prevent the loan balance exceeding the property value.
- Some products allow an agreed inheritance protection feature, subject to terms and a lower amount available to release.
- Some products offer downsizing protection or other early-repayment exemptions. Conditions and qualifying periods apply; this is not universal.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
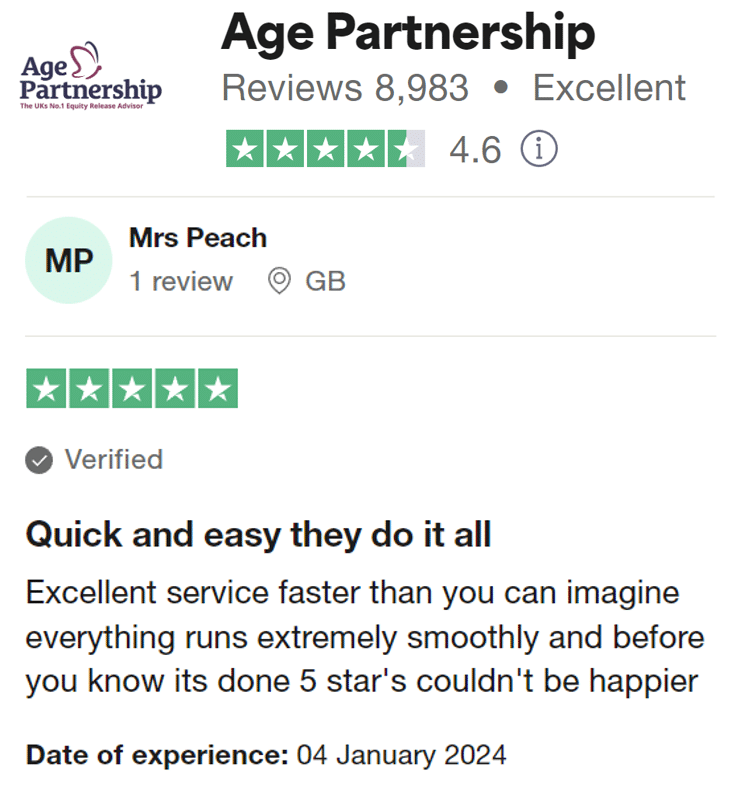
Reviews shown are for Age Partnership. Search powered by Age Partnership.
How to avoid the pitfalls of equity release
You can do five things to avoid the pitfalls of equity release. These are:
- Get independent advice from a financial services company that has experience working for clients in equity release.
- Tell your adviser about any future plans, such as plans to move home or downsize in the future.
- Only choose a lender that is regulated by the FCA.
- Only choose a lender that is a member of the ERC.
- Don’t rush into a decision and do your own research.
Is equity release a good or bad idea?
Equity release is neither a good nor bad idea for everyone.
The decision to use an equity release scheme should be based on personal circumstances. For some people with nobody to leave their estate to, it can be an easy decision, whereas, for others with children who could really benefit from inheriting a family home, it’s not such an easy decision.
If you’re thinking about equity release, make sure you use FCA-regulated lenders and seek independent financial advice for equity release.
Things to consider
Equity release includes lifetime mortgages and home reversion plans. A lifetime mortgage is a loan secured on your home; a home reversion plan sells part or all of the property. Equity release reduces what may be left in your estate and can affect means-tested benefits and future care funding. A lifetime mortgage is usually repaid when the last borrower dies or moves permanently into care, subject to the plan terms. Specialist financial and independent legal advice are needed. Any existing mortgage must normally be repaid from the proceeds or other funds. Age Partnership publishes an advice fee of £1,995 payable on completion; confirm the current fee in your personalised illustration. Lender and legal fees may also apply.
References