Renting With an IVA: Tenancy, Arrears and Referencing Checks


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you wondering if an IVA (Individual Voluntary Arrangement) would affect your chance of renting a property?
You’ve come to the right place. Each month, over 170,000 people visit our website looking for clear, helpful advice on debt solutions.
In this article, we’ll cover:
- The main facts about an IVA and its effect on renting a property.
- How an IVA might change your current rent agreement.
- How an IVA might impact your ability to rent a home in the future.
- Options for including rent arrears in your IVA.
From July to September 2023, the Gazette reported that there was a total of 13,965 Individual Voluntary Arrangements.1 This highlights just how many people are navigating similar financial challenges like yours.
Don’t worry, we understand what you’re going through, and we’re here to help you understand how an IVA can affect your chance of renting a property.
Will Entering into an IVA Affect My Current Rent Agreement?
An IVA does not automatically end a tenancy or prevent you from renting. The effect depends on the tenancy, rent payments, any arrears and the relevant housing law.
Read the agreement and obtain housing advice about any insolvency clause or threatened action. A clause does not by itself let a landlord bypass the lawful possession process.
A landlord is a creditor if rent arrears are included and may be notified on that basis. Even otherwise, an IVA appears on a public register and can be found through relevant checks, so secrecy cannot be guaranteed. The landlord’s property does not become your IVA asset.
Keep paying current rent and tell the supervisor if housing costs change.
This is because when you devise a payment plan with your Insolvency Practitioner (IP), they will consider the payment you have to make towards your monthly rent. This will be considered a part of your essential living expenses.
Rent arrears may be included in an IVA, but arrears on your current home can still put the tenancy at risk. Do not assume they can simply be paid separately without approval. Ask both the insolvency practitioner and a housing adviser how the arrears and any possession order will be handled.
IVA Breakdown
Understanding the basics of an Individual Voluntary Arrangement is essential for anyone navigating financial decisions.
Here’s a quick table that will help you better understand how an IVA works.
If you want to learn more about the pros and cons of IVA, be sure to read our specialized guide.
Is it Possible to Move to Another Rented Property While an IVA is in Place?
Moving to another rented property is possible when you have an IVA, but it can be more difficult as your options will be limited.
This is because an IVA is recorded in your credit file and, as a result, negatively impacts your credit rating.
If your potential landlord performs a credit check on you before approving you for the rented property, then mentioning the IVA in your credit record may make them apprehensive about approving your application.
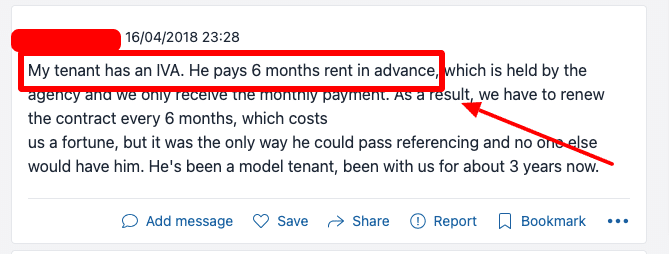
Tenancy law also matters. In England, most existing private assured shorthold tenancies became assured periodic tenancies on 1 May 2026; they do not require repeated fixed-term renewals.
Other jurisdictions and tenancy types have different rules. See the Renters’ Rights Act tenant guidance for England, and get local housing advice if you are uncertain about a proposed check or new agreement.
A joint application may be considered using both tenants’ circumstances, but it is not guaranteed to succeed and can make both tenants responsible for the rent.
Some landlords may consider a suitable guarantor, subject to their criteria and the terms of the guarantee.
A guarantor can become liable for unpaid rent and sometimes other obligations under the wording agreed. They should understand the amount, duration and scope before signing.
A guarantor may help an application, but it does not ensure acceptance or make an unaffordable rent sustainable.
It’s important to be honest and upfront with landlords and letting agents when you want to acquire a space to rent so that they can decide about IVA, arrears, and eviction risk.
Provide accurate information requested in the application and evidence of affordable rent, income and payment history. Do not promise payments that your budget cannot support.
Will an IVA affect My Ability to Rent a Home After it has Finished?
An IVA is normally recorded on your credit file for six years from approval and can remain longer if it is still ongoing.
Completing early does not usually remove it before six years. After completion, check that both the IVA entry and associated accounts are accurately updated.
As I said earlier, when you’re looking to rent a property, the landlord will likely perform a credit check on you.
A recorded IVA can affect an application, but landlords’ criteria differ. It does not mean every landlord will reject you.
Check your reports for errors and gather evidence of current affordability and rent payments. There is no universal six- or twelve-month waiting period before you may seek a tenancy.
Do not delay finding necessary or safer accommodation solely until an IVA entry disappears. Ask housing advisers or the council for help if you are at risk of homelessness.
Different landlords and housing providers use different checks. Explore realistic options promptly while agreeing any change in rent within your IVA budget.
Alternatives to IVAs when renting
There are alternatives to IVAs if you find yourself in a position where your debts become unmanageable. These include things like debt relief orders and even bankruptcy.
DROs, bankruptcy and informal arrangements have different eligibility criteria, risks and housing consequences. A poor credit history alone does not establish which solution is suitable; obtain debt and housing advice together where needed.
References