Equity release calculators: estimates, assumptions and personal details


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
This guide explains how an equity-release calculator can illustrate borrowing and interest costs. Check what information a tool requests and how any contact details will be used before submitting them.
It’s normal to feel confused about equity release, but don’t worry; we’re here to help. We can guide you on:
- What an equity release plan is.
- How calculator estimates differ from a personalised lending offer
- What percentage you can get on equity release.
- How interest on equity release is calculated.
- What happens after you release equity.
This guide explains how calculators work, what their estimates assume and why a personalised assessment is needed before proceeding.
In a nutshell
Eligibility depends on the product, age, property, credit circumstances and any required affordability assessment. Minimum property values and borrowing limits are lender-specific. An existing mortgage normally has to be cleared at completion, often using some of the released funds. Most standard lifetime mortgages start at age 55, but some payment-term lifetime mortgages are available from 50 and require interest payments for an agreed period. Home-reversion minimum ages and all other eligibility rules depend on the provider. Check the youngest applicant’s age and the actual product criteria.
A lifetime mortgage is a loan secured on your home; you retain ownership. Interest that is not paid is added to the balance. The loan is usually settled when the last borrower dies or moves permanently into care, subject to the contract. Required or optional repayments vary by product.
The lender’s repayment and enforcement rights depend on the contract. Sale is a common repayment route, but other available funds may be used.
The most common type of equity release plan in the UK is called a lifetime mortgage. However, there is another plan called a home reversion scheme. You can read about both in our How Does Equity Release Work? guide.
Understand the estimate before proceeding
An equity release calculator can give an estimate based on limited information. It is not an offer or a suitability assessment. Equity release reduces your estate and can affect benefits and future care funding. Compare alternatives and obtain specialist financial and independent legal advice before proceeding.
Alternatives
Compare downsizing, savings or other assets, benefits and grants, a standard mortgage or retirement interest-only mortgage where affordable, and other suitable borrowing. A specialist adviser should assess the alternatives; equity release is not the only option in later life.
Remortgaging is the process of moving your mortgage on your property from one lender to another. People often remortgage with the purpose of taking out a larger loan, releasing some of their home equity in the process.
Before remortgaging, you should ensure that you are able to repay a larger loan. To do so, you can use a remortgage equity release calculator. You should also make sure that you meet all of the eligibility criteria before applying.
What percentage can you get?
The maximum advance depends on age, property, product and current criteria. It is not a universal 20–60% of equity, and existing mortgages can often be cleared at completion.
Do not assume a lifetime mortgage will release 100% of the property value because prices are expected to rise. Future house-price growth is uncertain and is not a substitute for a provider’s actual lending limits.
Consider the costs and risks of equity release
Equity release is a long-term decision. A lifetime mortgage is secured against your home. Adding interest can substantially increase the debt and reduce your inheritance.
Consider fees, means-tested benefits, early repayment charges and future care needs. Alternatives include downsizing, other assets or a retirement interest-only mortgage where affordable.
Start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
Advertisement. MoneyNerd introduces enquiries to Age Partnership, which advises on lifetime mortgages, and may receive a referral fee.
Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply. Interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
What can affect the maximum percentage?
The percentage of equity you’re able to access with an equity release plan usually depends on the value of the property, its anticipated future value, and your age. The latter can be an important factor when the lender determines how much of your equity you can access.
Some providers consider health and lifestyle and may offer different terms. Enhanced underwriting does not guarantee a larger advance or establish that borrowing is suitable.
Can you be turned down?
Yes, you can be turned down for an equity release plan for many reasons, including if you don’t meet the lender’s age requirements or if the property is valued below a certain amount.
Certain aspects of a property can also result in an equity release rejection, including if the property’s roof is (partially) flat or if unauthorised building work has been carried out. Lenders will also assess whether the property is at risk of damage, such as from flooding.
What is the typical interest rate?
Rates change and depend on the product and your circumstances. Obtain a current personalised illustration and compare the APRC, fees, repayment options and total projected cost; this article does not quote a live market-leading rate. See related guidance.
A home reversion plan is a sale of part or all of your home, usually below open-market value, in return for money and the right to remain under the plan’s occupancy terms. It is not a loan. The provider receives its agreed share when the home is sold.
How is the interest calculated?
The amount of interest you’re charged on a lifetime mortgage is calculated based on the size of your loan, your age, and details about the property. You might be given a fixed interest rate or a variable one. But an important thing to note is that the interest is likely to be compounding.
So, what’s a compounded interest rate? In terms of borrowing, it is when the interest added to the debt each month is applied to the loan amount and any interest already accumulated. Because interest keeps making the debt grow, the next amount of interest is always more than the previous amount of interest added.
Therefore, compounded interest rates make the equity release debt grow quicker. But they are a good thing when applied to savings accounts because you earn interest on the interest paid to you as well.
What is the difference between pay monthly and interest roll-up options?
Rolled-up interest isn’t paid back each month, whereas pay monthly interest is repaid each month as the name suggests.
Many lifetime mortgages allow interest to roll up without regular payments, but some require interest payments for a set period. Optional repayments, limits and any early-repayment charges depend on the contract.
Paying interest can reduce balance growth, but required payments, fees and other terms matter. It does not guarantee a particular inheritance.
How do you calculate the cost?
To calculate the cost of an equity release plan you’ll need to know:
- Your loan amount
- The interest rate applied
- Assumed duration, fees, compounding and repayments. Future duration is uncertain, so compare several scenarios.
This is made easier with an equity release calculator.
About Age Partnership
Equity release is a long-term decision. Specialist advice is needed to assess suitability and compare the costs, risks and alternatives.
Advertisement. MoneyNerd introduces enquiries to Age Partnership, which advises on lifetime mortgages, and may receive a referral fee.
Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply. Interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Online calculator without personal data
A calculator gives an illustration based on stated assumptions. A borrowing-limit estimate and a compound-interest projection answer different questions. Neither is a lending offer, approval or suitability assessment; actual terms require a valuation, checks and specialist advice.
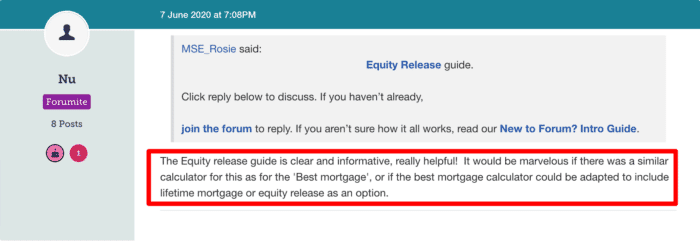
Source: https://forums.moneysavingexpert.com/discussion/comment/77261479#Comment_77261479
Read the calculator’s input fields and privacy information. An estimate that uses no contact details is still not a personalised quote or eligibility decision; a formal application requires personal information.
Is it a con?
If you read some of the equity release horror stories online, you can be forgiven for thinking that it’s all a con. It’s certainly true that repaying a lifetime mortgage that has been active for a long time is expensive, easily costing more than double the original loan.
FCA authorisation does not make every product suitable or risk-free. Check the firm’s identity and relevant permissions, and obtain qualified advice.
For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
Some people can really benefit from using a lifetime mortgage, but it’s essential to get professional equity release advice beforehand. In fact – it’s compulsory!
How to compare plans
You can compare different equity release plans by doing your own research or using lifetime mortgage comparison sites, such as the equity release supermarket. You could also speak with a loan broker who specialises in lifetime mortgages.
Things to consider
Equity release includes lifetime mortgages and home reversion plans. A lifetime mortgage is a loan secured on your home; a home reversion plan sells part or all of the property. Equity release reduces what may be left in your estate and can affect means-tested benefits and future care funding. A lifetime mortgage is usually repaid when the last borrower dies or moves permanently into care, subject to the plan terms. Specialist financial and independent legal advice are needed. Any existing mortgage must normally be repaid from the proceeds or other funds. Age Partnership publishes an advice fee of £1,995 payable on completion; confirm the current fee in your personalised illustration. Lender and legal fees may also apply.