Equity release examples: lifetime mortgages and home reversion


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
These illustrative examples explain how lifetime mortgages and home reversion plans work. They are not live offers or personal recommendations.
You can trust us to help you understand:
- What are equity release schemes?
- How to get a realistic quote.
- The role of the Equity Release Council.
- How much money you can get with equity release.
- Possible catches with equity release.
The following examples are fictional illustrations, not verified customer case studies.
Let’s dive in and learn more about equity release together.
How does it work?
Eligibility depends on the product, age, property, credit circumstances and any required affordability assessment. Minimum property values and borrowing limits are lender-specific. An existing mortgage normally has to be cleared at completion, often using some of the released funds. See related guidance.
A lifetime mortgage is a loan secured on your home; you retain ownership. Interest that is not paid is added to the balance. The loan is usually settled when the last borrower dies or moves permanently into care, subject to the contract. Required or optional repayments vary by product. A home reversion plan is a sale of part or all of your home, usually below open-market value, in return for money and the right to remain under the plan’s occupancy terms. It is not a loan. The provider receives its agreed share when the home is sold.
- From their estate after death
- When they move into long-term care
What are the schemes?
Most standard lifetime mortgages start at age 55, but some payment-term lifetime mortgages are available from 50 and require interest payments for an agreed period. Home-reversion minimum ages and all other eligibility rules depend on the provider. Check the youngest applicant’s age and the actual product criteria. Many lifetime mortgages allow interest to roll up without regular payments, but some require interest payments for a set period. Optional repayments, limits and any early-repayment charges depend on the contract.
The two main types are lifetime mortgages and home reversion plans. Enhanced lifetime mortgages are a variation of a lifetime mortgage.
- Lifetime mortgage
- Enhanced lifetime mortgage
- Home reversion plan
We provide equity release examples of these schemes later.
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
How much do you get?
An equity release product will not allow you to take all of your home equity out as a lump sum or drawdown. There are reasons why you cannot access all of the value of your home.
For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
Another reason is that the equity release plan provider is aiming to make a profit. If they allow you to take too much of your equity out then they restrict the amount of profit they can make when the negative equity guarantee is agreed upon.
» TAKE ACTION NOW: Find out how much equity you could release
What can I use it for?
Equity release is predominantly used by seniors to make retirement more comfortable. It could be used to pay for everyday expenses over a long period, fund at-home care services, or even be used to pay for memorable experiences, such as round-the-world cruises and trips. Sometimes equity release is used for home renovations, especially to make a property more accessible and safer in older age, such as installing stairlifts or new seated showers etc.
In other cases, the homeowners gift some of the money to family members to help them make their own property purchases or start a business. Be aware, any financial gifts over a set amount could be subject to inheritance tax if the (grand)parent dies within seven years.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
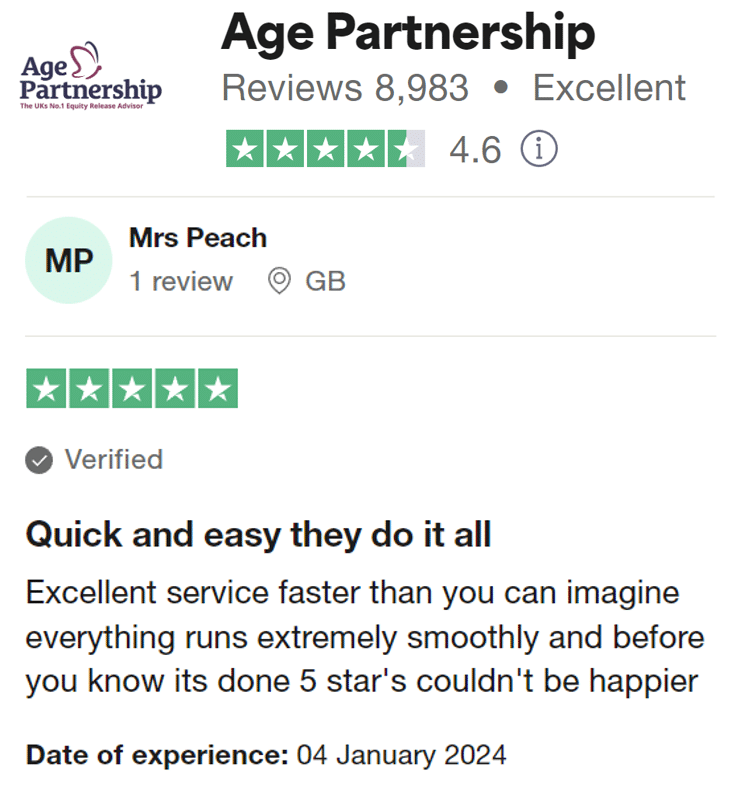
Reviews shown are for Age Partnership. Search powered by Age Partnership.
Some examples
The examples below cover a standard lifetime mortgage, an enhanced lifetime mortgage and a home reversion plan.
Lifetime mortgage
A lifetime mortgage is a loan secured on your home; you retain ownership. Interest that is not paid is added to the balance. The loan is usually settled when the last borrower dies or moves permanently into care, subject to the contract. Required or optional repayments vary by product.
Illustration only: borrowing £65,000 at 6.4% interest compounded annually with no repayments would produce a balance of about £137,000 after 12 years, excluding fees. This is an assumed rate, not a current offer.
If the property held its value at £130,000 and sold for this much, all of the money raised from the sale would be owed to the lifetime mortgage provider. But what happens to the remaining £7,000 of debt?
For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
Enhanced lifetime mortgage
Some providers consider health and lifestyle and may offer a larger advance or different pricing. Medical underwriting does not guarantee either result.
The amount offered depends on the product and underwriting. An enhanced plan is still a secured lifetime mortgage with costs, risks and eligibility conditions.
Home reversion scheme
A home reversion plan is a different legal arrangement from a lifetime mortgage; an enhanced lifetime mortgage remains a type of loan.
Fictional illustration: Jeff agrees to sell a 66% share of a home valued at £150,000 for £50,000 while retaining the right to occupy it under the plan’s terms. This illustrates a sale below market value, not a quoted offer or a loan.
Does it affect state benefits?
Releasing equity will instantly increase the amount of money you have in the bank, which could then affect your eligibility to receive some means-tested benefits. For example, you cannot lose your state pension, but you could lose some of your pension credits that top up your state pension, which could then mean losing council tax reductions.
Released money retained as savings can affect means-tested benefits. Universal Credit normally has an upper capital limit of £16,000, but disregards and deprivation-of-capital rules may apply; obtain benefits advice before acting.
Is there a better alternative?
Downsizing may release money without taking an equity-release product, but selling and moving have costs. Future debts, spending, care costs and tax can still affect what beneficiaries receive.
However, moving can be a stressful process that you might not want to deal with in later life.
Want more examples and discussions?
For more equity release examples and discussions, look no further than MoneyNerd. Our team has written lots of new guides and blogs all about releasing equity so you have the tools to assist your decision.