Equity Release to Help Children – Complete Guide


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
Are you keen to understand more about equity release? Perhaps you're wondering if it could help your child buy a house. Welcome to our complete guide!
In this article, we’ll answer your questions about:
- What equity release is and how it works.
- Getting a fair quote for equity release.
- The good and not-so-good points of equity release.
- How equity release money can be used.
- If you can give equity release money to your children.
We know that equity release can seem tricky. It’s a big decision with many things to think about. But don’t fret; we’re here to help. We understand your situation and have lots of useful advice to share.
So, let’s take a closer look at how equity release might help your children step onto the property ladder.
Stick with the Equity Release Council
The Equity Release Council (ERC) is a group that creates rules and guidelines within the equity release industry. These rules and guidelines are made to protect homeowners and offer them greater assurances.
Council membership can provide product standards and safeguards, but is voluntary and includes different professional categories. Check the adviser’s and provider’s FCA permissions and the solicitor’s relevant professional registration.
To give you an idea of why sticking with Equity Release Council members is usually better, here are some of their rules:
- For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
- Moving depends on the new property meeting the provider’s criteria; partial repayment or charges can apply.
- A qualifying no-negative-equity guarantee limits repayment to net sale proceeds when its conditions are met.
Can I give the loan to my children?
Some people use released funds to help family, including with a deposit or education. Whether to gift money depends on the homeowner’s own needs, risks and alternatives; it is not a measure of generosity. See related guidance.
Gifts may be permitted, subject to provider terms. Check the effect on your own finances, benefits, care funding and tax, and any recipient’s mortgage requirements.
While unfortunate, an equity release loan can also be used to buy out your spouse in the event of separation.
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Should I release equity to help them?
Releasing equity to help your children may not be financially beneficial in the long run because they would receive more from you if they waited to receive your inheritance. However, finances are not the only consideration. You may benefit from seeing your children access quality education and get a good career, or you may be happy and feel satisfied to help them buy their first home.
It is an entirely personal decision that should be backed up with the correct knowledge and guidance from an equity release professional.
The bank of mum and dad
The bank of mum and dad is no longer just a tongue in cheek phrase to describe a little financial support from parents. It is being heavily relied upon by younger generations, especially millennials who have now experienced the financial crash and the pandemic in their early working lives.
In fact, the latest research highlights how big the bank of mum and dad really is, especially when it comes to helping their children buy their first home. The Independent reports that 40% of first-time buyers are receiving some financial backing from their parents to complete their property purchase.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
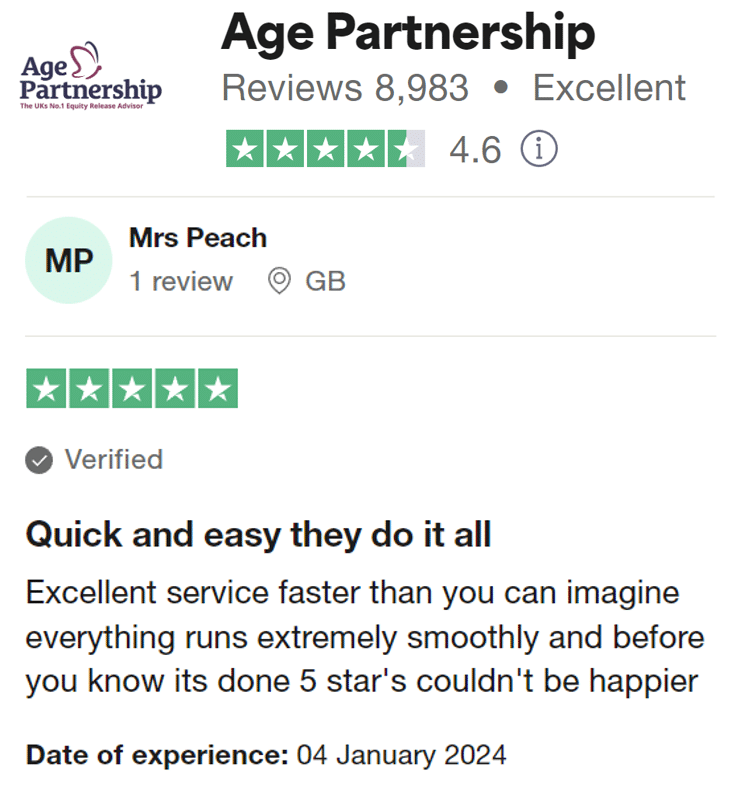
Reviews shown are for Age Partnership. Search powered by Age Partnership.
Can I use it to avoid inheritance tax?
Inheritance tax depends on the whole estate, gifts, exemptions and available allowances. The standard nil-rate band is £325,000, and an eligible estate can have a residence nil-rate band of up to £175,000, subject to conditions and tapering. Selling or downsizing does not automatically remove every residence allowance.
Many outright gifts to individuals fall outside inheritance tax after 7 years, but gifts within 7 years are not all automatically taxed: exemptions, allowances and other rules matter. Gifts with reservation and trusts need separate advice.
There are ways that equity release can mitigate inheritance tax, but these methods provide some risk and should be discussed with your financial adviser.
Can it be used to pay for school fees?
Another common reason that senior homeowners take out equity release is to help their children or grandchildren pay for school fees. This may include private schools or university tuition.
Borrowing to fund education has costs and reduces financial flexibility. Future career or income benefits are uncertain and should not be treated as a guaranteed return.
How can I help them get on the property ladder?
If you are part of the bank of mum and dad, you’re probably wondering how you can help your son or daughter get on the property ladder. Equity release is one option.
Sometimes equity release is avoided because it takes away from their children’s inheritance. But if you are giving the money to children who will benefit immediately, and you get to witness that benefit, then it is an even more attractive option.
A home equity release loan can also be used in situations of divorce or separation to provide the person leaving the house with an opportunity to purchase another property, thus reducing stress on the children involved.
Pros and Cons
The primary benefits of equity release are:
- Cash lump sum or drawdown
- A lifetime-mortgage advance is borrowed capital; later income, investments or gifts can have separate tax implications.
- Many lifetime mortgages allow interest to roll up without regular payments, but some require interest payments for a set period. Optional repayments, limits and any early-repayment charges depend on the contract.
- Occupancy rights and any rent obligations depend on the type of plan and contract.
Costs can substantially reduce an estate. Rolled-up interest, home-reversion sale terms and early-exit charges vary; request projections and compare alternatives.
Quick recap
Equity release can be used to help children with their own finances. There are scores of senior homeowners choosing equity release and giving some or all of the loan to their children to help them get on the property ladder, which is proving more difficult than ever. Other reasons that the money is given to children is to help fund private school fees and university, or to start a new business.
In rare situations, it may even help their children avoid inheritance tax, but this is not a straightforward issue and should be discussed with a financial adviser first.