Can a Grant Help Pay Off Loans? Support and Repayment Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you worried about a debt? Do you need to know about UK grants that can help? You’ve come to the right place. Every month, over 170,000 people use our website to find answers about debt, so you’re not alone.
In this article, we’ll help you understand:
- What to do if you have a debt problem.
- How payment holidays work.
- What student loans and loan forgiveness are.
- How to check eligibility and whether support must be repaid.
- The different types of help the government can offer.
We know how hard it is to deal with debt, as some of our team members have been in the same place as you. We know how it feels to worry about money, but there’s help out there.
There is no general government grant that pays off everyone’s personal loans. Charitable and local grants have specific rules and often cover essential costs rather than credit debts. Payment breaks, benefit advances and insolvency are different forms of help, not grants.
Payment Holidays
If you’re struggling with your debt repayments, you can write to your creditors and inform them of this.
Negotiating with creditors can yield great results as you might be able to get a payment holiday (also known as a payment break) for a few months. This is one of the debt relief options available to UK citizens.
A payment break would give you some breathing space to get your finances in order. Your creditor may agree to give you a payment holiday after looking at your personal circumstances.
In order to convince your creditors, you may need to provide evidence and/or documentation of your financial situation.
This can be in the form of a copy of your wage slips and bank account statements. Based on personal experience, enclosing a copy of your financial statement within your letter to your creditor(s) can play a huge role in convincing them to consider your payment break request.
If your creditor(s) are refusing to give you a payment break and there’s no other way you can manage your finances, it’s a good idea to get in touch with a debt charity and seek debt advice from them. National Debtline, StepChange Debt Charity, and Citizens Advice are great debt advice services to contact.
They have professionals who will assess your financial situation, after which they might be able to provide you with a personal debt management plan to deal with your debts.
Alternatively, they could also negotiate with your creditors on your behalf to get you a payment break.
What’s the Impact of Payment Break in the Long-Term?
An agreed payment break can offer temporary relief. Before accepting it, ask the creditor to explain the payment schedule, interest, fees and credit reporting in writing. Possible effects include:
- Monthly payments may rise afterwards or the repayment term may be extended, depending on the agreement.
- Interest or fees may continue unless the creditor agrees to freeze or reduce them. Regulated lenders must treat customers in payment difficulty with appropriate forbearance.
- The total cost can increase, especially if interest continues or repayment takes longer. Compare the agreed figures before deciding.
- A hardship arrangement or missed payments may be recorded on your credit file. Do not assume every agreed payment break is credit-neutral.
Student Loans and Forgiveness
For income-contingent student loans, repayments depend on your repayment plan and earnings. Older mortgage-style loans have a separate deferment application process.
The threshold differs depending on what style of student loan debt you have. If your course started before 1998, then you have an old-style student loan, also referred to as a mortgage-style loan. These types of loans are repayable over either a period of five years or a period of seven years if your course was longer than three years.
Most loans for courses starting from 1998 use income-contingent repayment. Deductions may be made through PAYE, Self Assessment or direct arrangements where required, including for borrowers overseas.
If you have an old-style loan, you can defer your student loan repayment if your annual income is below a certain threshold. You can contact your student loan provider to determine this threshold. This will be either Erudio Student Loans, Honours Student Loans or Thesis Servicing.
If you qualify to get your student loan debt repayment deferred, then you can contact your provider and ask them to do so.
It’s important for you to note that interest will keep being added even if you defer your payments. You won’t need to make any payments for 12 months once your repayments get deferred.
For new-style loans, repayments will only start getting deducted from your wages once your income goes above the appropriate threshold.
Student-loan cancellation dates depend on the repayment plan. Plan 2 and English or Welsh Postgraduate Loans normally end 30 years after the April repayments were first due; Plan 5 uses 40 years.
For other income-contingent plans, check when the first loan for the course was paid:
- Plan 1: first loans paid on or after 1 September 2006 are normally written off 25 years after the April repayments were first due. Earlier Plan 1 loans are normally written off at age 65.
- Plan 4: first loans paid on or after 1 August 2007 are normally written off 30 years after the April repayments were first due. Earlier Plan 4 loans use age 65 or that 30-year point, whichever comes first. Check your own plan and repayment compliance with the Student Loans Company.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Government Financial Help and Money
Hardship Payments
A Universal Credit hardship payment may be available if a sanction or fraud penalty leaves you unable to meet essential needs. It must normally be repaid through later benefit deductions. It is not a general grant for missed loan payments.
Other benefits have different hardship rules. Ask the office handling your claim or a benefits adviser about the support appropriate to your circumstances.
Check benefit entitlement before claiming Universal Credit. Moving from an existing benefit can affect the amount and protections you receive. The benefits being replaced have included:
- Housing Benefit for many working-age claimants, although separate claims continue in some circumstances
- Child Tax Credit, which ended on 5 April 2025
- Working Tax Credit, which ended on 5 April 2025
- Income Support
- Income-based Jobseeker’s Allowance
- Income-related Employment and Support Allowance
If you receive a Migration Notice, follow its deadline and get advice promptly. Transitional protection has conditions; claiming Universal Credit voluntarily does not guarantee that your previous benefit income will be preserved.
Breathing Space Scheme
In England and Wales, an authorised debt adviser can assess you for Breathing Space. Standard protection normally lasts up to 60 days and covers qualifying debts; it does not cancel them or automatically stop every payment obligation.
- adding most interest, fees and charges on debts covered by the protection;
- taking most enforcement action or contacting you to demand payment of those debts. Some necessary or legally required contact is still permitted.
Eligibility includes living or usually residing in England or Wales and being unable, or unlikely to be able, to repay qualifying debts. The adviser checks existing insolvency arrangements and whether you have had standard Breathing Space in the last 12 months. A separate mental-health-crisis route has different duration and eligibility rules.
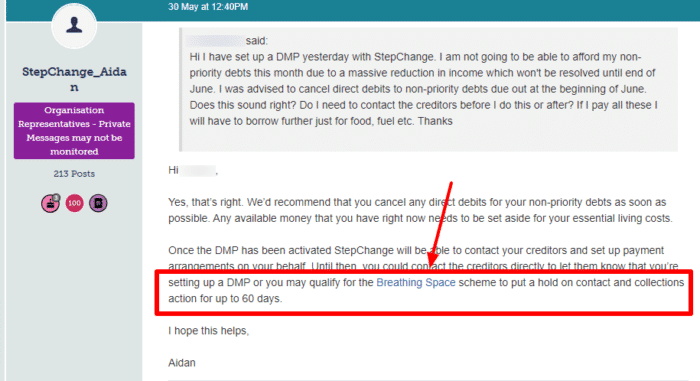
Ask a debt adviser whether the scheme is appropriate. Ongoing rent, mortgage instalments and essential bills still need attention during a standard Breathing Space.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
Assistance from Your Local Council
You can check your local council to see if they have a local welfare assistance scheme. Schemes such as these are offered to low-income people who are facing difficulties with their payments.
Check your local council for what the qualifying criteria are. If you qualify, you could be eligible for a number of different benefits such as small cash loans, grants or free used household goods.
Social Fund
A Budgeting Loan may be available after six months on one or more of the following qualifying benefits. Other conditions apply. Universal Credit claimants must consider a Budgeting Advance instead; neither is a grant:
- Pension Credits
- Income Support
- Income-based Jobseeker’s Allowance
- Income-related Employment and Support Allowance
Budgeting Loans are interest-free but repayable, normally through benefit deductions. The amount depends on household circumstances, savings, existing loans and what you need the money for.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Short-term Benefits Advance
A short-term benefit advance may help while waiting for a qualifying first or increased benefit payment if you face financial need. Universal Credit has its own advance process. These are repayable, not general grants for clearing debts.
In order to apply for a benefit advance, you can contact the Department of Work and Pensions (DWP) office that is responsible for your benefit claim.
How Can I Find Out About Different Grants?
Check grants for your location, needs, background or employment history. Read the permitted uses and eligibility before applying; do not assume a grant will cover ordinary borrowing.
Turn2us provides a benefits calculator and grants search. For advice on dealing with loan debts, use a free debt-advice service such as National Debtline, StepChange or Citizens Advice. Grant eligibility and debt-solution suitability are separate questions.