


How Long Does Debt Last? Limitation, Write-Offs and Student Loans


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
There is no single age at which all UK debts disappear. Court time limits, credit-file retention, insolvency write-offs and student-loan cancellation are different rules.
In this article, we’ll cover:
- When an old debt may be statute-barred.
- Why debt type, jurisdiction and earlier court proceedings matter.
- How student-loan cancellation depends on the repayment plan.
- Why credit-file removal does not prove that a debt has ended.
This guide explains the distinctions. A debt adviser can check the dates and documents in your individual case.
Is an old debt automatically written off?
For many simple-contract debts in England and Wales, a court claim is subject to a six-year limitation period. That does not mean that every debt is cancelled six years after borrowing.
A genuine write-off or release, such as after successful completion of an appropriate insolvency procedure, is different from a limitation defence.
Where limitation applies, it can prevent a creditor succeeding with a late court claim if the defence is properly raised.
In England and Wales the underlying statute-barred debt generally still exists. Scotland has different prescription rules under which many ordinary debts can be extinguished after five years if the conditions are met. Northern Ireland has separate legislation.
Selling a debt does not restart the limitation period. Ask for advice if a new collector contacts you about an old account.
The six-year rule commonly applies to simple-contract claims in England and Wales, subject to the relevant start date, later payments or acknowledgment and earlier proceedings.
The starting point is the cause of action: when the creditor became legally entitled to bring the relevant claim. It is not automatically the borrowing date, first missed payment or credit-file default date.
Check whether a claim was issued within time or a judgment already exists. A CCJ does not disappear six years later; particular enforcement methods may then require permission or face other restrictions.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
Examples of debts that may fall within the simple-contract limitation rules include:
- Credit debts
- Personal loan debts
- Store card debt
- Catalogue debt
A payment or valid written, signed acknowledgment made before expiry can restart a running period. A creditor’s reminder does not. Once the claim is already statute-barred under the Limitation Act, a later payment or acknowledgment does not revive it.
Mortgage shortfalls need separate advice: claims for capital and interest can have different periods, commonly twelve and six years respectively in England and Wales.
Those periods are not automatic cancellation dates. Public debts such as benefit overpayments and council tax also have distinct recovery rules.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
At what point are student loans written off?
Cancellation depends on the loan plan and relevant dates, rather than a plan you can freely choose. Check the government’s student-loan cancellation guidance and your account.
Plan 1 student loans
There are several different factors as to when a student loan is written off.
For Plan 1, if the first loan for the course was paid before 1 September 2006, the normal age-based cancellation point is 65.
If that first Plan 1 loan was paid on or after 1 September 2006, the normal period is 25 years after the April repayment first became due.
Plan 2 student loans
Plan 2 student loans are much simpler and are written off 30 years after the first April on which it was due to be repaid.
Plan 4 student loans
For Plan 4, if the first loan for the course was paid before 1 August 2007, the normal cancellation point is age 65 or 30 years after the April repayment first became due, whichever comes first.
If the first Plan 4 loan was paid on or after 1 August 2007, the normal period is 30 years after the April repayment first became due.
Plan 5 student loans
Plan 5 loans get written off 40 years after the first April on which it was due to be repaid.
Postgraduate Loans for students funded through England or Wales normally use a 30-year cancellation period from the April repayment first became due. Scottish postgraduate borrowing uses Plan 4.
Northern Irish postgraduate borrowing uses Plan 1. Keep meeting repayment and information obligations; arrears and older mortgage-style loans need separate checks.
Statute barred debt: A step-by-step guide
A debt may be statute-barred when the applicable time for bringing the claim has expired. The debt type and jurisdiction determine which rule applies.
Do not ignore court papers: respond by the deadline and explain any limitation defence. A court can enter judgment if no defence is filed.
For consumer-credit collection covered by FCA CONC 7.15, payment demands must stop after you state that you will not pay because the debt is statute-barred.
There is also a protection where the lender or owner made no contact during the limitation period. These rules do not amount to a universal ban on all communication about every old debt.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
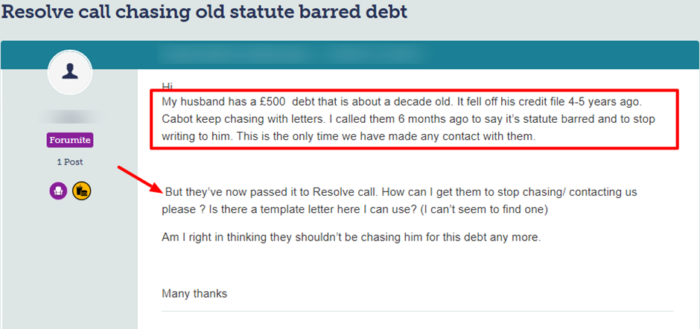
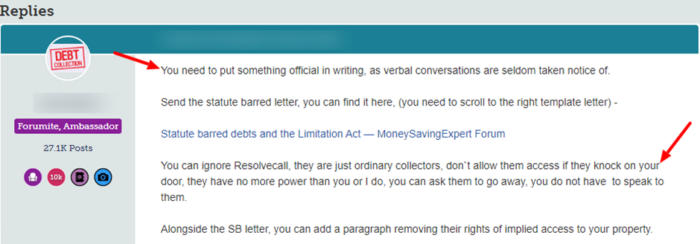
Statute barred debt case study
The forum example below is an individual account, not proof of the legal position in another case. Check the agreement, notices, payment history and any court record.
Source: Moneysavingexpert





