


How Long for Your Credit Score to Go Up After Paying Debt?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you keen to know how long it takes for your credit score to go up after paying off debt in the UK? You’re in the right place. Each month, over 170,000 people come to our website for guidance on debt solutions, as they have worries about debt just like you do.
In this article, we’ll cover:
- What a credit score is and why it’s important.
- How your credit score might change after you pay off debt.
- Ways to make your credit score better after you pay off debt.
- How long it could take for your credit score to go up after you pay off debt.
- What happens with settled debts and how they affect your credit score.
We understand how you feel about debt, as some of us have had debt worries too. We know it can be tough to deal with. But don’t worry; we’re here to help you understand and improve your credit score.
Let’s start learning about credit scores, debt, and how to make things better.
What Is the Timeline for Rebuilding Credit?
The length of time it will take for your credit score to improve after you pay off the debt will depend on multiple factors, some out of your control.
Creditors usually send updates periodically, so a repayment may not appear immediately. Check when the lender next reports and allow time for the credit reference agency to process it.
There is no guaranteed one-to-three-month timetable or promised score increase. Paying a balance can help, but the result depends on the rest of your credit history and the scoring model. A default does not disappear merely because it has been paid.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
How Is It Rated?
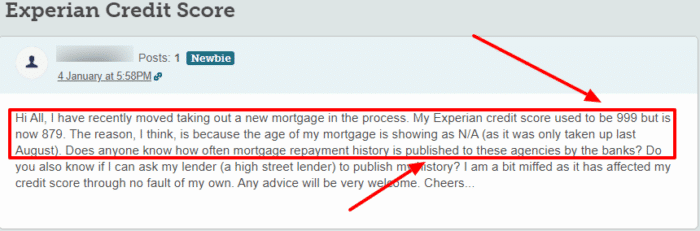
Credit reference agencies use different scales. Experian’s current consumer score runs from 0 to 1,250, following a rollout that began in autumn 2025. Equifax uses a scale of 0 to 1,000. Check the scale shown by the service you use.
Score bands and models differ between providers. Lenders also use their own assessment, including affordability, rather than simply relying on the consumer score you see.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Several things go into the calculation of your credit score, including:
- Your payment history
- Your credit utilisation
- Length of credit history
- Types of credit in use (e.g. mortgage, credit cards, etc.)
- Recent applications for credit
Remember, this is not an exhaustive list, and there are a few adjustments you can make to improve your credit score.
Are All Kinds of Debt Bad?
The answer to this question depends on what you mean by ‘debt’.
Having affordable credit that you manage well can help build a repayment history, but taking on debt is not necessary just to improve a score.
Paying on time is positive, although no single action guarantees that your score will rise.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
A limited credit history can make it harder for a lender to assess you. That does not mean you should borrow money you do not need or cannot comfortably repay.
Why, you ask? Well, having credit and paying back as promised shows that you can handle your finances and stick to an agreement. This is called positive credit behaviour.
But if you are asking if ‘debt’ is bad for your credit score and you mean debts from unpaid loans and credit cards, then yes, this is probably bad for your credit score.
It shows you failed to keep to an agreement and repayments and will probably send your credit score down as a warning to any other loan company or bank that may consider lending you money.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
Ways to Improve Your Rating
There are many ways to achieve this. Here are some examples of ways to improve your credit score after paying off your debts:
- Keep up with other credit repayments
- Keep up with bills and other contracted repayments
- Look for debt solutions for other existing debts
- Don’t apply for lots of unnecessary credit or bank accounts (applications can affect your score too)
- Use credit card builders to gradually bring up your credit score
Where Can I Check It for Free?
In the UK, you have a right to access your credit report for free from any credit reference agency. However, this only gives you a snapshot of your credit history and doesn’t include a credit score.
You can also obtain a free score through several services. For example, Experian offers its consumer score free and provides a free report through its app.
You do not need to take a paid subscription or a trial simply to see a credit score. Check what a service includes and whether any optional upgrade has a charge.





