


How Much Does Equity Release Cost? Complete Analysis


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
“Are you trying to understand the cost of equity release? It can feel a bit tricky with all the different fees and charges. But don’t fret! We’re here to clear things up for you.
We know it can be a bit puzzling, so in this easy-to-read guide, we'll cover:
- What equity release is and who can apply for it.
- How you can get a fair quote.
- What equity release is used for.
- The average interest charged on equity release.
- How much you have to pay back after an equity release.
We understand that you might be worried about any hidden costs or how it might change your tax, but rest assured that we’re here to help you every step of the way. Together, we can make sure you make the best decision for your future.”
Let’s dive in.
What are the costs and fees involved?
Aside from the actual cost to get an equity release plan, there are other costs to consider when setting up the plan and using professional services.
Use a qualified, appropriately authorised equity-release adviser. A client fee does not by itself demonstrate better advice; ask about market coverage, commissions, total fees and service.
Advisers, solicitors and lenders have separate charges. Obtain written quotes stating fixed or percentage fees, VAT, disbursements and when each amount is payable.
The unseen costs!
There might be some unseen costs of equity release relating to the money you are no longer entitled to receive. By receiving a large sum of money, your newfound wealth could mean you are no longer eligible to receive some means-tested benefits, including Universal Credit and Pension Credit (not your State Pension!).
For Pension Credit, savings above £10,000 generally count as weekly income of £1 per £500 or part thereof. The full assessment determines entitlement and any linked support.
Drawdown may affect the capital you hold, but does not guarantee benefit protection. Seek benefits advice about capital limits, disregards and deprivation rules.
» TAKE ACTION NOW: Find out how much equity you could release
What is the average interest?
Rates change and depend on the product and your circumstances. Obtain a current personalised illustration and compare the APRC, fees, repayment options and total projected cost; this article does not quote a live market-leading rate.
How much do I pay back?
How much you pay back on equity release depends on the type of equity release product you choose and specific circumstances.
A home reversion plan is a sale of part or all of your home, usually below open-market value, in return for money and the right to remain under the plan’s occupancy terms. It is not a loan. The provider receives its agreed share when the home is sold.
Illustration only: £65,000 at 6.4% interest compounded annually without repayments would grow to about £137,000 after 12 years, excluding fees. Actual repayment depends on the contract, rate, fees and repayments.
Early exit costs vary. Lifetime mortgages may have early-repayment charges and exemptions; ending home reversion involves different contractual costs.
Use a calculator for help!
A calculator gives an illustration based on stated assumptions. A borrowing-limit estimate and a compound-interest projection answer different questions. Neither is a lending offer, approval or suitability assessment; actual terms require a valuation, checks and specialist advice.
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Do you have to pay tax?
A lifetime-mortgage advance is borrowed capital rather than taxable income. Home reversion is a property sale; later income, gains and gifts can have separate tax consequences.
Will it affect inheritance tax?
Equity release can have an effect on the inheritance tax your estate and beneficiaries may owe. In fact, equity release can both increase or mitigate inheritance tax liability. It is best to discuss this when you receive financial advice.
If you have a short life expectancy and are thinking about using equity release to give money to loved ones, be aware that financial gifts within seven years of your death can still be subject to inheritance tax.
Can you move home afterward?
The Equity Release Council states that all of its members must allow homeowners to move to a suitable home and take their lifetime mortgage with them.
The new property must meet the provider’s criteria. A cheaper home may be acceptable, but a partial repayment or charges can apply.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
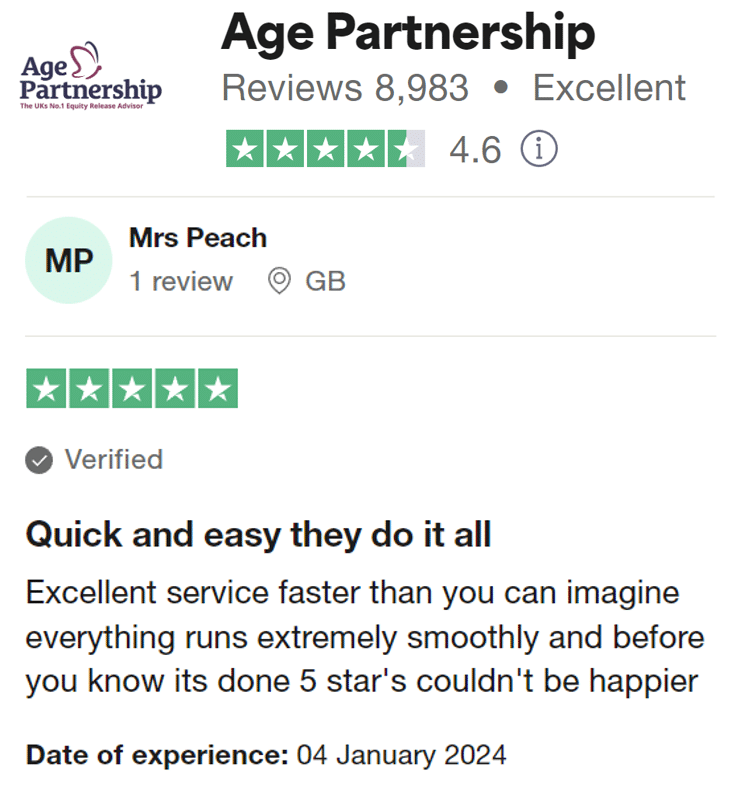
Reviews shown are for Age Partnership. Search powered by Age Partnership.
Still considering a lifetime mortgage?
If you are still considering a lifetime mortgage after discovering the arrangement fee, the true costs of these plans, and more, you can learn the finer details about them on MoneyNerd. Check out one of our other equity release guides for further examples, definitions, and explanations.
Things to consider
Equity release includes lifetime mortgages and home reversion plans. A lifetime mortgage is a loan secured on your home; a home reversion plan sells part or all of the property. Equity release reduces what may be left in your estate and can affect means-tested benefits and future care funding. A lifetime mortgage is usually repaid when the last borrower dies or moves permanently into care, subject to the plan terms. Specialist financial and independent legal advice are needed. Any existing mortgage must normally be repaid from the proceeds or other funds. Age Partnership publishes an advice fee of £1,995 payable on completion; confirm the current fee in your personalised illustration. Lender and legal fees may also apply.





