How Do I Qualify for a Debt Consolidation Loan


The path to managing your debts can seem long and winding. But, a debt consolidation loan might be the tool you need to bring all your debts together, making it simpler to tackle your money worries. Qualifying for one, however, requires understanding certain factors. This guide aims to illuminate these for you.
In this article, we’ll explore:
- The definition of a debt consolidation loan.
- The process to see if you’re eligible for one.
- The potential cost of a poor debt consolidation loan.
- How to obtain a debt consolidation loan even with bad credit.
- Commonly asked questions about debt consolidation loans.
We're here to provide you with the knowledge and guidance you need to navigate this process.
Let’s dive in.
Debt consolidation qualifications
To qualify for debt consolidation, you will need to be approved for a new loan and a loan amount that enables you to pay back at least two existing debts.
This means making a new credit application and being accepted based on your individual circumstances and your credit score.
But it’s not just about being able to access credit. You should assess your situation to ensure consolidation is the most appropriate method to improve your debt situation.
There may be an alternative that can save you more money or even write off some of your debt.
To find out if you qualify from this perspective, you can ask for guidance from a free debt advice charity. They could help you out of debt in the best way for you!
You should also know there are other ways to consolidate debt besides personal loans.
- If you are only wanting to consolidate credit cards, you can complete a balance transfer using a balance transfer credit card.
- A Debt Management Plan or, in Scotland, a Debt Arrangement Scheme programme can combine administration of payments. These are repayment solutions, not consolidation loans.
- Another option is remortgaging to release home equity and using that money to pay off your debts
Remortgaging your home as a way to consolidate debt is by far the most risky. You should only consider this after speaking with a professional mortgage advisor and a debt advice charity.
Where can I get a loan?
Debt consolidation loans are available with banks and building societies offering credit products and services.
Getting a decision on your application is usually quick, especially if you already have a bank account with the lender. These types of personal loans are also available from online loan providers.
Compare personalised APRs, total repayment, fees and affordability. A representative rate is an advertising measure, not a guaranteed offer.
One useful tool that most loan providers will offer is a loan calculator. The loan calculator allows you to determine the cost of your debt consolidation loan.
Simply enter the amount of money you would like to borrow to consolidate your existing loans and cards – and how long you need to repay.
A calculator estimates payments using its stated amount, rate and term. It is not a lending offer, eligibility confirmation or suitability assessment. Compare the personalised terms and total cost before applying.
Enquire about borrowing options through Loans Warehouse
How hard is it to get one?
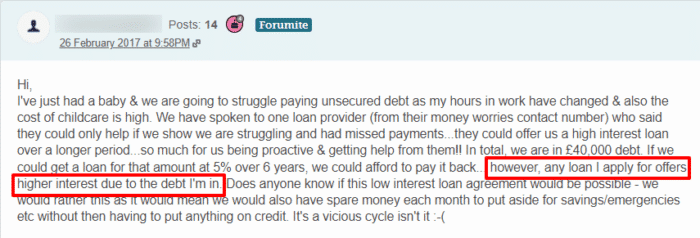
The difficulty of accessing a debt consolidation loan is comparable to trying to get any other type of unsecured personal loan.
Some experts suggest getting a debt consolidation loan is a little more difficult. However, there is not a big difference, if any difference at all.
The lender will evaluate how likely you will be able to keep up with monthly payments based on the loan amount and interest rate available to you.
Much of this will depend on your income and how you handled your finances in the past. This means acceptance of these loans is subject to a credit score check.
Before you apply for a loan of this kind, you might want to try and improve your score first (more on this below!).
What credit score do you need to consolidate debt?
There is no universal credit score that qualifies you for a UK consolidation loan. Credit reference agencies use different scales and lenders make their own assessments.
A US FICO score of 670 is not a UK Experian approval threshold. Review your UK credit reports for accuracy, but do not treat a consumer score as a lending decision.
Free statutory credit reports are available. If you choose a paid monitoring trial, check renewal and cancellation terms.
Arrears can restrict options, but a score alone does not determine acceptance; affordability and the lender’s criteria matter.
Keep in mind that these loans are also used by people who are not in arrears. They’re taken out by those who want a new personal loan to consolidate other credit and make repaying their current loans and credit cards cheaper – even if they’re not struggling to repay them in the first place.
It’s not just people with financial difficulty who use debt consolidation loans!
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
How do I get it with bad credit?
The above does not mean you will be automatically rejected for a debt consolidation personal loan if you don’t have a “good” or “excellent” rating.
There could still be plenty of lenders willing to accept you for a loan with a poor credit rating.
However, because you are seen as a greater risk for defaulting on payments or not repaying the fixed monthly payment in full, the interest you pay is likely to be higher.
For a regulated consumer-credit promotion using a representative APR, that rate or lower must be expected to apply to at least 51% of credit agreements entered into as a result of the promotion. It is not a promise to 51% of everyone who applies, and the rule should not be applied indiscriminately to mortgage APRC illustrations.
The personal rate may be higher or lower than a representative example. There is no simple “below average score” formula for the rate.
If you want to find creditors that lend to people without a perfect credit score, you can search your options online.
Or you can check out this guide, which discusses some of the debt consolidation loan options for people with a poor credit history.
On the other hand, you could try to improve your credit file over many months before using the debt consolidation strategy. Taking your time to improve your file and then applying for a loan could be more beneficial in the long term.
The loan amount you need by that time may also be smaller if you’ve continued repaying, making it even more likely to get accepted for the loan.
Will I qualify?
Your debt consolidation loan application will be assessed by the lender you apply to based on individual circumstances, your credit score, the loan rates and amount – and possibly other factors.
Because so many things need to be considered, it’s not possible to say if you will or will not qualify for the debt consolidation loan you apply for.
Some eligibility checks use a soft search that does not affect your score. Check the provider’s process: an indication is not approval, and a full application may involve a hard search.
If your debt consolidation loan application is rejected, try not to worry. There are alternative options and strategies you could use that will also help you get back on track.
We’ve discussed them in further detail below…
How to get approved
There is no sure-fire way of getting approval for a debt consolidation loan. But there are things you can do to improve your chances.
Most of them revolve around improving your credit score so creditors believe you are not a risk.
So, how could you improve your credit score?
We’ve already explained the importance of looking for credit file errors and having them put right. But here are some additional hints and tips that may improve your score in the short term:
1. Get on the electoral register
Registering to vote at your current address, if eligible, can help identity checks and your credit profile.
It does not guarantee a specific score increase or turn a rejected application into an approval.
Check your address details with the credit reference agencies after registering; other factors still determine lending decisions.
2. Reduce your credit utilisation
Your credit utilisation is the amount of credit you have been approved for against the amount of credit you have used.
For example, if you have been approved for three cards of £500 each and you have spent £750 across those three cards, you have a credit utilisation of 50%.
Paying down balances can reduce utilisation and interest, but a score increase is not guaranteed.
Closing an unused account can change your available credit and utilisation. Consider cost, fraud exposure and the risk of further spending as well as the score.
3. Keep up with bills
It’s tempting to think your ongoing bills don’t matter when you have more serious debts. But you should be putting the same efforts into preventing those bills from becoming debts that you put into clearing your debt.
Missed payments that are reported can damage your credit record. Prioritise essential and priority bills and seek debt advice if payments are unaffordable.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. A lower monthly payment may mean paying more overall, and secured borrowing puts your home at risk if repayments are not maintained.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
Alternative Debt Solutions
If you do not get approval for a debt consolidation loan, there are other debt management strategies and debt solutions available.
Some of the most popular are:
1. Debt Management Plans
A Debt Management Plan (DMP) is an informal agreement with your lenders to pay off your debt in one monthly payment.
The new payment will take into account your financial difficulty and may not include a lower interest rate.
2. Debt Relief Order
A DRO can protect against action for included qualifying debts during its moratorium, normally 12 months. Excluded debts and ongoing bills still need attention; required communications may continue. See related guidance.
In England and Wales, the main limits include debts of £50,000 or less, surplus income of £75 a month or less and assets of £2,000 or less, with a separate vehicle allowance of £4,000. You must not own a home and other conditions apply. An approved intermediary checks eligibility.
Qualifying debts included in the DRO are normally written off at the end if it is not revoked. It does not erase every type of debt.
3. The Snowball Method
The Snowball Method is used when someone has multiple debts. The debtor prioritises minimum monthly payments on each debt, and then any extra disposable income is used completely to pay the smallest debt. Thus, it focuses on reducing the number of debts first.
A word on balance transfer cards
If you would like to borrow to consolidate credit cards only, then another alternative is to use a balance transfer credit card instead of a consolidation loan.
This is a special type of credit card that allows you to transfer the balance of your existing debts (credit cards only!) to the new card.
If the new card has a lower fixed interest rate than your other cards, then you could save on your payments. Many of these cards include a 0% fixed rate for so many months to help reduce payments.
This could be a more appropriate and lucrative option than applying for loans.
More information
We’ve covered many questions from debtors about how to qualify for debt consolidation loans. If you didn’t find what you were looking for, we’ve probably covered it in one of our other consolidation debt guides.
And remember there are many excellent UK debt charities waiting to help you. They offer free private debt advice to help guide you through the process. They will assess your situation and recommend the most suitable debt solution based on your personal situation.
Free support is available from organisations such as StepChange and National Debtline, and MoneyHelper can direct you to debt advice.
If you’ve just started thinking about debt consolidation, pick up the phone and have a chat with a trained advisor!