


Cannot Pay Klarna? Support Options and What Happens Next


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you struggling to manage your Klarna debt and worried about what happens next? You’ve come to the right place. Every month, over 170,000 people visit our website for advice on debt problems.
In this guide, you’ll learn about:
- What Klarna is and how it works
- The steps to take if you can’t pay your Klarna debt
- The possible outcomes if you don’t pay Klarna, including late fees, credit score damage, and debt collection efforts
- How to get in touch with Klarna and discuss your payment issues
- The option of writing off some Klarna debt
In 2022, arrears on household bills increased by 68% from £1,739 to £2,9201. So, it’s common to be concerned about debt and missed payments.
Don’t worry! We’re here to help you learn how to deal with your Klarna debt. Let’s get started.
What You Need to Do
Budget Advice
I’ve put together this table that provides 10 budgeting tips to help you manage your finances effectively and avoid missing payments.
| Budgeting Advice | How You Can Lower Your Expenses |
|---|---|
| Arrange a Debt Repayment Plan | To negotiate, contact your creditors via phone, email, or letter to explain your financial situation, and offer to pay an amount you can afford. |
| Save on Utility Bills | Compare energy providers to find a cheaper deal. Use energy-efficient appliances. Reduce water usage with low-flow fixtures. |
| Save on Groceries | Shop with a list to avoid impulse buys. Buy store brands instead of name brands. Look for sales and use coupons. |
| Cut Back on Non-Essentials | This includes dining out, entertainment, subscriptions, and luxury items. Look for free or low-cost entertainment options and cook meals at home. |
| Transportation Costs | If possible, use public transportation, carpool, or consider biking to work. If you own a car, maintain it regularly to avoid costly repairs. |
| Negotiate Bills | Contact service providers (like phone, internet, and cable) to negotiate a lower rate or switch to a cheaper plan. |
| Consolidate Debts | Compare the full cost and term before using new credit to repay debts. Fees or a longer term may increase the total paid, and securing debts on your home puts it at risk. Seek free debt advice if payments are already unaffordable. |
| Sell a Financed Car | If the finance company owns the vehicle under hire purchase or PCP, you cannot sell it without its permission or first settling the finance. Ask for a settlement figure and advice on your options. |
| Use Cash Instead of Credit | To avoid accumulating more debt, use cash or a debit card for your purchases. |
| Seek Professional Advice | If you’re struggling, consider contacting a debt advice service like StepChange or National Debtline. They offer free, confidential advice. |
What happens if you don’t pay?
Missing a Klarna payment can lead to reminders, applicable late fees, credit reporting and possible collection action. The costs depend on your product and agreement.
Contact Klarna about an unaffordable payment and ask for support. If you dispute an order, report the issue and keep evidence.
This includes:
Late fees and interest charges
Check your agreement for any late fee and the circumstances in which it applies.
Pay in 3 and Pay in 30 days are interest-free products; a missed payment does not automatically turn them into interest-bearing loans. Financing and other Klarna products can have different interest terms.
Ask Klarna to explain any charge and discuss support if it would worsen financial difficulty.
Credit score damage
There is an impact of Klarna on your credit score.
Klarna reports payment information, including Pay in 3 and Pay in 30 days, to credit reference agencies. Late or unpaid balances and payment arrangements can affect how other lenders assess you. Do not assume that a Buy Now Pay Later payment is invisible on your credit file.
A lower credit score can make it harder for you to get approved for credit in the future, and you may end up paying higher interest rates on loans and credit cards.
Your credit score is calculated based on a number of factors, including your payment history, the amount of debt you have, and the length of your credit history.
The effect on your score and future applications depends on what is recorded and your wider credit history. There is no fixed six-year recovery timetable for every missed payment.
Debt collection efforts
If you don’t pay your Klarna bills, the company may also hire a debt collection agency to recover the debt as part of the Klarna collections process.
Debt collectors can be aggressive, and they may use tactics such as calling you repeatedly and threatening legal action.
They must not harass you or use misleading threats. A creditor may, however, warn about court action that it is lawfully entitled to take.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Contact Them If You’re Struggling to Pay
An eligible order may offer a short extension. Check the revised due date and any conditions in the app.
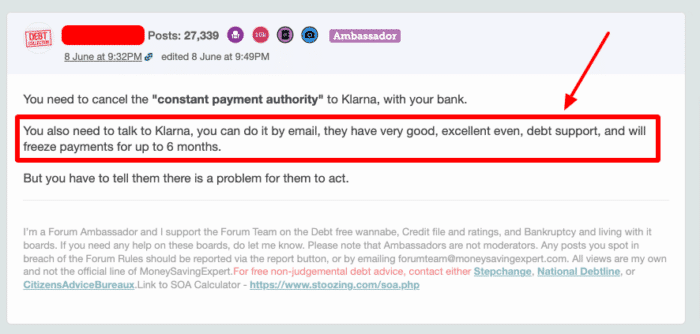
If the option is unavailable, or you need longer-term help, contact customer support.
Seek help even if the payment is already late. Do not agree to an amount you cannot afford after essentials and priority debts.
Klarna Contact Details
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
The Financial Hardship Option
» TAKE ACTION NOW: Fill out the short debt form
I Have an Existing Payment Holiday. Can I Extend It?
What Happens When They Send Your Details to an Agency?
Dealing With Debt Collection
What If I Can’t Pay?
References





