


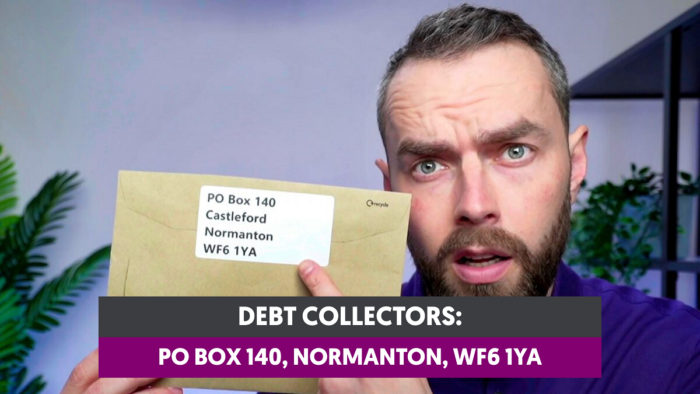
PO Box 140 Normanton WF6 1YA Debt Letter – Who is it?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Have you received a letter from PO Box 140 Normanton WF6 1YA about a debt? This can be very confusing and a bit scary.
A return address alone does not identify or authenticate the sender. Read the named organisation, account details and any deadline before responding.
In this article, we’ll:
- Help you understand who might have sent the letter.
- Show you how to find out if the debt is really yours.
- Give you tips on how to respond to the letter.
- Explain what you can do if you can’t afford to pay.
- Guide you on how to get more help if you need it.
If the demand is unfamiliar, verify it through a trusted contact route and keep a copy. Free debt advice can help you assess the account.
With our experience, we’ll help you understand your options. Let’s work out what to do together!
Should you ignore a letter from them?
We always recommend responding to debt collectors – even just to question the debt’s validity.
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
How should you respond to the letters?
» TAKE ACTION NOW: Fill out the short debt form
It is very important that you keep good records when dealing with your debts. Keeping copies of letters that you have received and sent is the easiest way to maintain healthy records.
Up-to-date documentation will be vital if there is a dispute about your debt in the future – you will have all the evidence you need at your fingertips if you keep copies of letters!
You may also need your documents if your debt is sold and information on your payment status, for example, is lost.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Are the letters legitimate?
How Do You Verify a Company?
Before you respond to any letters, you need to make sure that you are dealing with the right company or that you aren’t dealing with scammers of phishing letters.
Verifying a company before you make any payments is an easy method of financial fraud prevention.
Companies House can help identify a company and its registered details. Registration is not an endorsement of its conduct or proof that a particular letter came from it.
Compare the company name and number, then verify the contact route independently. Fraudsters can copy genuine registration details.
For a regulated financial activity, check the FCA’s current record and permissions. CSA membership is a separate trade-association matter, not regulatory authorisation.
Not every type of debt collection requires the same FCA permission, and trade-body membership is not universal. Assess the actual activity rather than treating absence from one list as conclusive fraud.
You can check registration records by using the FCA’s register or the CSA’s membership page.
For a solicitor in England and Wales, check the appropriate legal regulator, commonly the Solicitors Regulation Authority. Scotland and Northern Ireland have different legal regulators. See related guidance.
For an enforcement visit, check the person’s identity and authority for that case. A trade-association listing alone is not a writ, warrant or enforcement-agent certificate. See related guidance.
Check the firm and contact route independently before sharing information or paying. A genuine company name, registration number or displayed caller ID does not prove that a particular message is authentic.
If you are unsure, you shouldn’t hesitate to get some advice. There are several charities offering UK financial advice services for free, and will be able to help you verify a debt letter.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Do you owe them money?
What should you do if you have debt?
Your Rights With Debt Collectors
It’s important to understand your rights when dealing with debt collectors. That’s why we’ve put together this table. For more information on what debt collectors can and can’t do, check out our specialized guide.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Where is PO Box 140 Normanton?
Final Thoughts
References





