


Lifetime Mortgage Rules – Current Laws and Pitfalls


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
Are you wondering what are the lifetime mortgage rules you need to know? You've come to the right place for answers.
In this article, we’ll address the following questions:
- What is a lifetime mortgage and how does it work?
- Who qualifies for a lifetime mortgage?
- Can you take out a lifetime mortgage on any property?
- How much interest will you pay with a lifetime mortgage?
- Can you pay off a lifetime mortgage early?
Home improvements are one possible use of released funds. Historic survey percentages should not be treated as last year’s results without a dated source.
So, if you’re considering a lifetime mortgage for similar reasons, it’s important to understand the latest regulations and potential pitfalls associated with these financial products.
Don’t worry, we’re here to provide you with the necessary information. Let’s get started!
What is a lifetime mortgage?
A lifetime mortgage is a loan secured on your home; you retain ownership. Interest that is not paid is added to the balance. The loan is usually settled when the last borrower dies or moves permanently into care, subject to the contract. Required or optional repayments vary by product.
Lifetime mortgages and home reversion plans are the two main equity-release types; only the former is a loan.
The other type of equity release plan is called a home reversion scheme, but it’s used less often because it involves selling a percentage of your home to the lender.
Equity release comparison
I’ve put together this quick table to help you better understand the main differences between a lifetime mortgage and a home reversion plan.
| Category | Home reversion plan | Lifetime mortgage |
|---|---|---|
| Ownership | You sell part or all of the home, usually for less than open-market value, and remain under the plan’s occupancy terms. | You retain ownership and borrow against the home. |
| Property value changes | The provider receives the agreed share of future sale proceeds; only any retained share belongs to your estate. | Sale value and the outstanding loan, interest and charges affect the amount left for your estate. |
| Inheritance | Selling a share reduces what you can leave; any protected share and conditions must be checked. | Rolled-up interest can reduce the remaining equity. Inheritance protection may be available under some plans. |
| Repayment | There is no loan to repay for the sold share; the provider receives its share when the property is sold under the plan. | Usually settled when the last borrower dies or moves permanently into care. Payment options and obligations vary. |
| Money received | A lump sum or income may be available, depending on the plan. | A lump sum or agreed drawdown reserve may be available; access remains subject to the plan terms. |
How does a lifetime mortgage work?
Lifetime mortgages allow the homeowner to borrow against some of the value in their residential property.
They receive a loan which is charged with interest.
Many lifetime mortgages allow interest to roll up without regular payments, but some require interest payments for a set period. Optional repayments, limits and any early-repayment charges depend on the contract.
The loan gets bigger over time as interest is added and no repayments are made. The debt must be repaid when the homeowner sells their property.
Repayment is normally due when the final borrower dies or moves permanently into care, subject to the contract. Other repayment triggers can also apply:
- The last surviving homeowner dies
- The last surviving homeowner moves into an aged care home or equivalent
» TAKE ACTION NOW: Find out how much equity you could release
Who qualifies for it?
Most standard lifetime mortgages start at age 55, but some payment-term lifetime mortgages are available from 50 and require interest payments for an agreed period. Home-reversion minimum ages and all other eligibility rules depend on the provider. Check the youngest applicant’s age and the actual product criteria.
Both homeowners applying for a lifetime mortgage together will need to meet this minimum age requirement.
You don’t have to be retired like some people are led to believe:
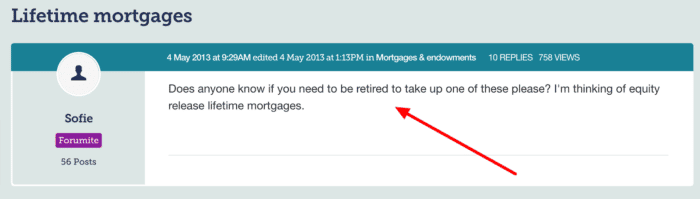
Source: https://forums.moneysavingexpert.com/discussion/4583237/lifetime-mortgages
You can be too old for a lifetime mortgage, but it’s quite rare.
Minimum and maximum ages vary by provider and product. Check actual criteria rather than assuming a universal 85- or 100-year upper limit.
Can you take out a lifetime mortgage on any property?
You must take out the lifetime mortgage on your residential home where you habitually live and plan to keep living.
Remember, the debt becomes owed when you stop living there, even if you haven’t sold the property yourself, so buying to let isn’t really an option.
An existing mortgage normally has to be cleared at completion, often from the release proceeds. It does not universally need to be paid off before applying.
Several properties can cause issues and result in a rejected lifetime mortgage. These include:
- Leaseholds with short leases
- Flood risk properties
- Park homes may not provide the property security required for a standard lifetime mortgage; specialist advice and an actual product check are needed.
- Retirement homes are rarely accepted
- Properties with flat roofs
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
How much interest will you pay?
Rates change and depend on the product and your circumstances. Obtain a current personalised illustration and compare the APRC, fees, repayment options and total projected cost; this article does not quote a live market-leading rate.
Lifetime mortgage interest rates are compounding.
This means the interest added is based on the loan amount and the previous interest you have accumulated.
If interest is rolled up without payments, the debt compounds. Some plans require or permit interest payments, changing the growth of the balance.
What can you use it for?
Funds may be used for various purposes, subject to provider terms and advice on the intended use, tax, benefits and risk. See related guidance.
Some of the common reasons people take out a lifetime mortgage are to:
- Create financial security in later life
- Pay off existing debts
- Home improvements
- Help family members, usually to buy property
- Private medical care
Factors of mortgage repayment
Lifetime mortgages are known to be expensive debts to repay, even if you don’t have to make monthly repayments.
But the amount you’ll repay hinges on several factors.
The debt will grow based on your initial loan amount, the interest rate, and the length of time you have the lifetime mortgage.
As their name suggests, you are expected to have a lifetime mortgage for the remainder of your life.
So it’s impossible to know with any certainty how long you’ll have the loan and therefore how much you’ll need to repay.
But we can give you a standard example to show how much the debt could grow…
Fictional illustration: a person borrows £65,000 against a £195,000 home at an assumed 6.4% annual compound rate. This is one-third of the property value, not a guaranteed lending limit for any age.
After 12 years with no repayments, the balance would be about £137,000, excluding fees. Permanent care can trigger repayment under the terms; the figures are an illustration, not an offer.
The actual settlement amount depends on the contract, fees and repayments, and any applicable guarantee.
What costs do you pay?
Along with the potential significant loan repayment cost, you will also need to pay for equity release advice, equity release solicitor services, and possibly brokerage services.
Some of these services can be provided by the same person or company.
Setup fees vary. Obtain separate written quotes for advice, legal work, valuation and lender charges, including VAT and when each fee is payable.
Can you pay off a lifetime mortgage early?
Yes, you can pay off a lifetime mortgage early if desired.
But you might be charged with an early repayment fee for doing so. The early repayment fee is usually an amount based on a percentage of the debt.
If the lender uses a fixed early repayment structure, the percentage you’ll pay depends on the number of years you’ve already held the lifetime mortgage.
In some cases, if you’ve held it for over eight years, you might not have to pay an early repayment cost.
Other lenders could use a variable early repayment structure.
These lenders use Gilt performance to determine how much to charge you to repay early. A Gilt is a type of bond with the UK Government.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
Reviews shown are for Age Partnership. Search powered by Age Partnership.
Can you move home with a lifetime mortgage?
Moving may be possible if the new property meets the provider’s criteria. It does not universally need to have equal or higher value.
Downsizing may require partial repayment and charges; the lender calculates this under the product terms.
A downsizing-protection clause can waive charges only when its conditions are met.
What are the different types?
There isn’t just one type of lifetime mortgage. There are some variations on the lifetime mortgage explained above.
The three most common variations are:
Drawdown lifetime mortgages allow later withdrawals under an agreed facility. Interest normally applies only to sums drawn; future rates and benefits effects need individual assessment.
Interest-payment lifetime mortgages may have voluntary or mandatory payments. They can reduce interest growth but require an assessment of affordability and product conditions. See related guidance.
Enhanced lifetime mortgages – these work as described above but allow the homeowner to access more of their equity due to poor health. If you have poor health and a reduced life expectancy, the lender may allow you to access a bigger loan.
Is it right for you?
Lifetime mortgages shouldn’t be rushed into.
They need careful consideration and support from an equity release adviser. Receiving advice is now mandatory as part of Equity Release Council guidelines.
The adviser will assess your situation and see if there are other options before considering you for an equity release lifetime mortgage.
References





