Lowell Financial Debt Collection: Letters, Payments and Disputes


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
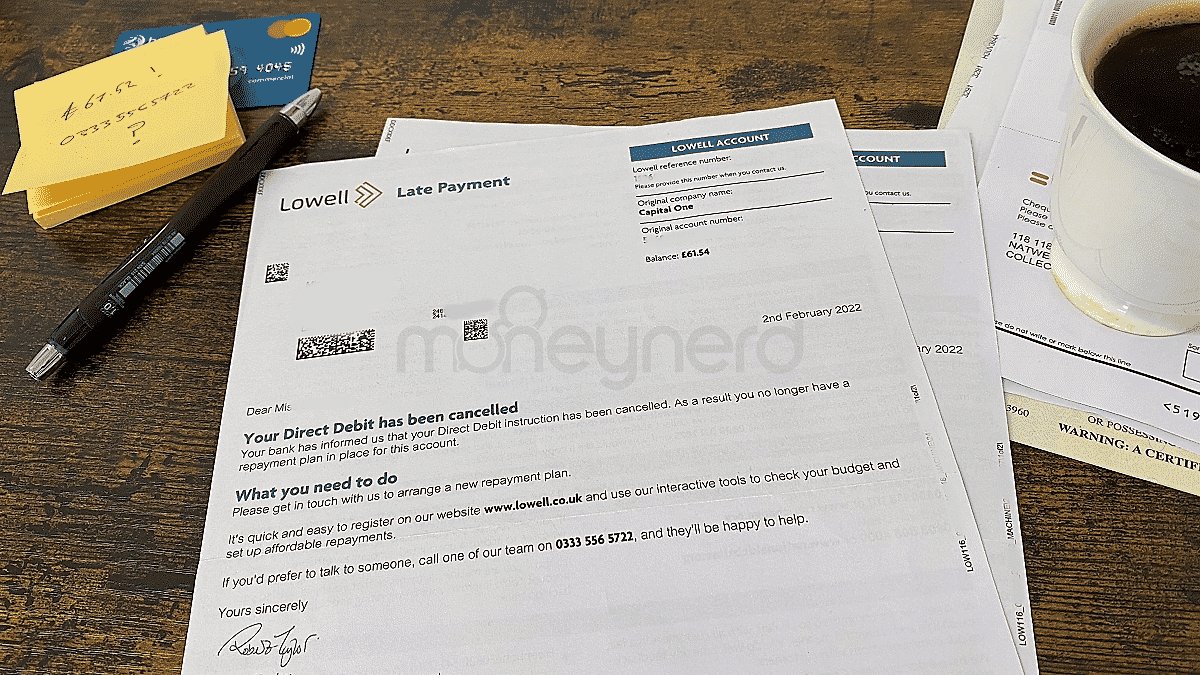
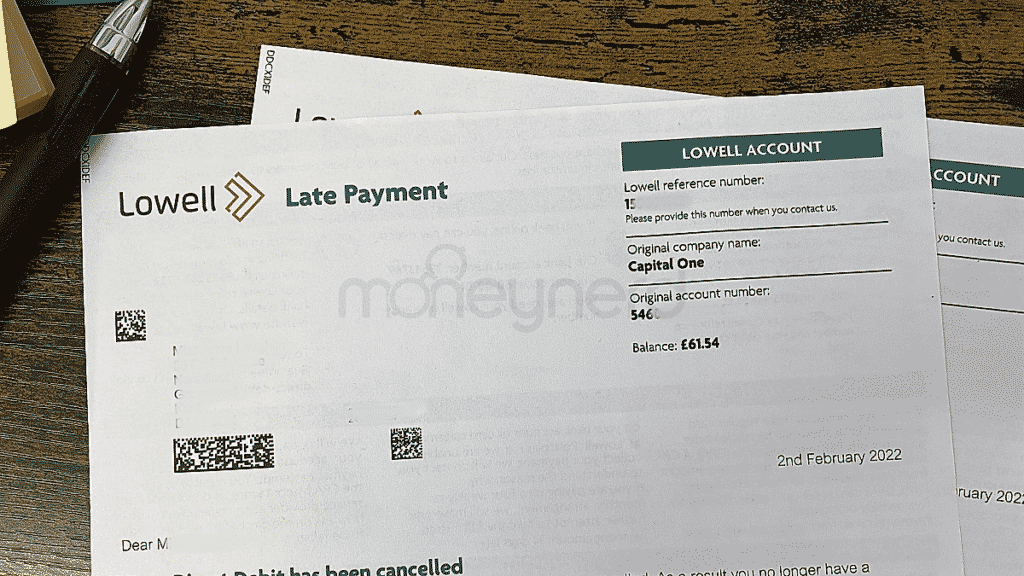
When a letter from Lowell Financial Debt Collection lands on your doormat, it can be a bit scary. But don’t worry; we’re here to help you understand what’s happening and what you can do about it.
This guide explains how to check the account and choose an appropriate response.
In this article, we’ll help you figure out:
- How to make sure the debt is really yours.
- What you can do if you can’t afford to pay.
- How to stop Lowell from contacting you too much.
- Ways to set up a payment plan or even get your debt written off.
You can request account information and seek independent advice if the debt or contact is causing difficulty.
So, let’s dive in and find out more about Lowell Financial Debt Collection and what you can do if they’re chasing you.
Why are they contacting me?
Lowell’s website explains that Lowell Portfolio I buys debts and Lowell Financial collects them. They are separate companies within the group.
The amount paid for an assigned account does not determine what you legally owe.
They buy debts from other organisations, so the money they claim you owe will be originally owed to a different company. So just because you’ve never heard of Lowell, doesn’t mean you don’t owe them.
An unexpected letter may be genuine, mistaken or an impersonation attempt. Verify the sender and account without assuming either validity or misconduct.
This can be confusing, which is why it is crucial that you ask Lowell Financial to prove you owe the money first. We can help you do just that with our prove the debt template letter.
» TAKE ACTION NOW: Fill out the short debt form
Knowing Your Rights with Debt Collectors
It’s important to know what Lowell can and can’t do when it comes to demanding payment from you.
We’ve put together this table to give you a general overview. For a more detailed breakdown, make sure to check out our article on your rights with debt collectors.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Should You Pay?
If liability, balance and enforceability are established, consider payment or an affordable arrangement. Protect essentials and priority bills first.
For many unsecured debts in England and Wales, the usual limitation period is six years from the relevant cause of action, not simply the last phone call. A payment, qualifying written acknowledgement or court proceedings can affect the position. Scotland usually has a five-year prescription period for many ordinary debts, with different rules and exceptions. Court judgments, secured debts and some tax debts require separate advice. Get free debt advice before paying or acknowledging an old debt; do not ignore court papers.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What Happens If You Ignore them?
An entitled creditor may bring a claim. If you fail to respond, a default judgment may be entered without a contested hearing, so follow the court deadline.
Lowell says it does not charge interest or administration fees where customers work with it to manage the account. Court action can add costs; ask what applies to your particular account.
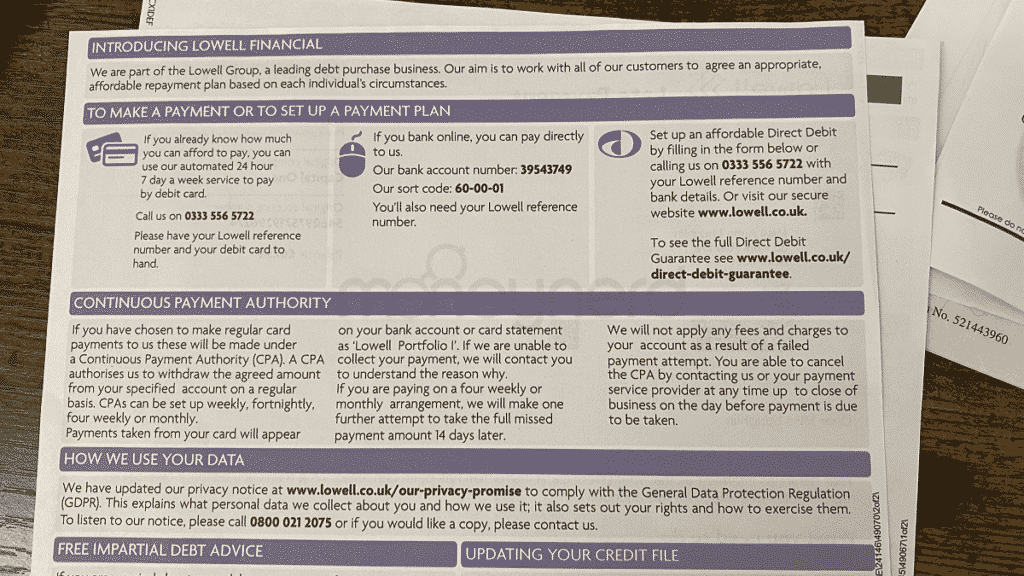
Best Way to Pay
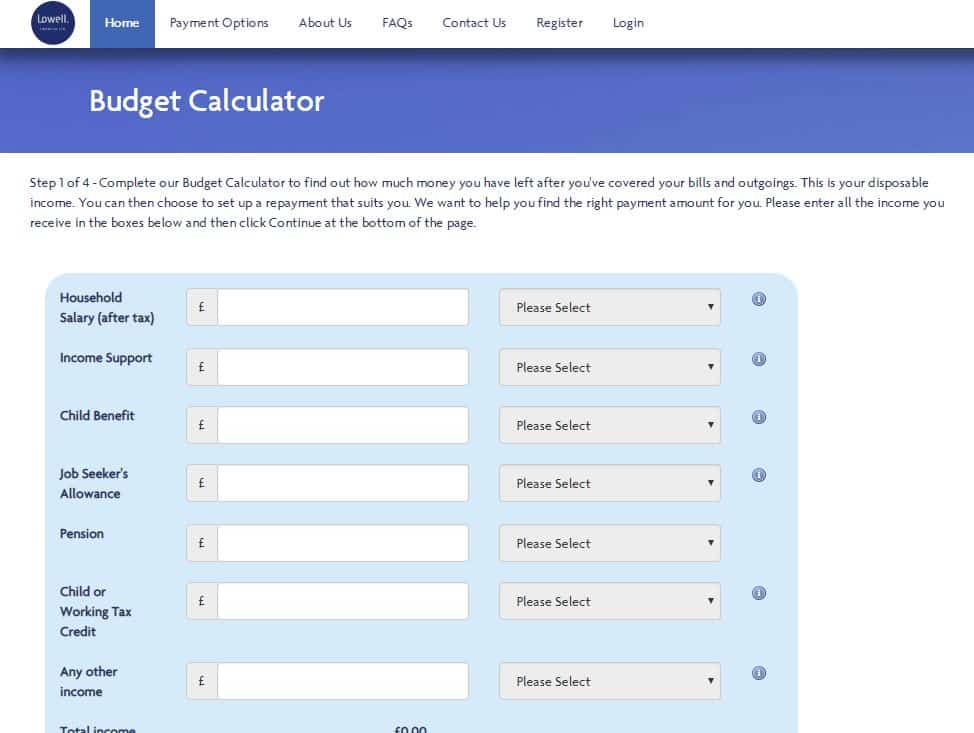
You can make a payment to Lowell over the phone or online. They even have a website tool that can help you work out what you can afford to pay back each month (see below). Or you could use our free budgeting guide!
Next, check out their payment options page (their site has easy navigation).
Here you can enter your Lowell Financial reference number that you likely received at the top of any letters.
Make sure you note down the reference number of your payment, so next time they call you you can tell them that you’ve already paid (it may take some time for this payment to be reflected on your account).
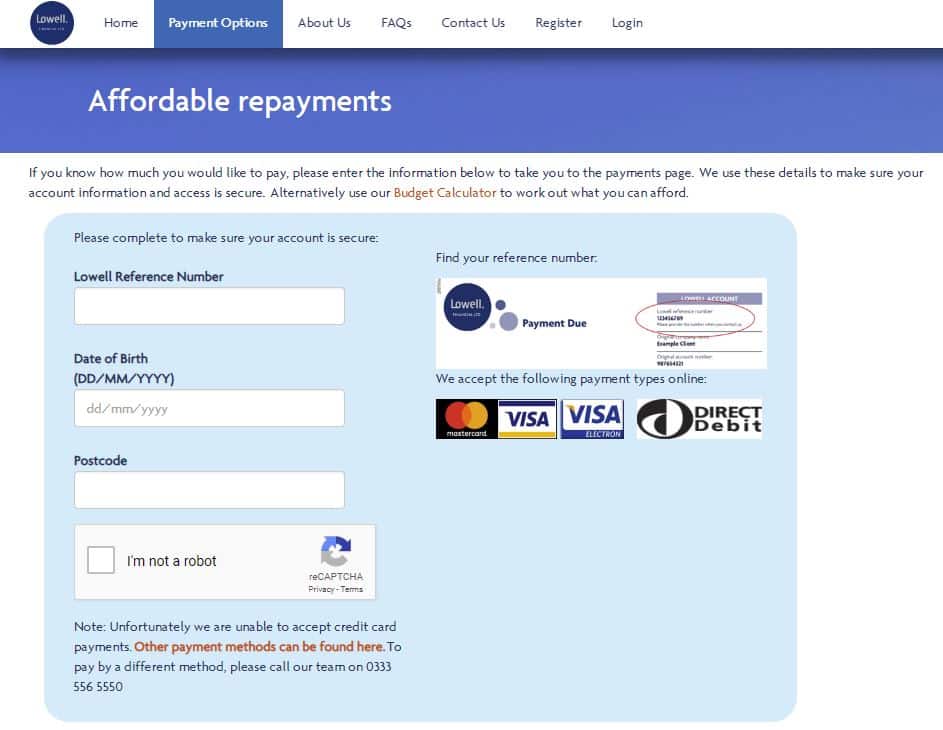
As you can see it’s relatively simple to make a payment providing you have the reference number and card to hand.
Will they use Bailiffs?
The short answer – Maybe. Lowell Financial Ltd are not bailiffs themselves and it would be a legal offence for anyone to pretend to be one.
A debt collector cannot seize goods. Bailiff enforcement of an ordinary civil debt normally requires an unpaid judgment and separate enforcement authority.
Discussing an affordable arrangement may help resolve matters, but cooperation alone does not guarantee that legal action or enforcement stops. Obtain written confirmation of any pause.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Is It possible to write off my debt?
Some accounts can be resolved through an accepted settlement or suitable formal solution. Eligibility, costs, assets and excluded debts all matter; no particular write-off is guaranteed.
Some ways to write off part or all of the debt include:
Limitation in England and Wales can provide a court defence rather than writing the debt off. Scotland has different prescription rules. Get advice before paying or acknowledging an old debt, and never treat a template letter as a substitute for responding to court papers.
Can I stop them from calling me?
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
For regulated consumer credit collection, FCA rules require firms to give due regard to reasonable requests about when, where and how they contact you. You can ask for letters or emails instead of calls and explain any health or accessibility needs. This is not an automatic ban on every call or required notice. Keep a record of unreasonable contact and complain if your request is not properly considered.
If you’re looking for a way to deal with your debts for good then you might consider using one of the UK’s 7 debt solutions.
How do I make a complaint about them?
Complain using a suitable method through Lowell’s official complaints process and keep a record. A phone call is not guaranteed to be the fastest route.
Any complaints should be first directed towards Lowell Financial so they have a chance to put things right.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
The FOS have a lot of authority and can make a big difference if your complaint is justified.
Who is Lowell Telecom?
If you’ve received a letter talking about an account labelled “Lowell – telecom”, it’s likely that you owe a debt to a telecommunications company. This could be an unpaid phone bill or you’ve got debts with your broadband provider.
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
Lowell Group Debt Collection Contact Details
Use Lowell’s current official contact details rather than trying unverified numbers from older online listings.
| Official website | Lowell |
| Telephone | 0333 556 5552 |
| Postal address | Lowell Financial Ltd PO Box 13079 Harlow CM20 9TE |
| Opening hours | Monday to Friday, 9am–6.30pm; Saturday, 9am–4pm. Closed Sundays and bank holidays. |
| Online contact | Official contact form |
References