


Moriarty Law Debt Letters: Disputes, Court Claims and Payments


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
A debt letter can be worrying. Keep the correspondence, check the creditor and balance, and note any response deadline. Free independent debt advice is available.
In this article, we’ll discuss:
- How to check if the debt is really yours.
- What to do if a debt collection agent visits your home.
- How you might be able to write off some Moriarty Law debt.
- How to stay on top of your debts.
If dealing with debt is affecting your wellbeing, seek support and tell the firm about any communication or accessibility needs. A debt adviser can help you decide what to do next.
We truly understand your concerns and are here to help you learn more about dealing with Moriarty Law Debt Collection.
How to Deal With Moriarty Law Debt Collectors
Check the creditor, account and balance identified in the letter. If you dispute liability or an amount, explain the issue and request the relevant evidence.
If you dispute the debt, explain why and request an itemised balance and evidence of liability. For recovery covered by FCA consumer-credit rules, a valid or potentially valid dispute must be investigated and recovery paused. A generic proof request does not cancel a debt, override an existing judgment or extend a court deadline. See related guidance.
From our experience, it is too common for people to pay a debt before checking to see if they owe it!
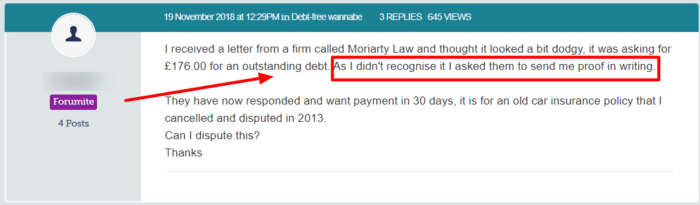
This forum account describes a dispute, but does not establish that Moriarty Law acted wrongly. An evidence request does not automatically remove a deadline; check any letter of claim or court papers.
Many ordinary unsecured debts have a six-year limitation period in England and Wales or a five-year prescription period in Scotland. The start date, debt type, relevant payments or acknowledgments and court action matter. Ask an adviser to check before paying or admitting liability, and respond to court papers on time.
But some debts last longer than others!
A debt with an existing judgment, council tax liability order or enforcement warrant cannot be assessed using a simple six-years-since-last-payment rule. Tax debts also have special rules. A judgment does not disappear when its six-year credit-file entry ends, although later enforcement may require court permission.
Typical Debt Collection Process
If you’ve missed a payment, Moriarty Law can call you and send letters. This is quite normal, as it’s part of the first stage of the debt collection process.
We’ve put together this table to help you better understand the debt collector timeline. For more information, be sure to check out our specialized guide.
| Possible stage | What can happen | What to do |
|---|---|---|
| Missed payments | The creditor or collector may contact you, apply contractual charges or issue required notices. There is no single timetable for every debt. | Check the debt and contact the creditor early. Prioritise essential bills and seek free debt advice. |
| Collection activity | Letters, calls or a proposed visit may follow. A collection agent has no power to seize your belongings. | Ask for identification and evidence of the debt. You do not have to let a debt collector into your home. |
| Letter of claim | A creditor may send a formal pre-action letter before making a claim. | Follow the response deadline and get advice; do not ignore it. |
| Court claim | In England and Wales, a creditor may apply for a county court judgment. A judgment and later enforcement are separate stages. | Respond to the claim by the court deadline, whether admitting it, disputing it or asking for time to pay. Attend if the court requires a hearing. |
| Enforcement after judgment | Where legally permitted, a creditor may seek enforcement such as an attachment of earnings, charging order or warrant of control. | Get advice promptly about the specific notice, available objections and affordable payment options. |
What to Do If You Can’t Pay Your Debt?
Budget for essential living costs and priority debts first, such as rent or mortgage arrears, council tax and energy arrears. Only then consider using spare money for higher-interest non-priority debts while keeping required payments on other accounts. The highest interest rate does not always identify the most urgent debt.
Prepare a budget covering essential living costs and priority debts first. Propose only instalments you can afford, and obtain written acceptance and confirmation of any interest or action being paused. An offer alone does not guarantee agreement or stop a court claim.
If you can’t afford to pay via a repayment plan, you may need to consider a debt solution.
There are several options, depending on your financial circumstances. Many of these solutions are also some of the only debt write-off options in the UK.
We recommend speaking to a debt charity if you are thinking about debt solutions. Their advisers will be able to guide you through your options and find the best one for you.
Individual Voluntary Arrangement (IVA) or Trust Deed
An IVA is a formal insolvency arrangement with creditors. It can include agreed payments or other contributions and binds creditors covered by the arrangement once approved. Fees, effects on assets and credit, and the risk of failure need to be considered with an authorised insolvency practitioner.
An IVA sets out agreed contributions and restricts recovery of the included debts once approved. It does not prevent every required notice or other permitted contact.
An IVA can write off the unpaid balance of included debts on successful completion, subject to its terms. Excluded debts remain payable, and failure can leave you liable for remaining debt and further action.
There is no universal statutory requirement to owe several thousand pounds or have more than one creditor. Suitability depends on the debts, available income or assets, alternatives and the provider’s criteria.
Scotland has different debt remedies, including protected trust deeds, the Debt Arrangement Scheme and bankruptcy. A trust deed is one option, not a compulsory replacement for an IVA; ask a Scottish debt adviser which options fit your situation. A protected trust deed is a formal Scottish insolvency arrangement with conditions, costs and risks to assets and credit. Protection and discharge depend on its status and successful completion; it does not automatically cover every debt or prevent every type of contact. See trust deed guide.
Debt Relief Order (DRO)
In England and Wales, a Debt Relief Order may be available if qualifying debts are no more than £50,000, spare monthly income is no more than £75, assets are no more than £2,000 and any qualifying vehicle is worth no more than £4,000. Other conditions apply, including not owning your home. An approved adviser must assess eligibility. See Debt Relief Order guide.
During the usual 12-month DRO period, recovery of listed qualifying debts is restricted and you generally do not pay those debts. Ongoing bills and excluded debts still need attention. Creditors may send statements and other permitted correspondence.
Included debts are normally discharged at the end of the DRO period if the order remains in force. Changes in circumstances must be reported and can affect the order; excluded debts are not written off.
Bankruptcy or Sequestration
Bankruptcy or sequestration in Scotland is often the final step for some people.
Bankruptcy is a formal insolvency option with eligibility rules and serious consequences for assets, housing, credit and sometimes employment. It does not cover every debt. Get independent advice on all available options before applying.
Scotland’s Minimal Asset Process is a form of bankruptcy for people meeting specific debt, income and asset conditions. It has consequences for credit and finances and should be assessed with an approved money adviser. See Minimal Asset Process guide.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Ignoring Debt Letters from Moriarty Law
We always recommend responding to debt collectors – even just to question the debt’s validity.
If you dispute the debt, explain why and ask for an itemised balance and evidence that you are liable. For recovery covered by FCA consumer-credit rules, a valid or potentially valid dispute must be investigated and recovery paused. A generic proof request does not cancel a debt, override an existing court order or extend a court deadline.
What Rights do they Have?
The creditor, or solicitors acting for it, may bring a court claim if entitled to do so. Only the court can issue a judgment. A claim form is not a CCJ: respond within its deadline, as judgment can be entered in default without a hearing.
» TAKE ACTION NOW: Fill out the short debt form
A CCJ may require immediate payment or instalments set by the court. If the terms are unaffordable, seek advice promptly about asking the court to vary them.
Do not ignore a County Court judgment. If the payment terms are not met, the creditor can seek an authorised enforcement method, which may include a warrant or writ of control. Ordinary debt collectors cannot seize goods merely because a judgment exists. Obtain advice promptly if you need to challenge the judgment or change payments.
For ordinary civil debts, including council tax, an enforcement agent cannot force initial entry into a home. They may enter through a normal unlocked door where they have lawful authority, but cannot climb through a window or push past you. You can communicate through a closed door. Goods exemptions and ownership rules also apply; removal and sale are not automatic.
Can You Lose Your House Because of Moriarty Law?
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Can You File a Complaint?
Collectors must protect your privacy and must not unfairly disclose a debt to relatives, neighbours or an employer. They can communicate with an authorised representative or make other legally permitted disclosures. Contact must be proportionate and must not amount to harassment. An ordinary debt collector has no bailiff powers: it cannot force entry or seize your goods. You can decline a doorstep discussion and ask the visitor to leave. The creditor may still take lawful court action; authorised enforcement after judgment is a separate process.
If they violate these rules, you can complain.
Moriarty Law is an SRA -regulated law firm, SRA number 607528. The applicable financial-services rules and Ombudsman eligibility depend on the activity. See FCA handbook information.
If you think that any of these rules have been broken, you should first complain to Moriarty Law directly.
This will give them the opportunity to sort out your problem by themselves, per the Moriarty Law complaints process.
Complain to the firm first. The SRA deals with concerns about solicitors’ conduct; the Legal Ombudsman generally considers eligible complaints about your own legal-service provider. The Financial Ombudsman may consider eligible financial-services complaints. Check the relevant body’s jurisdiction and deadlines; a complaint does not stop court proceedings. For an eligible financial-services complaint, first complain to the firm. You can normally refer it to the Financial Ombudsman Service after a final response or eight weeks without one, usually within six months of the final response. The FCA does not decide individual debt disputes, and not every creditor or type of complaint falls within the Ombudsman’s jurisdiction.
Moriarty Law Debt Collection Contact Details
| Phone: | 0203 126 4544 Monday to Thursday – 9am – 5:30pm, Friday 9am – 5pm and Saturday 9am – 1pm |
| Postal complaints address | Moriarty Law Complaints Team, Cobb House, 2–4 Oyster Lane, Byfleet, KT14 7DU. Check the firm’s current details for other correspondence. |
| Website: | https://moriartylaw.co.uk/ |
| Email and online contact | Use the current customer-contact or complaints details on Moriarty Law’s official website. See Moriarty Law customer contact. |
There is no doubt that receiving a letter from Moriarty Law chasing you for debt can be stressful, and there may be all sorts of questions you have about dealing with this debt, as well as your general financial situation.
These are some of the most common questions being asked, and hopefully some useful answers.
References





