


Mortimer Clarke Solicitors Debt – Should You Pay?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Have you received a surprise letter from Mortimer Clarke Solicitors about a debt? You may be asking, should I pay this debt? Is this company real? Where has this debt come from? If you can’t pay, what will happen?
Check the creditor, amount and legal stage before responding. A solicitor’s letter can require urgent attention, but it is not itself proof that the claimed debt is correct.
In this post, you’ll learn:
- Who Mortimer Clarke Solicitors are.
- If you should pay the debt they say you owe.
- Ways you can manage this debt.
- If Mortimer Clarke Solicitors and Cabot are the same.
- How to deal with Mortimer Clarke Solicitors.
Keep the letter and related account documents. Free debt advice can help if you dispute the account or cannot afford the requested payment.
Let’s figure out your options together.
Why are Mortimer Clarke Solicitors contacting you?
There could be several reasons why you’ve received a call or letter from Mortimer Clarke Solicitors. Often, the most likely reason is over an outstanding debt that they’re trying to collect.
Although the name Mortimer Clarke Solicitors may not mean much to you, they’ll likely be collecting on behalf of another company, such as a bank, credit card provider, or hire purchase company.
Mortimer Clarke acts as a law firm for clients. Do not assume it bought your account, or infer the amount you owe from a supposed average debt-purchase price.
Usually, the original company owning the debt will try and get in touch before they refer your case to Mortimer Clarke. If you’ve not received such letters or you’ve ignored them, the company will escalate their efforts or sell your debt to another company.
Only the court can issue a County Court Judgment. Taking control of goods for an ordinary unsecured debt requires a further lawful enforcement step; bailiffs are not an alternative that a collector can send merely because you are uncooperative.
A claim can proceed even if you have been corresponding with the creditor. Meet the court’s deadlines; a default judgment can arise without a hearing if papers are not answered.
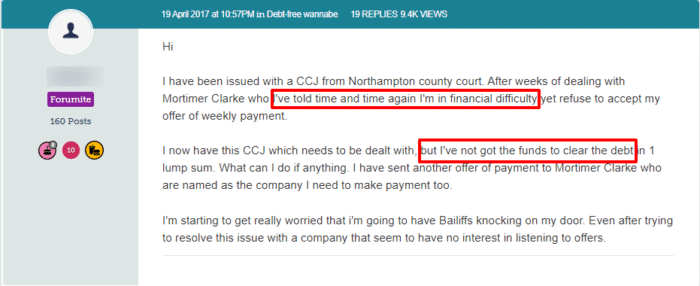
If you do have a CCJ against you but, like this person, you will have difficulty paying it, you have some options.
You can go back to the court and tell them that you can’t afford it. You will need to provide information about your income and spending habits. If you are in this position but need more information, we recommend contacting a debt charity.
StepChange has a lot of information on this subject.
Of course, in some rare instances, you may receive a letter from Mortimer Clarke Solicitors in error. Someone who previously lived at your address or someone with a similar name may actually be responsible for the debt.
Are Cabot and Mortimer Clarke the same company?
Mortimer Clarke Solicitors Limited identifies itself as part of the Cabot Credit Management group and is regulated by the Solicitors Regulation Authority. It is a separate legal entity, not the SRA itself. See related guidance.
Regulation imposes duties, but does not guarantee that every claim or letter is correct.
Check the genuine firm’s current regulatory record and official contact details before sharing information or paying.
The firm’s published company number is 06211733. A copied company number or name does not authenticate correspondence, so verify any unexpected demand independently.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
How to deal with Solicitors
There are some simple steps for dealing with debt collection agencies like Mortimer Clarke Solicitors. By following these, you can hopefully resolve the matter in a way that’s beneficial to everyone.
1. Don’t ignore them
Although it’s tempting to dodge calls or throw letters in the bin, ignoring debt collection agencies is never a good idea. You may feel scared about not being able to repay the money or feel that it’s not your debt in the first place.
However, ignoring the matter won’t make it go away.
The firm may take further lawful steps on its client’s behalf. Check whether the letter is an ordinary demand, a Letter of Claim or court correspondence and respond accordingly.
A threatened ordinary collection visit does not authorise entry or seizure. Court and enforcement papers have separate procedures.
A CCJ normally stays on the register and credit file for six years from judgment. Paying the full judgment within one calendar month can allow the entry to be removed; paying later normally marks it satisfied rather than removing it. The debt does not automatically expire when the entry disappears.
Don’t let it get to this stage.
If you dispute the debt, explain why and ask for an itemised balance and evidence that you are liable. For recovery covered by FCA consumer-credit rules, a valid or potentially valid dispute must be investigated and recovery paused. A generic proof request does not cancel a debt, override an existing court order or extend a court deadline.
2. Get your details in order
Once you receive a letter or call from Mortimer Clarke Solicitors, you’ll want to get your details in order before dealing with them. Carefully read the letter(s) they sent to understand the details of what they’re requesting.
There will be some information about who you owe money to and how much. They may also provide a date they want you to repay it by. If you can, find out any statements or paperwork related to the initial debt. Look for credit card and bank statements and credit agreements.
You’ll want to have these handy when you’re dealing with the debt collection agency. It may also refresh your mind about what exactly they’re trying to collect.
This step is also important for identifying whether or not you actually owe the amount they say you do. Act quickly, but remain composed.
3. Know your legal rights
It can be intimidating when you receive contact from a debt collection agency or similar organisation. You may be worried about losing your possessions, vehicle, or even your home.
Ask for advice early if assets, secured borrowing or court enforcement may be involved. Taking action helps you understand the options but cannot guarantee that legal enforcement will be avoided.
Firstly, Mortimer Clarke Solicitors aren’t a bailiff. This fact means that they can’t directly reclaim your possessions to cover the cost of your debt.
They also can’t force entry into your home and must leave your premises if you ask them to.
A firm must avoid harassment, misleading pressure and inappropriate disclosure. It can communicate with an authorised adviser or representative and send necessary legal documents.
It’s important that you know all your rights when facing a situation like this to have an edge over the debt collectors. Here’s a small table summarizing the key aspects.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
» TAKE ACTION NOW: Fill out the short debt form
4. Contact Mortimer Clarke Solicitors Limited
Once you’re familiar with what Mortimer Clarke Solicitors Limited want from you, you can get in touch with them. By this point, you should also know what your legal rights are and whether or not you owe what they say you do.
You can contact the business in several ways. They may give details on the letters they send you, and you can also check out their contact page for more information. They offer three main ways to get in touch:
| Address: | 16-22 Grafton Road, Worthing, West Sussex, BN11 1QP |
| Post: | Mortimer Clarke SolicitorsPO Box 130, BLYTH, NE24 9FA |
| Telephone: | 0330 045 0779 Monday – Friday 8.00am – 8.00pm Saturday 9.00am – 1.00pm Sunday Closed |
| Email: | [email protected] |
| Website: | https://www.mortimerclarke.co.uk |
Make a written record of any dispute and retain proof of submission or posting. Tracked delivery can help show delivery, but does not itself guarantee the firm has accepted your position.
5. Don’t let them enter your property
If you don’t contact Mortimer Clarke Solicitors after they write to you, they may write to you again to let you know they’re going to visit your home.
There is no universal seven-day notice rule for ordinary debt-collector visits. Bailiff Notices of Enforcement are different and have their own current statutory requirements.
An ordinary debt collector has no power to force entry or take goods. It may request a voluntary visit or payment, but you can refuse entry and ask it to leave. Bailiff enforcement requires separate lawful authority.
Refusing an ordinary visit does not itself authorise bailiffs. Continue to address the underlying debt and any legal documents.
For an ordinary unsecured debt, taking control of goods normally requires judgment and a separate warrant or writ. Enforcement is subject to limits and protected-goods rules.
6. Get them to confirm the debt
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
You can create what is known as a ‘Prove the Debt’ letter.
Use a template only for a genuine dispute and adapt it to the account. Share information safely through a verified route; do not assume the firm will misuse a signature or that a request cancels the debt.
7. Think about paying them back
If the debt is correct, check essential expenses and priority debts before agreeing affordable repayment or another suitable option.
Ask for confirmation of any agreement. Payment or a debt solution does not necessarily remove an accurate default or stop every required notice.
Often, you’ll be able to pay the outstanding amount either on the phone or online. The letters you’ve received from the company will have a reference number to use, and should detail exactly what you need to do. They often provide a range of ways for you to make the outstanding payment.
8. Speak about payment plans
You may not be able to pay the full amount in its entirety. If this is the case, you should consider contacting Mortimer Clarke Solicitors to see whether they’ll accept a payment plan.
They may let you pay back a small amount each month until the debt is paid off. Often, debt collection companies will try and accommodate your plans to repay the money.
The firm should consider applicable forbearance duties, but is not obliged to accept every proposed figure. Provide a realistic budget and seek advice if terms are unaffordable.
Do not promise an amount that leaves essential living costs unpaid. Ask for an arrangement to be confirmed in writing.
9. Check whether the debt is statute-barred
Many ordinary unsecured debts may become statute-barred after six years in England and Wales, or prescribed after five years in Scotland. The start date, debt type, payments, legally relevant acknowledgments and any court claim all matter. A creditor’s letter alone does not restart the period. Ask a debt adviser to check the facts before paying or admitting liability, and respond to any court papers on time.
In England and Wales, limitation generally restricts a court remedy rather than automatically cancelling a simple-contract debt. Scottish prescription can extinguish an obligation; different rules apply to judgments and some public debts.
Keep in mind that not all debts become statute-barred!
A CCJ does not automatically expire after six years, although some later enforcement steps need court permission. Tax debts also have special rules; avoid applying a single time limit to all HMRC accounts.
10. Check other debt solution options
There are several options for debt solutions in the UK, some of which will allow you to clear some of your unsecured debts.
We recommend speaking to a debt charity before starting a plan so you know that you are doing what’s best for your finances.
Debt Management Plan (DMP)
A DMP is an informal debt solution that lets you pay off your debts via a single monthly payment.
A DMP is generally voluntary and aims to repay included unsecured debts in full. Creditors are not automatically required to freeze interest or stop legal action.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency arrangement managed by an insolvency practitioner. Your proposal sets out payments, any assets involved and fees. Once approved, it binds the creditors and debts covered by it and restricts recovery action; it is not a blanket ban on necessary correspondence.
Many IVAs involve payments for five or six years, but the agreed term varies. Qualifying unpaid debt is normally released only on successful completion. An IVA affects your credit record, may involve assets or home equity, and can fail if its terms are not met.
IVA suitability depends on your debts, affordable contributions or available assets, fees and creditor approval. There is no universal rule that you must owe several thousand pounds to more than one creditor. Get independent debt advice and compare other options before agreeing to an IVA.
Trust Deed
IVAs are not available in Scotland. A Scottish money adviser can compare a protected trust deed, the Debt Arrangement Scheme, sequestration and informal arrangements; a trust deed is not compulsory.
A protected trust deed is a Scottish insolvency arrangement, usually lasting at least four years of contributions. It can discharge qualifying unpaid debt on successful completion, but fees apply and your home or other assets may be at risk. Covered creditors cannot pursue payment outside it, but can still send required documents.
Debt Relief Order (DRO)
In England and Wales, a DRO may suit an eligible non-homeowner with low surplus income, limited assets and qualifying debts within the £50,000 limit. Detailed income, asset, vehicle and residence rules apply. An approved debt adviser checks eligibility and submits the application to the Insolvency Service.
During a DRO, included qualifying debts are protected from most recovery action under the moratorium rules. This is not a ban on every necessary communication, and excluded debts and ongoing bills still need attention.
A DRO normally lasts 12 months. If it remains in force, the qualifying debts listed in it are normally discharged at the end. You must report relevant changes and continue paying ongoing bills and excluded debts, such as court fines and student loans.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, insolvency is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is the Scottish version of bankruptcy.
An approved Scottish money adviser can assess eligibility for the Minimal Asset Process (MAP), a form of sequestration, and compare other suitable options. Eligibility and consequences must be checked; it is not automatically the best choice for everyone with a low income. See related guidance.
The suitability of insolvency depends on current circumstances, not how many people entered it in a past year. Obtain independent advice before agreeing to a formal solution. See related guidance.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How Can You Complain About Mortimer Clarke?
Complain to Mortimer Clarke about the specific conduct and retain evidence. Financial-service and solicitor-regulation routes have different eligibility and purposes. See related guidance.
Make your first complaint to Mortimer Clarke so that they have the chance to sort out the issue themselves. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
The SRA can consider reports of serious professional misconduct; it is not a general debt-appeal service. Eligibility for the Legal Ombudsman depends on the relationship and complaint, so an opposing party should not assume access to that route. See related guidance, related guidance.
Final Thoughts
Although it can be unpleasant receiving contact from debt collectors such as Mortimer Clarke Solicitors, it’s not the end of the world. The important thing is that you don’t ignore their correspondence and hope they go away – they won’t.
With a little bit of know-how and preparation, you can start taking the right steps to deal with the problem.
Free debt advice is available from organisations such as StepChange and National Debtline. An adviser can assess liability, affordability and suitable options, but cannot guarantee that the debt will be cleared. See related guidance.
References





