


PayPlan and StepChange: Services, Fees and Choosing Help


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
PayPlan and StepChange both offer free debt advice and Debt Management Plans. The right choice depends on the service you need and whether the recommended solution suits your circumstances.
We’ll answer your questions about:
- The role of PayPlan in a debt management scheme
- How StepChange can help with a Debt Management Plan (DMP)
- Ways to write off some debt
- The differences and similarities between PayPlan and StepChange
- How to contact StepChange and PayPlan
Debt can involve both credit commitments and priority household bills. Keep rent, energy and other essential costs in the budget before offering DMP payments.
Compare the advice, fees and ongoing support before choosing a service; there is no single best provider for every person.
What is the role of PayPlan in a debt management scheme?
PayPlan is one of the largest debt advice providers in the UK.
They offer free help and financial advice to their customers to help them get rid of their debt problems. Payplan is funded through contributions from the credit industry and commercial partners.
Moreover, they provide freephone debt line and debt help tools through their website.
How can StepChange help with a DMP?
If you have a Debt Management Plan with a commercial debt management company, your monthly payments could be going to the debt management company as fees.
However, switching to a Stepchange Debt Management Plan will make all your monthly payments go towards paying your debt.
This could help you pay off your debts faster.
You can also get other debt solutions and debt relief from Stepchange. They will be able to talk you through their options when you speak to their advisers.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What are the similarities?
Both provide free debt advice and DMPs. Fees can apply to other solutions, including IVAs arranged through associated insolvency providers.
They provide confidential debt advice which is for free. The advice could be taken through a call or online.
Free advice and a free DMP do not mean that every product or insolvency procedure is free. Ask for a written explanation of the costs of any recommended solution.
» TAKE ACTION NOW: Fill out the short debt form
What is the difference?
While both offer free debt advice and debt management plans, there are some differences between the two.
Payplan provides help with a large number of debt solutions, such as IVAs (through their partner companies).
PayPlan is a company, funded by donations from the credit industry, while Stepchange is a registered charity.
Stepchange also offers some debt solutions, including IVAs through Stepchange Voluntary Arrangements.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
What if I am unhappy with their services?
Individual experiences vary. A positive review or a provider’s size does not guarantee a particular outcome.
If you are unhappy with either company, the best thing to do is make a complaint to them.
Follow StepChange’s current complaints procedure and keep a copy. An acknowledgement or investigation target is not a guarantee that every complaint will be resolved within four weeks. See related guidance.
Follow PayPlan’s current complaints procedure. If the issue cannot be resolved promptly, ask for confirmation of the investigation and the expected response date. See related guidance.
Complain first to the firm and named insolvency practitioner. Unresolved complaints about a practitioner’s conduct can go through the Insolvency Service Complaints Gateway to the relevant regulator. The Financial Ombudsman may handle a separate eligible complaint about regulated debt advice; it does not automatically cover insolvency-practitioner work. The FCA does not resolve individual claims. See related guidance.
For an eligible financial-services complaint, you can normally go to the Ombudsman after a final response or eight weeks without one, usually within six months of the final response. Redress depends on what it finds; it is not automatic.
What do people say?
The reviews below are individual historical examples, not a current representative survey of either service.
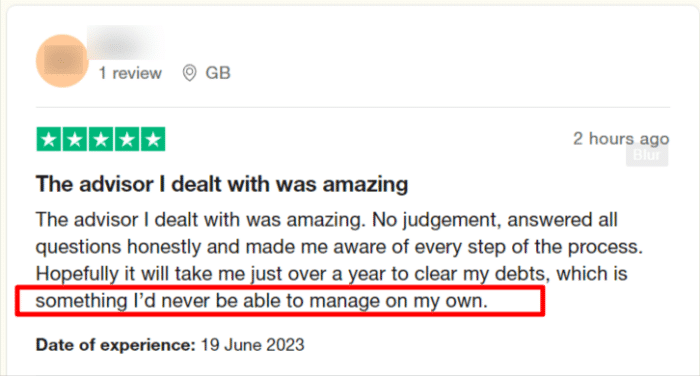
This person used Payplan to start clearing their debts. Sometimes having some extra support can make all the difference!
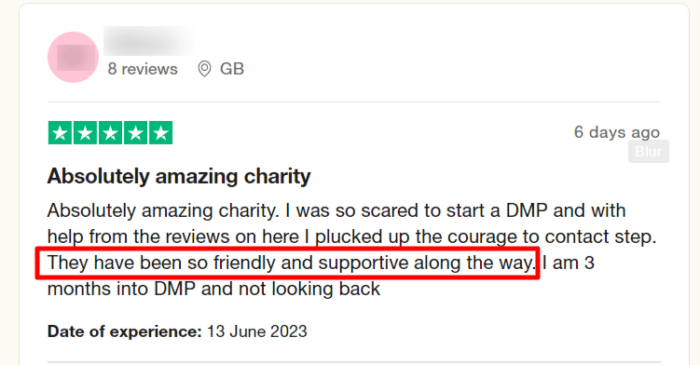
This reviewer used Stepchange to get their DMP up and running.
Contact a free debt-advice service to compare suitable options. Ask which legal entity provides the advice and which practitioner would handle any insolvency arrangement.
Payplan Contact Information
| Phone: | 0800 280 2816 |
| Registered Office: | Kempton House, Dysart Road, PO Box 9562, Grantham, NG31 0EA |
| Website: | https://www.payplan.com/ |
Stepchange Contact Information
| Phone: | 0800 138 1111 |
| Online Debt Advise Service: | https://www.stepchange.org/setting-expectations.aspx |
| Website: | https://www.stepchange.org/ |
References





