Personal Loan for Home Improvement – In-depth Guide


Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Is it time to hit the refresh button on your home? From new furniture or something more significant like a loft conversion, it all costs a pretty penny.
If you want to complete a home update soon, you should know about your options when it comes to getting a personal loan for home improvement. There are different types of personal loan for home improvement and the best option for you will depend on eligibility and personal circumstances.
Read on to discover what method of financing home improvements could work for you, and speak with a money advice group or commercial service provider for further support.
Can you get a loan for home improvements?
When you want to borrow to pay for home improvements, there are many options which we will discuss below. Using a bank loan is one method of financing your renovation, but there are even different types of bank loans to choose from that can be used for this purpose.
Compare suitable lenders and verify their FCA permissions and genuine contact details. Authorisation is a necessary check, not proof that every product is suitable or affordable. See related guidance.
If a loan company approaches you to offer a loan it could be a sign that they are not authorised and are in fact a scam lender.
What is the best one to take out?
The best loan for home improvements will depend on the terms and conditions of the loan you’re offered, which will be based on your finances and your credit score. There is no “best loan for home improvements” but there are some popular options you should check out and compare.
Here are some of the most used methods of paying for home improvements:
- Secured and unsecured home improvement loans
A loan marketed for home improvements may restrict how the money is used. Check the agreement and disclose your actual purpose; terms vary. See related guidance.
These personal loans provide the homeowner with a lump sum amount which is then repaid through a monthly repayment plan made up of principal repayments and interest. Monthly repayments continue for a fixed period until you have paid all of the loan back.
A home improvement loan could take the form of unsecured loans or a secured loan. The former means no assets are listed in the credit agreement as collateral. If you do not repay an unsecured loan the lender has no right to seize any assets or force you to sell your home. But they can take you to court and if the debt escalates they may get these permissions eventually.
The loan is secured on the property. Missed payments can lead to repossession through the applicable legal process; security does not remove affordability checks or give the lender an automatic right to take the home without that process.
- Personal home improvement loans
A generic personal loan may also be used to fund your new kitchen, bathroom or any other renovation project. Sometimes a lender that offers a personal loan will simply re-advertise it on another web page as a home improvement loan and car loan to appeal to people searching for these loans.
A general personal loan may allow several purposes, but restrictions still apply. Do not assume a lender will not ask how funds will be used.
- Home equity loans
A secured homeowner loan is borrowing against the property. Equity is its current value less all secured debts: a £185,000 home with an £85,000 mortgage and no other secured debt has £100,000 equity.
Illustration only: an 85% combined loan-to-value limit on that £185,000 home gives £157,250 total secured borrowing. Less the £85,000 mortgage, the theoretical extra amount is £72,250 before fees and other restrictions, not £85,000. Actual affordability and lending limits may be lower.
- Remortgaging
A mortgage is a type of bank loan to buy a property, and it can also be used to fund house renovations if you have built up enough home equity. Scores of homeowners switch from their current mortgage deal to another one to get a better interest rate. However, you can also remortgage to borrow more against the property.
For example, refinancing an £85,000 mortgage with £100,000 could release £15,000 before fees, if approved. The new lender must permit the purpose, and costs or a longer term may outweigh a lower rate.
- Second charge mortgages
Second charge mortgages are similar to overborrowing through remortgaging, but instead of trading in your existing mortgage for a bigger one, the homeowner simply takes out a second mortgage on the same property, secured against home equity. The money can then be used to pay for your new kitchen, bathroom or any other small or large renovation project – but not exclusively.
This may be preferential if the current mortgage is a good deal and you don’t want to pay early repayment fees to pay off the first mortgage.
Enquire about a secured loan through Loans Warehouse, a credit broker, not a lender. Approval and terms depend on checks. Compare the full cost before applying. MoneyNerd may receive a referral fee. Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Where can you get it?
Taking out a loan for home improvements is possible with many different types of lenders. The most obvious places to look are banks and building societies. But you should also check out lenders that exclusively offer loans online. Moreover, many supermarkets and even the Post Office offer loans that can be used for renovations. You can usually apply for a home improvement loan online and get a decision quickly.
As long as the lender is a legitimate lender then you should consider their products and compare them with other legitimate personal loans for home improvement.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. A lower monthly payment may mean paying more overall, and secured borrowing puts your home at risk if repayments are not maintained.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
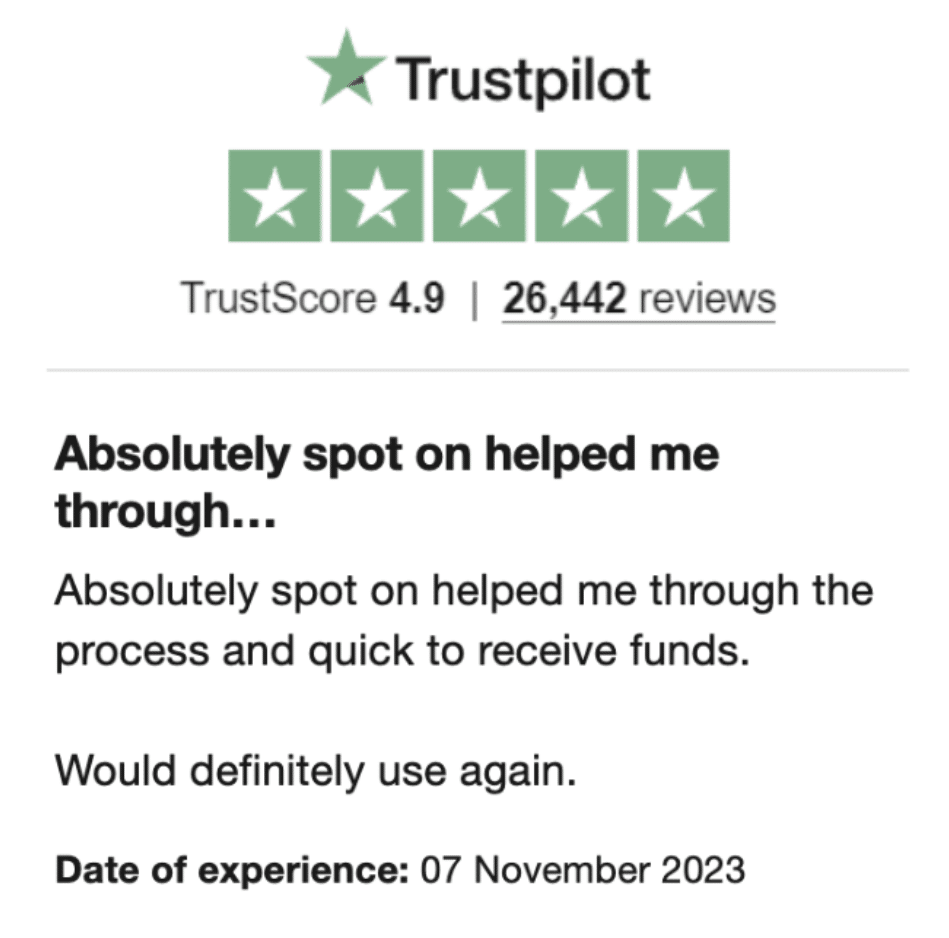
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
How to get one
To get a personal loan for home improvement projects will require you to pass the lender’s assessment that ensures the loan will be affordable. The lender carries out these assessments as part of their responsible lending commitment. Not making sure you can afford the loan could mean they don’t get their money back, and it could lead to significant debts.
When you apply for a loan for home improvement, the lender will ask about your income and existing debts. If you’re securing an asset within the credit agreement, they may need to value these, also known as an appraisal.
They’ll also check your credit score to see how you have managed monthly repayments to other banks and lenders in the past. It is an accumulation of these things that will decide if you are offered the money you need for renovations or not. Each lender has its own determinations and there is no fixed benchmark you need to hit to be accepted.
How to compare loans
For a regulated consumer-credit promotion using a representative APR, that rate or lower must be expected to apply to at least 51% of credit agreements entered into as a result of the promotion. It is not a promise to 51% of everyone who applies, and the rule should not be applied indiscriminately to mortgage APRC illustrations. See related guidance.
A representative APR is not the average rate offered to applicants. Compare the personalised offer and total amount payable.
Sometimes a maximum APR you could be offered is also advertised, so you’re aware of the highest rate possible if approved.
A calculator estimates payments using its stated amount, rate and term. It is not a lending offer, eligibility confirmation or suitability assessment. Compare the personalised terms and total cost before applying.
Include arrangement, broker, valuation, legal and settlement charges where applicable. Mortgage illustrations use APRC and product-specific disclosures; do not assume US-style closing costs apply.
Getting a loan with bad credit
If you want a personal loan for home improvement plans but know you have bad credit, there might be a solution. Homeowners with poor credit will always find it harder to secure a loan over those with excellent credit scores. But it doesn’t make it impossible. Some lenders even advertise a home improvement loan for bad credit. You may want to look at these options first.
Security may affect the lender’s terms, but does not replace affordability and credit checks or guarantee approval. It exposes the asset to enforcement if you default.
Things to consider
Before you take out a home improvement loan, you need to consider:
- Are you willing to use an asset as collateral in the loan agreement?
- What type of loan options are available to you? Those without home equity will have fewer options.
- How much do you need for the project?
- How long would you need to repay?
- Your credit score – check it for mistakes before applying. A lender’s mistake could cause a rejection.