


Is PIP Classed as Income? UK Tax Laws


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you wondering if PIP is classed as income? You’ve come to the right place for answers. Each month, over 170,000 people visit our website seeking guidance on debt matters.
In this article, we’ll answer the following questions:
- What is Personal Independence Payment (PIP)?
- How to apply for PIP and how it is assessed?
- How PIP is linked with Disability Living Allowance (DLA)?
- Is PIP counted as a benefit or income, and is it included in Debt Management Plans (DMP)?
- How PIP can be used to pay off debts and its relation to council tax and housing benefit?
We understand how hard it can be to manage debt, as some of our team members have been there too.
With our experience, we’ll help you understand if PIP is classed as income under the 2023 UK Tax Laws and how this affects your financial situation.
Is PIP counted as income?
PIP is a type of income, but it is not subject to taxation.
You will not have to pay any tax back on it, and there is not even an obligation to spend the money on things related to your disability.
There are other benefits that are not classed as income for fiscal purposes, such as Child Benefit, Attendance Allowance and Bereavement Support.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
Is it classified as income for council tax?
Anyone paid PIP will be eligible for a reduced rate of local authority tax (if you pay it!).
The amount of money you can get deducted from your bill will depend on the component of PIP you receive and at which rate. I suggest you contact your local authority for assistance.
Also, anyone who receives PIP might be applicable for an additional award on other their other benefits.
If you receive any of the following benefits, you could receive a top-up payment:
- Income Support
- Pension Credit (Living component only)
- Universal Credit
- Working Tax Credits
- Employment and Support Allowance (Living component only)
Is Personal Independence Payment counted as income for housing benefit?
PIP can increase the amount of housing benefit money you receive.
If you receive either component of PIP, you automatically qualify for a premium top-up payment on any housing benefit you get.
Your housing benefit money could increase if your child (aged between 16 and 20) receives PIP and is still in training or education.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Do you include it as income on a DMP?
If you are setting up a Debt Management Plan (DMP), you can take two approaches to declare PIP as income or not.
Both of these approaches are likely to lead to the same end result.
Option 1: You might want to not include PIP as declared income, but simultaneously not include any living expenses and costs associated with your disability.
As PIP is given to you to cover these costs, by excluding everything, you are keeping the records correct.
Option 2: Include all the pay you receive from PIP, but make sure you also include all the expenses you are frequently paying from the funds you receive.
If you are applying for a more formal debt solution, such as an Individual Voluntary Arrangement (IVA), you should consult with your Insolvency Practitioner (IP) when declaring your income.
Can you use PIP to pay off your debts?
It is your decision if you want to use PIP to repay some of your debt.
Using PIP for debt repayment is less of a risk if you are doing so as part of a DMP because if your situation changes, you can ask to change the DMP as it is not legally binding.
This is not the same for an IVA.
For more information on practical debt solutions, check out our debt solutions guide.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Can it be classed as a benefit?
PIP is classed as a benefit payment, but it is different from other benefits because it’s not income-based.
PIP is financial aid without income restrictions.
In other words, the payments are awarded to you no matter how much savings you have.
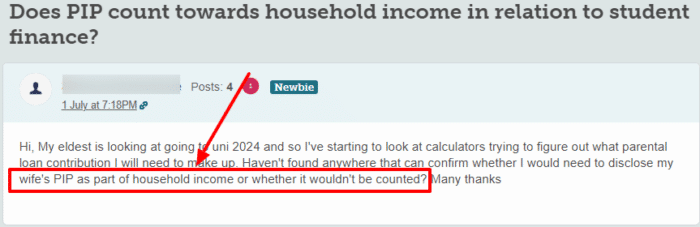
Remember, PIP is not a taxable benefit, and therefore, you don’t need to include it when declaring your household income.





